Reader support is what makes Oracle Ayano Project possible. I am pouring my heart into building a generative AI system for large-scale data gathering, analytical synthesis, and article verification, so each piece can offer both accuracy and a fresh perspective. Please consider supporting the project.
Good morning. Yields at 4.738% on the 10Y UST and a soft dollar frame today’s cross‑asset flows, lifting gold while compressing duration‑sensitive equity math. Freight is tightening again (SCFI +1.6% weekly; BDI ~2,841), raising landed costs into Q4. Nvidia’s $105B‑backed, 4.25 GW AI campus extends multi‑year capex into chips, power and real assets. A 2:00 p.m. EDT U.S. sanctions announcement on Iran is the near‑term oil and shipping swing factor.
Stocks and FX
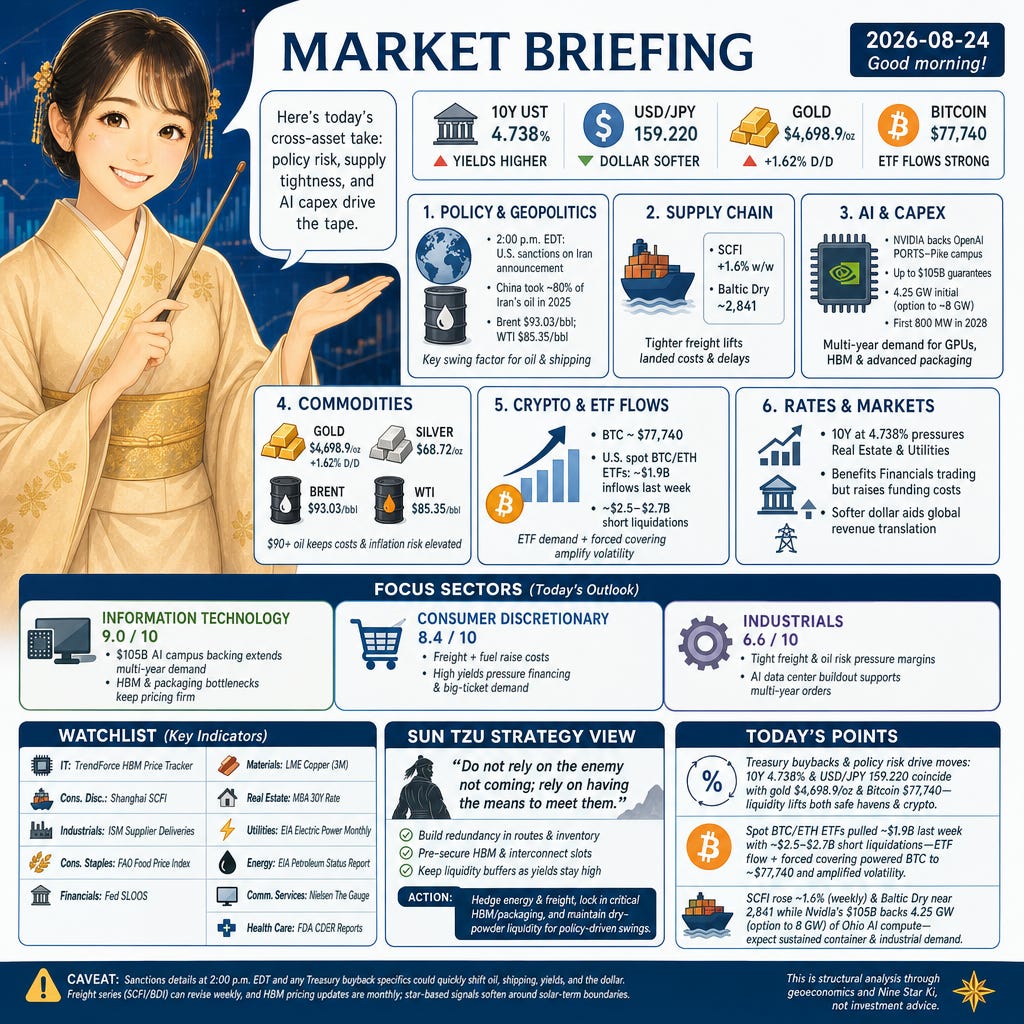
USD/JPY 159.220, EUR/USD 1.1669, the S&P 500 7,674, and the 10Y UST at 4.738% anchor today’s tape, per Reuters (Tom Westbrook). The softer dollar aids translation for global software and device revenues, while higher long‑end yields pressure Real Estate and Utilities via discount rates and funding costs. For Financials, elevated yields complicate net interest margin and raise wholesale‑funding expense even as trading revenues benefit from volatility. FX and rates positioning should assume policy‑speech risk later in the week.
Commodities
Gold at $4,698.9/oz (+1.62% d/d, +6.36% w/w) and silver at $68.72/oz extend the bullion bid as the dollar stays subdued; Brent sits at $93.03/bbl and WTI at $85.35, per Reuters. Higher gold supports Materials via miners and ETF flows, while $90+ oil keeps transport and packaging costs elevated for Consumer sectors and Industrials. If oil volatility persists, inflation expectations can feed back into yields, tightening financial conditions for duration‑heavy equities.
World Affairs
At 2:00 p.m. EDT, Washington plans to unveil the “toughest” Iran sanctions, which Tehran dismissed as futile, Reuters reports. With China estimated to have taken ~80% of Iran’s shipped oil in 2025 (Kpler in coverage), enforcement ambiguity will set the near‑term price deck for Brent ($93.03) and maritime insurance premia. Any perceived curtailment risk lifts Energy margins but raises input and freight costs for Industrials, Materials, and Consumer goods moving through Middle East routes.
Supply Chain
The SCFI rose ~1.6% w/w while the Baltic Dry Index hovered near 2,841, IndexBox notes, pointing to tighter ocean capacity. Higher container and bulk rates raise landed costs and working capital for Retail and Electronics supply chains, and elongate reorder cycles. Industry commentary on Panama Canal draft limits suggests September transits could tighten further, adding time and insurance buffers into schedules. Expect modest lead‑time drift and more frequent surcharge pass‑throughs.
AI
NVIDIA’s Form 8‑K and Bloomberg reporting detail up to $105B in guarantees and a $1.5B equity stake backing OpenAI’s PORTS‑Pike campus: 4.25 GW initially with an option toward ~8 GW; first 800 MW targeted for 2028. This entrenches multi‑year demand for GPUs, HBM (high‑bandwidth memory), and CoWoS advanced packaging, while raising grid‑interconnection and substation capex for Utilities and shell demand for Real Estate. Chip supply remains bottlenecked at HBM and packaging, keeping pricing firm.
Industry News
Bitcoin traded near $77,740 as U.S. spot BTC/ETH ETFs reportedly drew about $1.92B last week, Cointelegraph/The Block report, with $2.5–$2.7B in short liquidations cited across commentary. The ETF bid and forced covering lift exchange and ETP revenues (Financials) and ripple into IT/payment rails, but also amplify derivatives VaR and collateral needs. Elevated crypto volatility can widen spreads and funding haircuts intraday.
Industry Forecast
Today’s Setup
2026-08-24 is a Six White Metal (Roppaku Kinsei, 六白金星) day within a Two Black Earth (Jikoku Dosei, 二黒土星) month and a One White Water (Ippaku Suisei, 一白水星) year during Risshuu (Beginning of Autumn). Execution and scheduling dominate: watch landed‑cost pressure from freight and $90+ oil, financing math under a 4.738% 10Y, and throughput advantages for operators who can secure HBM/packaging, grid interconnects, and shipping slots.
Focus Sectors
Information Technology (9.0/10): $105B in guarantees and a 4.25 GW initial AI campus commitment (NVIDIA 8‑K; option toward ~8 GW) extend multi‑year demand for GPUs, HBM, and CoWoS packaging. A softer dollar helps software and device revenue translation, but SCFI’s +1.6% w/w uptick lifts landed costs for components. The bottlenecks are clear: HBM capacity and advanced packaging. Implication: pricing and backlog visibility stay firm for compute suppliers, while device makers manage freight and memory procurement cadence. Watch export‑control headlines and any slip in HBM lead times.
Consumer Discretionary (8.4/10): The margin line runs through logistics and fuel: SCFI +1.6% w/w and Brent at $93.03/bbl increase freight and surcharge exposure just as travel and cross‑border commerce benefit from a softer dollar. Financing remains a headwind for big‑ticket categories and BNPL as the 10Y UST sits at 4.738%. Near term, operators with dynamic pricing and diversified carriers can defend gross margin; slower pass‑through compresses it. Monitor oil policy headlines and credit‑approval rates for signs of demand elasticity.
Industrials (6.6/10): Freight stays tight (BDI ~2,841; SCFI higher) and sanctions risk on Iran raises fuel and insurance premia, pressuring backlog margins where indexation is weak. Counterbalancing, Nvidia’s Ohio data‑centre program (first 800 MW slated for 2028 within a 4.25 GW initial plan) supports multi‑year orders for electrical gear, heavy machinery, and construction services. Elevated yields can defer customer capex and stretch approvals. Focus on projects with cost pass‑through and secured routes; disruptions or rate spikes elevate working capital needs.
Watchlist
Information Technology: TrendForce HBM price tracker (monthly high‑bandwidth memory contract pricing and supply outlook).
Consumer Discretionary: Shanghai Shipping Exchange SCFI (weekly container freight rates from Shanghai by lane).
Industrials: ISM Manufacturing PMI — Supplier Deliveries (monthly index of delivery times; tighter readings signal rising bottlenecks).
Consumer Staples: FAO Food Price Index (monthly global basket of food commodity prices published by the UN FAO).
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey on Bank Lending Practices — quarterly lending standards and demand).
Materials: LME Copper 3‑month price (London Metal Exchange benchmark for industrial metal demand and inventory tightness).
Real Estate: MBA Weekly Mortgage Applications — 30‑year contract rate (Mortgage Bankers Association; weekly borrowing cost for U.S. households).
Utilities: EIA Electric Power Monthly (generation mix, retail sales, and capacity additions across U.S. utilities).
Energy: EIA Weekly Petroleum Status Report (U.S. crude and product inventories, refinery utilization, and imports/exports).
Communication Services: Nielsen ‘The Gauge’ (monthly U.S. streaming and TV viewing share, a proxy for ad inventory mix and platform traction).
Health Care: FDA CDER Drug and Biologic Approval Reports (monthly approvals and major decisions impacting pipeline value).
Caveats
Sanctions details at 2:00 p.m. EDT and any Treasury buyback specifics could quickly shift oil, shipping premia, yields, and the dollar, changing today’s read. Freight series (SCFI/BDI) can revise weekly, and HBM pricing updates are monthly; star‑based signals soften around solar‑term boundaries, though Risshuu is already in effect.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With oil at $93, freight tightening, and chip packaging still scarce, the risk is not whether shocks arrive but whether operators can absorb them. Build redundancy in routes and inventory, pre‑secure HBM and interconnect slots, and keep liquidity buffers as yields stay high.
Action: Hedge near‑term energy and freight, lock in critical HBM/packaging capacity, and maintain dry‑powder liquidity for policy‑driven swings.
Today’s Points
Treasury buybacks and policy risk are driving cross‑asset moves: 10Y UST 4.738% and USD/JPY 159.220 coincide with gold at $4,698.9/oz and Bitcoin $77,740, showing liquidity is lifting both safe havens and crypto.
Spot BTC/ETH ETFs pulled roughly $1.9B last week and coincided with a $2.5–$2.7B short‑liquidation window—this ETF flow plus forced covering powered BTC to ~ $77,740 and amplified volatility for Financials and IT desks.
Supply and capex linkage: SCFI rose ~1.6% (weekly) and the Baltic Dry sits near 2,841 points while Nvidia’s $105B guarantee backs an initial 4.25 GW (option to 8 GW) of Ohio AI compute — expect sustained container and industrial demand as data‑centre buildout scaffolds multi‑year supply‑chain orders.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.