Reader support is what makes Oracle Ayano Project possible. I am pouring my heart into building a generative AI system for large-scale data gathering, analytical synthesis, and article verification, so each piece can offer both accuracy and a fresh perspective. Please consider supporting the project.
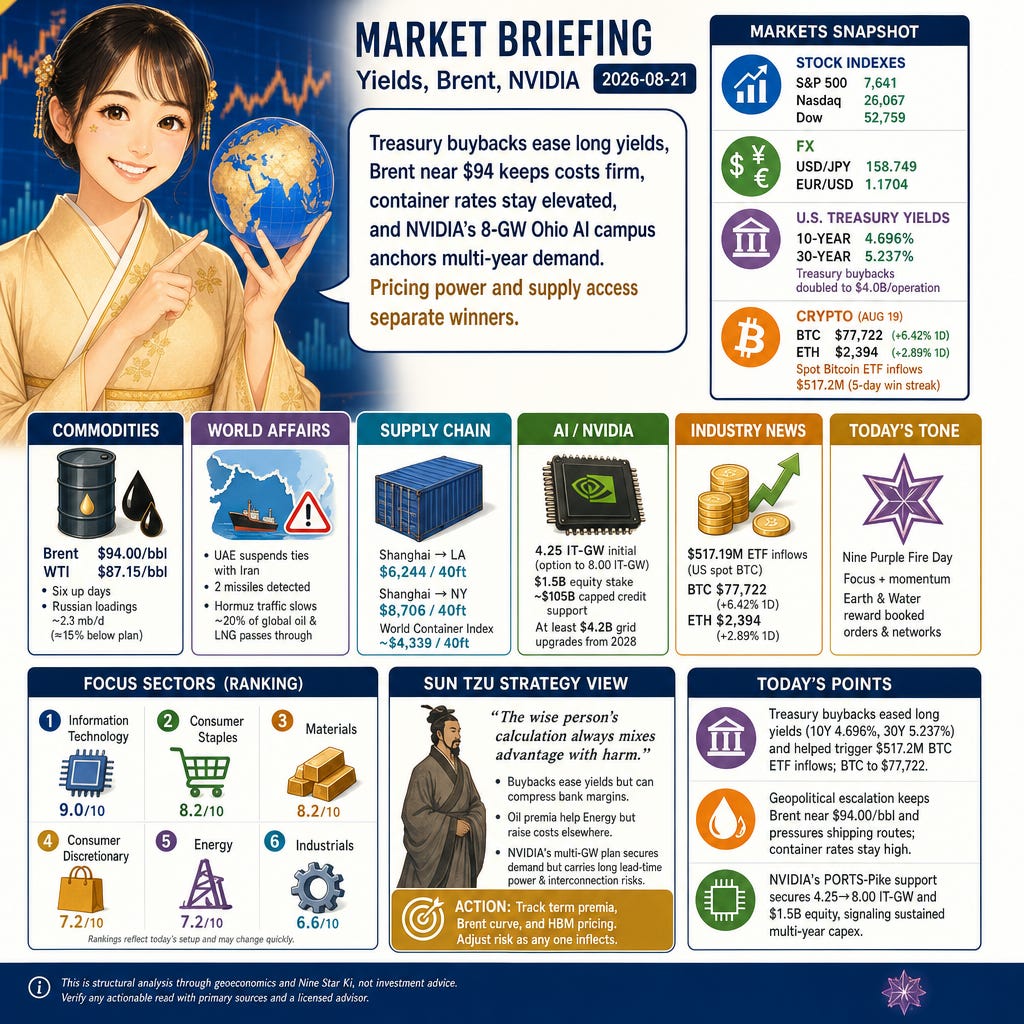
Good morning — on a Nine Purple Fire day, attention concentrates while orders flow best where backlogs and capex are real. Treasury buybacks are easing long-end pressure, Brent near $94 keeps input costs firm, and container rates remain elevated. NVIDIA’s 8‑GW Ohio AI campus anchors multi‑year compute and grid demand. Expect headline‑driven swings, with pricing power and supply access separating winners.
Stocks and FX
4.696% on the 10‑year and 5.237% on the 30‑year coincide with the Treasury doubling long‑end buybacks to $4.0B per operation from $2.0B (AP News). Equities marked higher levels with the S&P 500 at 7,641, Nasdaq 26,067 and Dow 52,759, while USD/JPY printed 158.749 and EUR/USD 1.1704. Easing term premia supports long‑duration assets (Tech, Real Estate) and loosens some FX funding strain for importers, while risk proxies recovered alongside crypto.
Commodities
$94.00/bbl Brent and $87.15/bbl WTI anchor a firm tape after six up days, with Reuters also noting Russian western‑port loadings near 2.3 mb/d (~15% below plan). Elevated crude lifts refinery margins and cascades into higher bunker surcharges, raising landed costs across Manufacturing and Retail supply chains. If Brent sustains above $90, Energy capex and hedging cadence may step up; a reversal would quickly ease cost‑push pressure into Q4.
World Affairs
2 missiles were detected by the UAE before it suspended trade and financial ties with Iran, as ship traffic through the Strait of Hormuz slowed (Reuters). Roughly one‑fifth of global oil and LNG historically pass through Hormuz, lifting geopolitical premia that keep Brent near $94 and lengthen freight times. Utilities and Industrials face tighter energy supply and potential rate adjustments as dwell times and insurance costs rise.
Supply Chain
$6,244/40ft Shanghai→Los Angeles and $8,706/40ft Shanghai→New York (Drewry) define peak‑season tightness, with the World Container Index near $4,339/40ft. Congestion and cautious transits add days to lead times, while Brent near $94 pushes bunker and carrier surcharges higher. Retailers and CPGs face longer inventory cycles and bigger working‑capital needs, and logistics providers see stronger pricing but tighter capacity planning.
AI
4.25 IT‑GW initially (option to 8.00 IT‑GW), a $1.5B equity stake, and a ~$105B capped residual‑value obligation mark NVIDIA’s backing of SB Energy’s PORTS‑Pike campus for OpenAI (GlobeNewswire). At least $4.2B of grid upgrades are planned with capacity phasing from 2028, signaling durable orders for accelerators, networking, power systems, and interconnection gear. This underwrites multi‑year data‑center capex across IT, Utilities and specialized Real Estate.
Industry News
$517.19M net inflows into U.S. spot bitcoin ETFs on Aug. 19 coincided with Bitcoin at $77,722 (+6.42% 1d) and Ether at $2,394 (+2.89% 1d) over a five‑day win streak (The Block). Rising ETF flows boost exchange custody balances and trading volumes, aiding capital‑markets and brokerage revenues, while adding volatility sensitivity to correlated growth assets and crypto‑levered businesses.
Industry Forecast
Today’s Setup
2026-08-21 is a Nine Purple Fire (Kyushi Kasei, 九紫火星) day within a Two Black Earth month and a One White Water year during Risshuu (Beginning of Autumn, from 2026-08-07). Fire concentrates narrative and capital on signal‑rich names, while Earth and Water reward firms that convert attention into booked orders on stable supply and networks; today that favors AI‑linked IT and power infrastructure as long‑end yields ease, with oil and container rates setting the cost floor for Staples, Materials and logistics‑exposed Discretionary.
Focus Sectors
Information Technology (9.0/10): AI infrastructure is the driver: NVIDIA’s support for an 8.00 IT‑GW Ohio campus for OpenAI (initial 4.25 IT‑GW, $1.5B equity, ~$105B capped credit support) hardens multi‑year demand for accelerators, networking and power gear, pulling forward data‑center capex and grid upgrades. AP News reports Treasury buybacks lifting long‑end liquidity, which eases discount‑rate drag on long‑duration tech and lowers financing friction for fabs and advanced packaging. Watch HBM/CoWoS capacity and power interconnection timelines—the chokepoints that can slip schedules if permitting or export rules tighten.
Consumer Staples (8.2/10): Freight and fuel set landed costs: Drewry shows Shanghai→LA at about $6,244/40ft and Shanghai→NY near $8,706/40ft, while Brent holds around $94/bbl (Reuters). That combination lengthens inventory cycles and tests pass‑through to shelf prices; where retailer contracts lag, gross margins compress. Defensive demand helps, but mix can weaken if households trade down to private label. Monitor grocer negotiations and promo intensity—faster pass‑through stabilizes cash conversion, slower pass‑through ties up working capital into the holiday quarter.
Materials (8.2/10): Input and freight costs are elevated: Brent near $94/bbl and tight containers (Drewry) lift energy and logistics for chemicals, metals, and building products. Reuters also flags reduced Russian western‑port loadings (~2.3 mb/d, ≈15% below plan), tightening some feedstock flows and supporting realizations where contracts are indexed. The setup favors producers with surcharge mechanisms and low spot exposure. The risk is asymmetry: a crude pullback would strip price support while inventories carry higher costs; protracted chokepoints could invert regional basis and expose contract gaps.
Consumer Discretionary (7.2/10): Shipping is the squeeze point: Shanghai→LA at ~$6,244/40ft and Shanghai→NY at ~$8,706 push delivery times and raise landed costs, while higher Brent lifts bunker surcharges. On financing, AP News notes Treasury buybacks easing long‑end liquidity, which can trim inventory‑carry and promo financing costs—a lever to support volumes. Retailers with agile sourcing and faster turns can defend gross margin; those with seasonal overhang may need heavier discounts. Watch dollar strength and tourism spend as secondary swings on FX translation into the holiday build.
Energy (7.2/10): Balances tighten as risk premia rise: Brent sits near $94/bbl with slower Hormuz traffic and the UAE suspending trade/finance with Iran; Reuters also notes Russian western‑port loadings around 2.3 mb/d (~15% below plan). Upstream cash flow benefits first, with product cracks shaping refiners’ realizations. Capital discipline and hedging choices will hinge on whether >$90 persists. The downside is a diplomatic de‑escalation or policy tools (SPR releases, price caps) that compress premia quickly, catching high‑cost barrels and unhedged refiners offside.
Industrials (6.6/10): Delivery speeds and energy costs drive conversion: elevated container rates (Shanghai→LA ~$6,244; Shanghai→NY ~$8,706) and Brent near $94/bbl lift logistics and process energy, narrowing project margins where escalation clauses lag. Offsetting, NVIDIA’s Ohio AI campus implies multi‑year orders for switchgear, transformers and transmission, with at least $4.2B of grid upgrades planned—supporting electrical OEMs and EPC pipelines. Risks include prolonged congestion that forces change‑order disputes and bid repricing if energy premia stay high, diluting book‑to‑bill even as backlogs hold.
Watchlist
Information Technology: TrendForce HBM/DRAM contract price index (monthly memory contract pricing that signals supply/demand tightness for AI components).
Consumer Staples: BLS CPI Food at Home index (monthly grocery‑price inflation that tracks pass‑through effectiveness).
Materials: S&P Global Manufacturing PMI Input Prices (monthly producer cost pressures across key Materials end‑markets).
Consumer Discretionary: U.S. Census Advance Monthly Retail Sales – Control Group (core retail demand that feeds GDP).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude inventories and refinery utilization, a read on balance tightness).
Industrials: ISM Manufacturing Supplier Deliveries Index (monthly measure of delivery speeds that drives backlog conversion).
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey – quarterly lending standards and demand across firms and households).
Communication Services: WARC Global Ad Trends (monthly benchmarks for digital and total ad spending).
Real Estate: Green Street Commercial Property Price Index (monthly U.S. private‑market commercial real‑estate pricing).
Utilities: EIA Electric Power Monthly (U.S. generation mix, retail sales and average retail electricity prices).
Health Care: BLS CPI Medical Care Services index (monthly pricing for outpatient, hospital and related medical services).
Caveats
Risshuu is mid‑season; as the month progresses, tape attention can fade while Earth’s accumulation bias strengthens, shifting which sectors capture flows. A re‑steepening in long yields or a swift Middle East de‑escalation would reset discount rates and oil/freight premia, reshuffling the rankings quickly.
Sun Tzu Strategy View
Sun Tzu wrote: —— The wise person’s calculation always mixes advantage with harm.
Treasury buybacks ease term premia and lift risk assets, but they can compress bank net interest margins and unwind quickly if issuance fears return. Oil premia support Energy cash flows while raising freight and input costs for Staples, Industrials and Materials. NVIDIA’s multi‑GW commitment secures demand yet ties capital to long lead‑time power and interconnection risks.
Action: Track term premia, the Brent curve, and HBM pricing together; adjust risk tolerance as any one inflects.
Today’s Points
Treasury action eased long yields (10Y 4.696%, 30Y 5.237%) and helped trigger $517.2M of spot Bitcoin ETF inflows, sending Bitcoin to $77,722 (5‑day win streak).
Geopolitical escalation (UAE suspending ties with Iran; 2 missiles detected) kept Brent near $94.00/bbl and pressured shipping routes, feeding higher spot container rates (Shanghai→LA ~$6,244/40ft; Shanghai→NY ~$8,706/40ft).
AI infrastructure commitments are expanding: NVIDIA’s PORTS‑Pike credit support secures an initial 4.25 IT‑GW (option to 8.00 IT‑GW) and a $1.5B equity stake, signalling sustained multi‑year capex for semiconductors and data‑centre operators.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.