Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
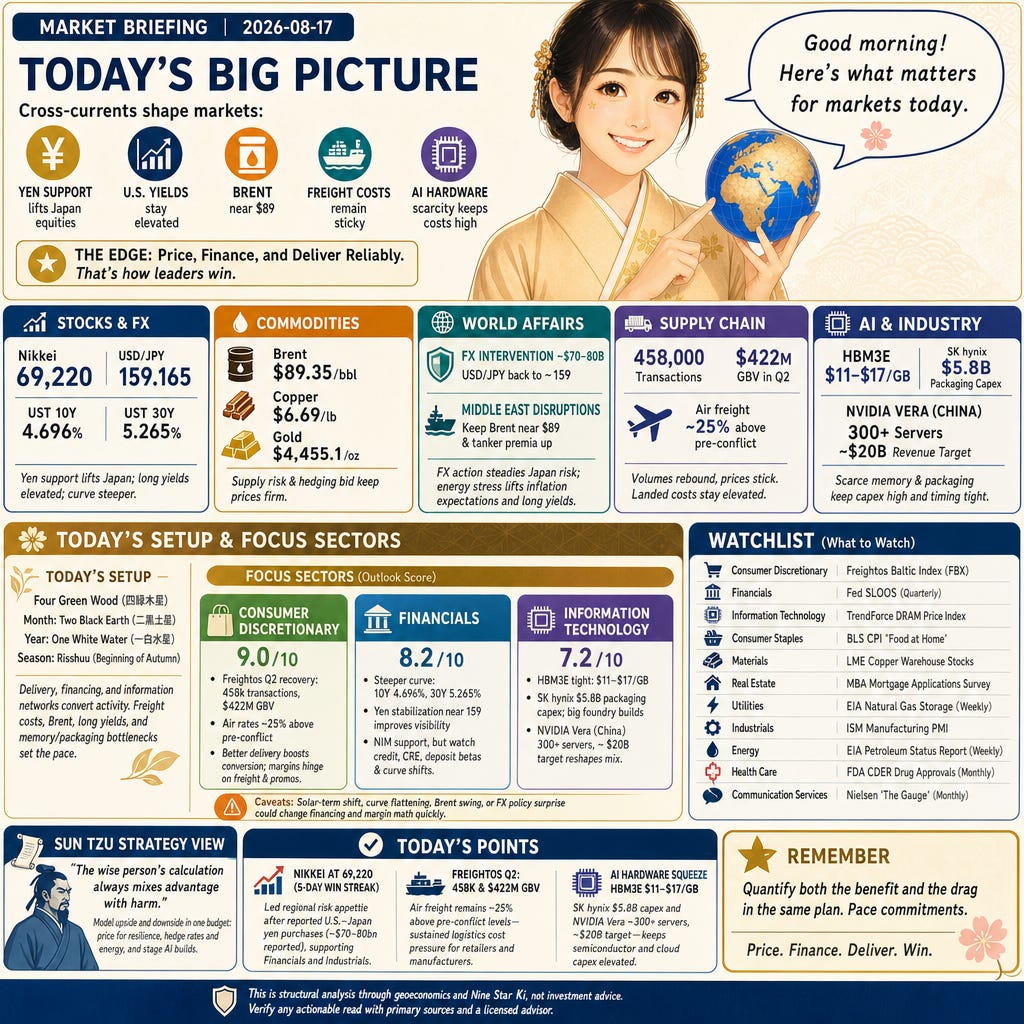
Good morning. Cross‑currents set today’s frame: Japan’s coordinated yen support lifted equities while U.S. long yields stay elevated, Brent holds near $89, and freight costs remain sticky even as volumes recover. AI hardware scarcity keeps capex and unit costs high. The sectors that can price, finance, and deliver reliably should lead.
Paywall
Stocks and FX
Nikkei 69,220 and USD/JPY 159.165 frame the tape as U.S. yields print 10Y 4.696% and 30Y 5.265% (Anadolu Agency reporting Reuters context). A firmer yen and a higher BOJ‑hike bar support Japanese cyclicals and banks, while a steeper U.S. curve lifts net interest margins but tightens financial conditions for Real Estate and Utilities via mortgage and corporate funding costs. Portfolio rebalancing across FX and duration stays the dominant transmission channel.
Commodities
Brent $89.35/bbl, copper $6.69/lb, and gold $4,455.1/oz trade firm on supply risk and bid-for-hedge dynamics (Chevron 2025 20‑F, market context). Higher oil raises transport and packaging costs and supports Energy cash flows; copper’s level signals ongoing industrial activity but squeezes Materials and electrical equipment inputs. A strong gold bid can divert capital from rate‑sensitive assets, adding cross‑asset volatility.
World Affairs
FX intervention of $70–80 billion pushed USD/JPY back toward ~159 and reset carry trades, while Middle East disruptions keep Brent near $89.35 and tanker premia elevated (Kuwait Times reporting Reuters). FX action stabilizes Japan risk (Nikkei 69,220) and forces global portfolio hedging; energy‑corridor stress feeds inflation expectations and central‑bank paths, transmitting into the long end of the U.S. curve.
Supply Chain
458,000 transactions and $422 million GBV in Q2 mark a Freightos rebound as Middle East lanes resume, with air rates still ~25% above pre‑conflict (Freightos). Recovered volumes alongside sticky prices mean landed costs stay elevated for retailers and manufacturers, extending margin management into H2. Lead‑time reliability is improving, but procurement hedges and inventory buffers remain prudent.
AI
HBM3E at ~$11–$17/GB and SK hynix’s $5.8B packaging capex, alongside foundry expansions in the tens of billions, keep AI hardware costs high and timing tight (SiliconAnalysts / SK hynix earnings context). Scarce memory and advanced packaging constrain cluster builds, pushing capex higher for cloud and device makers and supporting supplier margins. Expect continued prioritization of high‑margin configurations in allocation.
Industry News
300+ Vera CPU servers and a $20B revenue target anchor NVIDIA’s re‑entry push in China as GPU supply remains tight (IndexBox summarizing Reuters). If orders land, procurement budgets shift toward CPU‑centric builds, altering near‑term HBM and accelerator demand mix and impacting server OEM and semiconductor order books. Regional access and product‑roadmap timing become key earnings drivers.
Industry Forecast
Today’s Setup
2026-08-17 lands under Four Green Wood (Shiroku Mokusei, 四緑木星) in a month of Two Black Earth (Jikoku Dosei, 二黒土星) and a year of One White Water (Ippaku Suisei, 一白水星), within Risshuu (Beginning of Autumn). Expect information and commerce networks to convert activity where delivery and financing are dependable: freight costs and Brent shape COGS, long yields set funding math, and memory/packaging bottlenecks pace IT deployments.
Focus Sectors
Consumer Discretionary (9.0/10): Freightos shows Q2 recovery at 458k transactions and $422M GBV as lanes reopen, while air rates remain ~25% above pre‑conflict. Better delivery reliability lifts conversion in marketplaces, travel, and entertainment, but gross margins still hinge on freight and promo discipline. Watch leveraged retailers where a steeper curve raises funding costs; a negative turn in container/air spot rates or consumer credit could flip operating leverage.
Financials (8.2/10): A steeper curve with UST 10Y ~4.696% and 30Y ~5.265% supports net interest margins, and BOJ‑linked yen stabilization near 159 improves visibility for Japan banks. Intermediation and balance‑sheet pricing sit at the system’s pivot as FX hedging and duration repositioning run. Risks: rising credit costs and CRE exposures, deposit betas capping NIM, or an abrupt flattening if policy or data shift; SLOOS will guide lending‑standards read‑through.
Information Technology (7.2/10): HBM3E stays tight (ASP ~$11–$17/GB) with SK hynix adding $5.8B to packaging and big foundry builds proceeding, while NVIDIA’s Vera outreach in China (300+ servers; ~$20B target) reshapes order mix. Demand is strong, but advanced packaging and memory remain the binding constraints, elevating unit costs and deployment timing risk. Slippage in HBM/packaging yields or China program shifts could strain inventories; elevated freight adds incremental COGS pressure.
Watchlist
Consumer Discretionary: Freightos Baltic Index (FBX) global ocean container spot rates — real‑time gauge of landed cost pressure for retailers.
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey) — quarterly read on lending standards and demand across C&I, CRE, and consumer.
Information Technology: TrendForce DRAM contract price index (monthly DRAM/HBM pricing — barometer of memory tightness and supplier margin power).
Consumer Staples: BLS CPI ‘Food at Home’ (monthly U.S. grocery inflation — tests pricing power and pass‑through).
Materials: LME Copper Warehouse Stocks (daily exchange inventories — proxy for physical tightness and premia).
Real Estate: MBA Weekly Mortgage Applications Survey (30‑year mortgage rate and applications — read‑through to housing demand and financing costs).
Utilities: EIA Weekly Natural Gas Storage Report (U.S. working gas in storage — driver of power fuel costs and spark spreads).
Industrials: ISM Manufacturing PMI (New Orders and Supplier Deliveries — pace of demand and bottleneck relief).
Energy: EIA Weekly Petroleum Status Report (U.S. crude/product inventories and refinery utilization — near‑term margin and flow signal).
Health Care: FDA CDER Drug Approvals database (monthly approvals — momentum gauge for innovation‑led revenue).
Communication Services: Nielsen ‘The Gauge’ (monthly U.S. TV and streaming share — real‑time mix of linear vs. streaming attention for ad and subscription models).
Caveats
A late‑August solar‑term shift can rebalance emphasis from diffusion to cost discipline, altering which sectors convert activity. A rapid curve flattening, a sharp Brent move, or a policy surprise on FX would change financing and margin math faster than today’s setup implies.
Sun Tzu Strategy View
Sun Tzu wrote: —— The wise person’s calculation always mixes advantage with harm.
Steeper curves lift bank margins but also raise credit and refinancing risks; recovered freight volumes aid sales but keep landed costs high; AI capex builds capability while locking in higher unit economics and delay risk. The edge comes from quantifying both the benefit and the drag in the same plan and pacing commitments accordingly.
Action: Model upside and downside in one budget: price for resilience, hedge rates and energy, and stage AI builds to allocation windows.
Today’s Points
Nikkei at 69,220 (5‑day win streak) led regional risk appetite after reported U.S.–Japan yen purchases (~$70–80bn reported), supporting Financials and Industrials.
Freightos Q2: 458k transactions and $422M GBV while air freight remains ~25% above pre‑conflict levels — sustained logistics cost pressure for retailers and manufacturers.
AI hardware squeeze: HBM3E ~ $11–$17/GB and SK hynix packaging capex $5.8B, while NVIDIA’s Vera outreach targets ~300+ server orders and ~$20B revenue — keeps semiconductor and cloud capex elevated.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.