Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
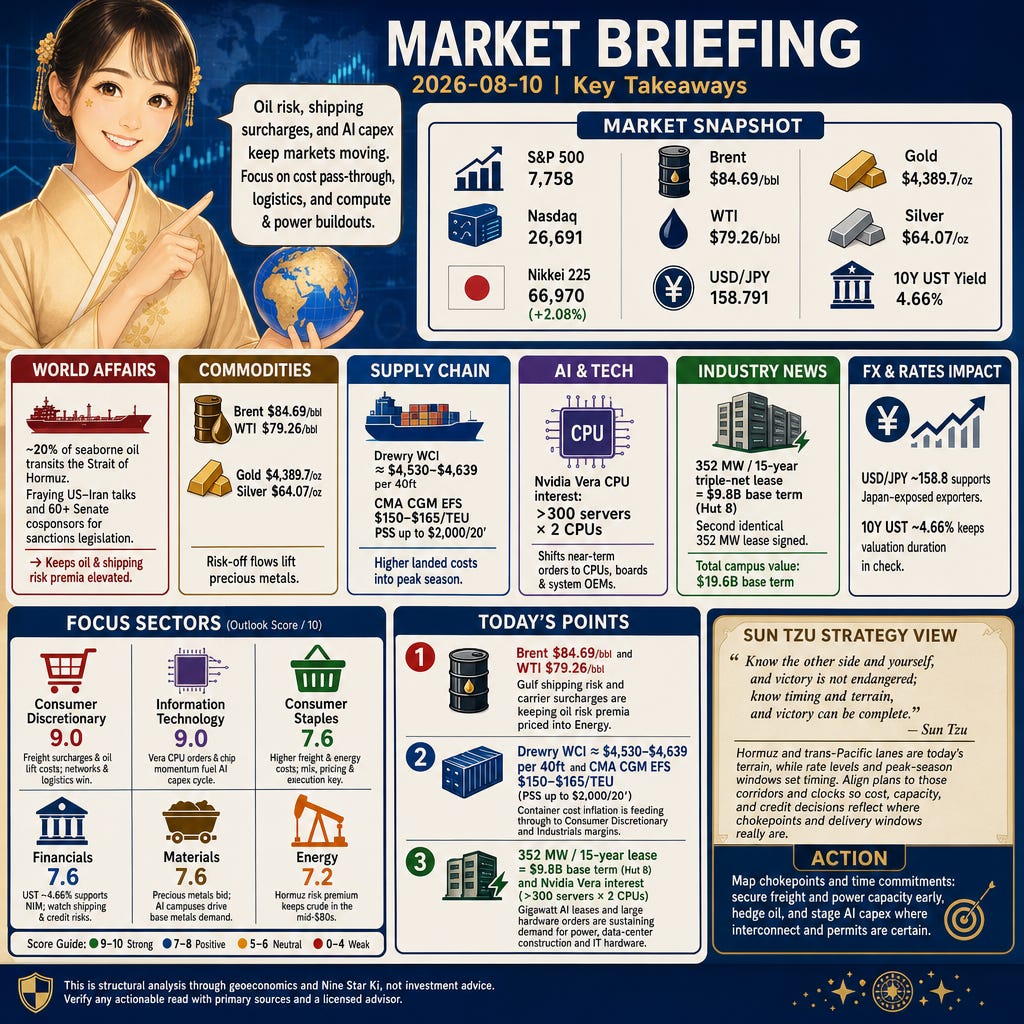
Good morning. Oil risk premia, container surcharges, and AI‑capex pipelines are driving today’s setup. Brent near $84.69 and WTI $79.26 reflect Gulf tension, while Drewry WCI around $4.5k/40ft and carrier EFS/PSS lift landed costs into peak season. At the same time, 352 MW/15‑year AI leases and Nvidia’s Vera CPU orders keep compute buildouts and power demand firm, with USD/JPY ~158.8 aiding Japan‑exposed exporters.
Paywall
Stocks and FX
S&P 500 sits at 7,758 and Nasdaq at 26,691, while Japan’s Nikkei 225 printed 66,970 (+2.08%) as USD/JPY trades near 158.791 and the 10‑year UST yield is 4.66% (Investing.com/Reuters). Reuters ties Tokyo’s move to memory/chip flows, including Kioxia sample shipments, and to yen weakness boosting exporters. The mix supports Information Technology multiples and FX translation tailwinds for consumer‑adjacent exporters, but higher long rates keep valuation duration in check.
Commodities
Brent is $84.69/bbl and WTI $79.26/bbl after renewed Gulf tensions, while gold is $4,389.7/oz and silver $64.07/oz on risk‑off flows (Reuters/Al Jazeera). Higher crude embeds a shipping and packaging cost pass‑through for Energy, Industrials and Consumer sectors, and it can firm inflation expectations into rate markets. The precious‑metals bid flags defensive positioning that typically narrows cyclicals’ risk budgets and lifts Materials exposure to bullion‑linked cash flows.
World Affairs
About 20% of seaborne oil historically transits the Strait of Hormuz, and Reuters/ThePrint and Al Jazeera report fraying US–Iran de‑escalation plus sanctions legislation with 60+ U.S. Senate cosponsors. This keeps tanker insurance and freight risk premia elevated and sustains Brent’s mid‑$80s tape. The channel runs through Energy input prices and carrier surcharges that compress margins in Industrials and Consumer categories, with spillovers to credit risk for energy‑linked borrowers.
Supply Chain
CMA CGM’s advisory sets Emergency Fuel Surcharges at $150–$165/TEU and some Peak Season Surcharges up to $2,000 per 20’, while Drewry’s WCI is ≈$4,530–$4,639 per 40ft (CMA CGM; Drewry). Higher spot and surcharges push landed costs up and pull forward inventory decisions into tighter windows. Retailers and manufacturers face leaner gross margins unless pricing and mix offset freight; lead‑time buffers and working‑capital cushions become pivotal.
AI
Reuters reports one Chinese cloud buyer preparing orders for >300 servers with 2 Vera CPUs each, with Nvidia targeting August availability. That shifts near‑term AI capex toward CPUs, boards and system OEMs while GPU supply stays constrained, supporting upstream packaging and memory demand. The power and cooling side remains tight as data‑center buildouts accelerate, shaping valuations in Information Technology and equipment‑heavy Industrials.
Industry News
Hut 8 signed a 352 MW, 15‑year, triple‑net take‑or‑pay lease worth $9.8B base term, later adding a second identical 352 MW contract, lifting campus base‑term value to $19.6B (Hut 8/PR Newswire). These long‑dated commitments lock in demand for power, networking and hardware, signaling durable revenue visibility for Real Estate (data‑center landlords) and Utilities while reinforcing multi‑year server and infrastructure order books in Information Technology and Industrials.
Industry Forecast
Today’s Setup
2026-08-10 is a Two Black Earth (Jikoku Dosei, 二黒土星) day in a Two Black Earth month, under a One White Water (Ippaku Suisei, 一白水星) year; the solar term Risshuu (Beginning of Autumn) started 2026-08-07. Expect housekeeping behaviors: tighter cost pass‑through, freight and energy sensitivity, and a premium on logistics and cash conversion, while networks and compute keep capital flowing to AI and power corridors with the 10‑year UST near 4.66%.
Focus Sectors
Consumer Discretionary (9.0/10): Spot freight at ≈$4,530–$4,639 per 40ft (Drewry WCI) and CMA CGM EFS at $150–$165/TEU raise landed costs; some lanes show PSS up to $2,000/20’. USD/JPY near 158.8 supports exporter translation and Japan‑linked flows. The operational edge is scaled commerce networks—payments and logistics that hold conversion when unit costs rise. Watch whether Brent in the mid‑$80s and carrier surcharges persist into peak season; if so, emphasize mix and cycle time to defend gross margin.
Information Technology (9.0/10): Reuters flags Nvidia’s Vera CPU push with a reported >300 servers × 2 CPUs at a major Chinese cloud, redirecting orders to CPUs, system boards and OEMs. Kioxia sample shipments and a chip‑led Nikkei 66,970 underline memory/packaging momentum and a weak‑yen tailwind. Strong AI capex should sustain demand, but CoWoS/HBM and substrate tightness can cap shipped upside even with orders in hand. Monitor export‑control pivots and FX swings for Japan/Taiwan exposure.
Consumer Staples (7.6/10): Drewry WCI near $4.5k/40ft and CMA CGM EFS at $150–$165/TEU, alongside Brent in the mid‑$80s, lift packaging, transport and energy inputs. Two Black Earth favors execution: inventory cadence, private‑label mix, and route‑to‑market efficiency to hold gross margin. Price architecture and promo discipline must track freight quickly to prevent erosion. If oil/freight stay elevated into autumn, expect tighter SKU rationalization; a softening FAO Food Price Index would ease input pressure.
Financials (7.6/10): The 10‑year UST around 4.66% supports asset yields and net‑interest margin (NIM, the spread between loan and deposit rates), while freight/oil costs risk firmer inflation expectations. Sanctions momentum (60+ Senate cosponsors) adds tail risk to energy shipping and commodity credits. Banks with granular deposit pricing and conservative transport/retail exposure screen better. Watch SLOOS for lending standards and loan demand; faster funding‑cost repricing or rising charge‑offs would compress NIM and capital flexibility.
Materials (7.6/10): Risk‑off flows lifted gold to $4,389.7/oz and silver to $64.07/oz (Reuters/Al Jazeera), supporting precious‑metals miners. On the demand side, 352 MW/15‑year AI leases ($9.8B base term each at Hut 8) point to durable copper, steel and cement needs across campus builds. Freight surcharges raise ore and product logistics costs, nudging buyers toward longer contracts. Energy spikes would squeeze smelting margins; monitor the LME Copper 3‑Month for industrial demand and pricing power.
Energy (7.2/10): Brent at $84.69/bbl and WTI at $79.26/bbl reflect a Hormuz risk premium, with ~20% of seaborne oil historically passing the strait and sanctions talk intensifying (Reuters/Al Jazeera). Upstream cash flows benefit as shipping insurance and flat price embed risk. Refining margins will oscillate with product balances and demand elasticity at higher pump prices. A rapid de‑escalation or inventory builds could compress the premium; monitor EIA weekly stocks and utilization for the near‑term signal.
Watchlist
Consumer Discretionary: Drewry World Container Index (weekly spot rates for 40ft containers across major lanes).
Information Technology: SIA/WSTS Monthly Global Semiconductor Sales (worldwide chip revenue by region and category).
Consumer Staples: FAO Food Price Index (global commodity food price basket that drives input costs).
Financials: Federal Reserve Senior Loan Officer Opinion Survey (SLOOS) on Bank Lending Practices (quarterly lending standards and loan demand).
Materials: LME Copper 3‑Month Official Price (London Metal Exchange benchmark for industrial metal demand/price).
Energy: EIA Weekly Petroleum Status Report (U.S. crude inventories, production and refinery utilization).
Real Estate: MSCI Real Assets RCA CPPI (monthly U.S. commercial property price index tracking cap‑rate and price trends).
Utilities: EIA Electric Power Monthly (U.S. electricity generation, retail sales and fuel mix by region).
Industrials: ISM Manufacturing PMI – Supplier Deliveries Index (monthly gauge of supplier lead times and delivery bottlenecks).
Communication Services: Standard Media Index (SMI) U.S. Ad Market Tracker (monthly total ad spend across channels).
Health Care: IQVIA National Prescription Audit (weekly U.S. retail prescription volumes indicating demand and access).
Caveats
A swift Gulf de‑escalation or large EIA inventory builds would fade the oil premium and soften freight surcharges faster than expected. Conversely, an export‑control shift that curtails Vera shipments or a decisive jump in the 10‑year UST toward 5% would alter the Information Technology and Financials reads.
Sun Tzu Strategy View
Sun Tzu wrote: —— Know the other side and yourself, and victory is not endangered; know timing and terrain, and victory can be complete.
Hormuz and trans‑Pacific lanes are today’s terrain, while rate levels and peak‑season windows set timing. Align plans to those corridors and clocks so cost, capacity, and credit decisions reflect where chokepoints and delivery windows really are.
Action: Map chokepoints and time commitments: secure freight and power capacity early, hedge oil, and stage AI capex where interconnect and permits are certain.
Today’s Points
Brent $84.69/bbl and WTI $79.26/bbl — Gulf shipping risk and carrier surcharges are keeping oil risk premia priced into Energy.
Drewry WCI ≈ $4,530–$4,639 per 40ft and CMA CGM EFS $150–$165/TEU (PSS up to $2,000/20’) — container cost inflation is feeding through to Consumer Discretionary and Industrials margins.
352 MW / 15‑year lease = $9.8B base‑term (Hut 8) and Nvidia‑reported Vera interest (>300 servers × 2 CPUs) — gigawatt AI leases and large hardware orders are sustaining demand for power, data‑center construction and IT hardware.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.