

Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
Good morning. Long-end U.S. yields at 5.208% on the 30-year, Brent near $90, and still-elevated container rates frame today’s setup. FX is active with EUR/USD at 1.1493 and USD/JPY near 160. AI capex remains heavy, with a $14.0bn data-center build and firmer HBM pricing tightening tech supply chains. The common threads: financing costs, energy/freight pass-through, and the conversion of AI demand into booked revenue.
Paywall
Stocks and FX
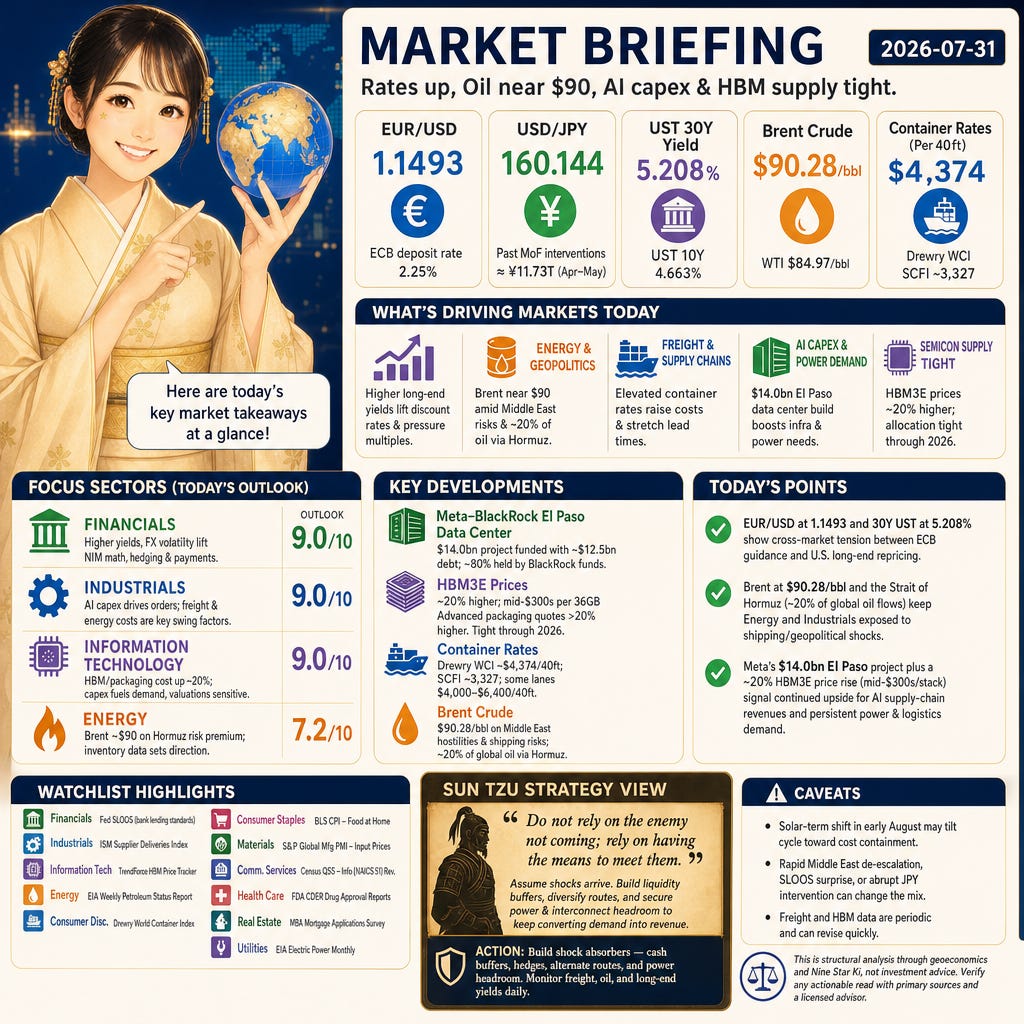
EUR/USD printed 1.1493 while USD/JPY sat at 160.144 as the ECB kept the deposit rate at 2.25% but left the door open to further moves (ECB / Lazard Asset Management). The U.S. 30-year Treasury yield at 5.208% and 10-year at 4.663% raise discount rates, pressuring equity multiples. Volatile USD/JPY, after past MoF interventions totaling about ¥11.73 trillion in April–May, lifts hedging needs and cross-border flow activity, a fee and trading tailwind for banks. The rates‑FX mix tightens financial conditions even as euro guidance reduces near-term policy uncertainty.
Commodities
Brent traded at $90.28/bbl and WTI at $84.97/bbl, supported by renewed Middle East hostilities and shipping risks (Reuters). A $90 handle pushes fuel, packaging, and freight costs higher for Industrials and Consumer sectors, while refining margins and upstream cash flow improve for Energy. Oil at these levels can lift inflation expectations and complicate rate‑cut hopes, reinforcing higher-for-longer financing costs. Watch inventory prints for confirmation of demand and the persistence of the geopolitical premium.
World Affairs
Roughly 20% of global crude/products normally transit the Strait of Hormuz, and reports of repeated U.S.–Iran strikes have kept a risk premium embedded in crude (ABC News / Reuters). Escalation forces tanker rerouting, raises insurance, and lengthens voyages — direct hits to Energy and Materials margins and working capital. The same pressures ripple into shipping-linked Industrials, where transit reliability and cost predictability drive project timing.
Supply Chain
Drewry’s WCI was about $4,374 per 40ft and the SCFI near 3,327, with some Transpacific/Asia–Europe lanes quoting $4,000–$6,400 per 40ft (BTX / Shanghai Shipping Exchange). Elevated spot rates, bunker surcharges, and insurance premia lift landed costs and extend lead times into peak season. Retailers and manufacturers face tighter gross margins and more defensive inventory planning. Logistics providers may see stronger top lines, but schedule reliability and equipment availability remain swing variables.
AI
A $14.0bn Meta–BlackRock El Paso data‑center venture, financed with about $12.5bn of debt and ~80% held by BlackRock-managed funds, underscores hyperscaler capex intensity (Reuters). The build pulls through construction, power infrastructure, and AI servers, lifting Industrials and Information Technology demand while tightening grid and interconnection capacity for Utilities. Financing scale at today’s yields raises the bar on project economics and delivery timing.
Industry News
HBM3E prices are up roughly 20% with stacks in the mid‑$300s per 36GB, and advanced‑packaging quotes are >20% higher, with allocation tight through 2026 (TrendForce / industry trackers). Rising memory and packaging costs support upstream semis and materials but raise OEM bills of materials, compressing margins where costs can’t be passed through immediately. Persistent supply tightness keeps AI server build schedules sensitive to component delivery.
Industry Forecast
Today’s Setup
2026-07-31 is a Three Blue Wood (Sanpeki Mokusei, 三碧木星) day in a Three Blue Wood month, within a One White Water (Ippaku Suisei, 一白水星) year during Shosho (Lesser Heat). Expect stronger follow‑through for projects that convert capex and demand into booked revenue via established financing and logistics channels, while higher long-end yields, energy/freight chokepoints, and FX volatility shape costs and valuation sensitivity.
Focus Sectors
Financials (9.0/10): The 30Y UST at 5.208% and ECB deposit rate at 2.25%, alongside EUR/USD 1.1493 and USD/JPY 160.144, reset NIM math and lift FX hedging and payments throughput — fee and trading income rise as cross‑border flows move. Balance‑sheet mix and funding-cost discipline are the control points in a higher‑for‑longer regime. Watch bear‑steepening for unrealized securities losses and deposit betas, and the risk that abrupt yen intervention whipsaws trading books.
Industrials (9.0/10): AI capex is visible in orders, with the $14.0bn Meta–BlackRock El Paso campus pulling through electrical gear, HVAC/cooling, and EPC backlogs. But input/logistics costs are elevated: Drewry WCI ~$4,374/40ft, SCFI ~3,327, and Brent near $90/bbl. When supplier delivery times hold, orderbooks convert to revenue with operating leverage; slippage in deliveries or chokepoint disruptions erode margins and delay recognition. Monitor delivery reliability as the key to conversion quality.
Information Technology (9.0/10): TrendForce cites ~20% HBM3E price hikes (mid‑$300s per 36GB) and >20% rises in advanced‑packaging quotes, keeping upstream memory/materials supported and BOMs higher for OEMs. Hyperscaler capex, including the $14.0bn El Paso build, sustains server demand, but the 30Y UST at 5.208% lifts discount rates and makes valuations sensitive. Bottlenecks in HBM/CoWoS, plus power and land constraints for data centers, can push deliveries right.
Energy (7.2/10): Brent at $90.28/bbl reflects a persistent Hormuz risk premium, with roughly 20% of global oil flows at stake. That supports upstream cash flows and, via refined‑product spreads, integrated earnings, but higher insurance, routing, and transit times raise delivered costs and volatility. A rapid de‑escalation or large U.S. inventory builds could compress margins; further disruption would do the opposite. Inventory data will set near‑term direction for cracks and cash generation.
Watchlist
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey — quarterly U.S. bank lending standards and loan demand).
Industrials: ISM Manufacturing PMI — Supplier Deliveries Index (monthly gauge of supplier delivery times; lower readings = faster deliveries).
Information Technology: TrendForce HBM price tracker (monthly updates on high‑bandwidth memory contract/spot pricing and supply allocation).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude/product inventories and refinery utilization).
Consumer Discretionary: Drewry World Container Index (weekly global spot container rates per 40‑ft box).
Consumer Staples: BLS CPI — Food at Home (monthly U.S. grocery price inflation across categories).
Materials: S&P Global Manufacturing PMI — Input Prices (monthly gauge of manufacturing cost pressures).
Communication Services: U.S. Census Quarterly Services Survey — Information (NAICS 51) revenue (quarterly measure of media/telecom and internet‑related service revenues).
Health Care: FDA CDER Drug Approval Reports (monthly tallies of U.S. novel drug and supplemental approvals).
Real Estate: MBA Weekly Mortgage Applications Survey (weekly U.S. mortgage application volumes by loan type).
Utilities: EIA Electric Power Monthly (U.S. electricity generation, capacity additions, and retail sales).
Caveats
A solar‑term shift in early August can reweight the cycle toward cost containment over expansion, which would temper today’s growth‑conversion bias. Rapid Middle East de‑escalation, a surprise SLOOS turn, or abrupt Japanese FX intervention would change the rates/FX/energy mix and the sector skew. Freight and HBM data are periodic and can revise quickly.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With Brent near $90, USD/JPY around 160, and HBM supply tight, the prudent stance is to assume shocks arrive and plan around them. Liquidity buffers, diversified freight routes, and power/interconnect contingencies let firms keep converting demand into revenue even when rates and chokepoints move suddenly.
Action: Build and maintain shock absorbers: cash buffers, hedges, alternate routes, and power headroom while monitoring freight, oil, and long-end yields daily.
Today’s Points
EUR/USD at 1.1493 and 30Y UST at 5.208% show cross‑market tension between ECB guidance and U.S. long‑end yield repricing (affects Financials and FX hedging).
Brent at $90.28/bbl and the Strait of Hormuz still handling ~20% of global oil flows means Energy and Industrials remain exposed to shipping/geopolitical shocks.
Meta’s $14.0bn El Paso project plus a ~20% HBM3E price rise (mid‑$300s/stack) signal continued upside for AI supply‑chain revenues (IT, Materials, Utilities) and persistent capex-driven demand for power and logistics.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.
Tiger Capital Research さん、いいねありがとうございます。読んでいただけてうれしいです。