Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
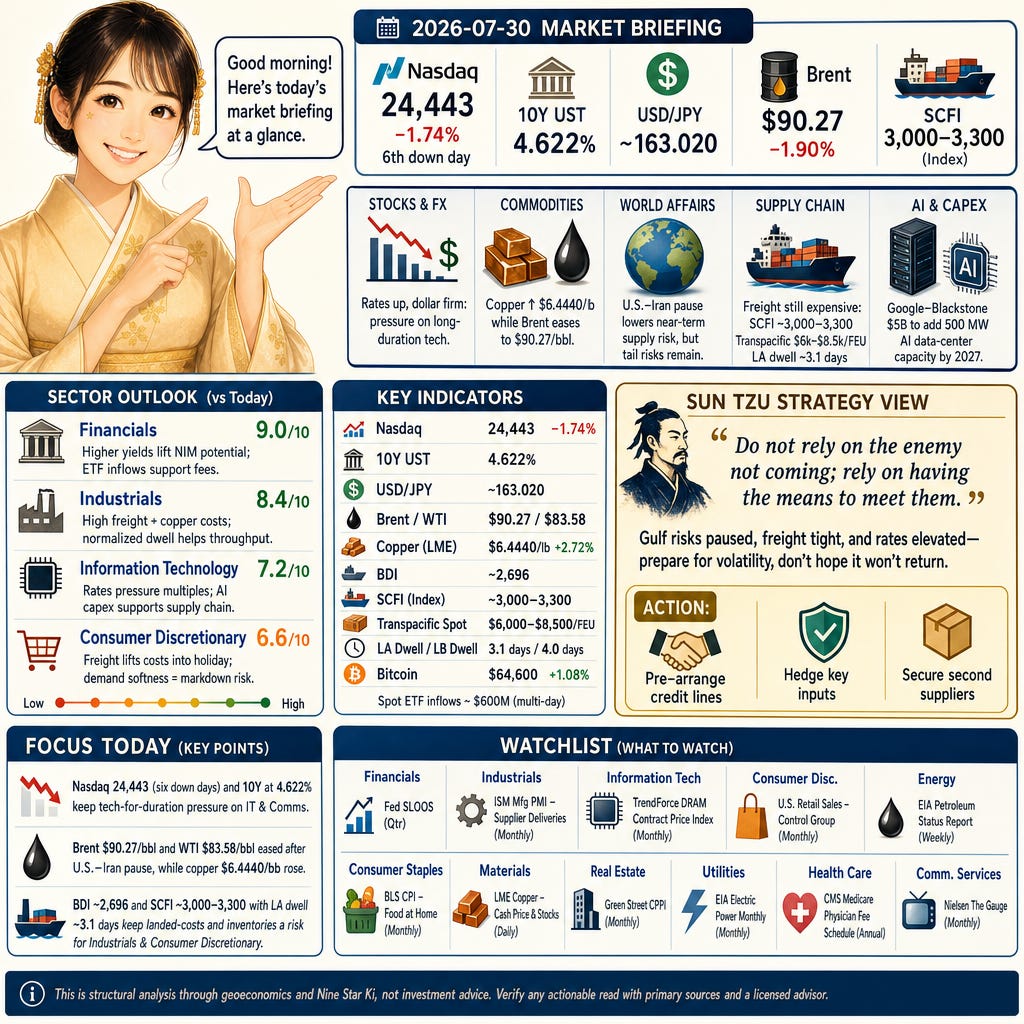
Good morning. Nasdaq 24,443 with a sixth down day, the 10Y UST at 4.622%, and USD/JPY near 163 frame a rates‑and‑dollar tape. Copper at $6.4440/lb rose as Brent eased to $90.27/bbl after the U.S.–Iran pause, splitting cost signals. Container routes stay expensive (SCFI ~3,000–3,300; transpacific $6k–$8.5k/FEU), keeping landed costs and working capital in focus while AI capex ($5B, 500 MW) extends multi‑year power and compute buildouts.
Paywall
Stocks and FX
Nasdaq 24,443 (-1.74%), S&P 7,316 (-1.52%), and Dow 51,594 (-2.19%) closed lower as the 10‑year UST hit 4.622% and the 30‑year 5.143%, with USD/JPY near 163.020, per Reuters (via MarketScreener). Higher yields raise discount rates for tech and compress duration‑heavy portfolios, while the stronger dollar pressures exporters’ reported revenue. The setup supports rotation toward cash‑flow visibility and penalizes long‑duration growth until rates break lower.
Commodities
Copper traded near $6.4440/lb (+2.72% intraday) while Brent eased to $90.27/bbl and WTI to $83.58/bbl after a diplomatic pause in Gulf attacks, per Reuters metals coverage and AP. Higher copper lifts input costs for Industrials and Materials even as miners benefit; oil near $90 still supports Energy cashflows but trims immediate risk premium. Manufacturers face tighter bill‑of‑materials math and selective pass‑through to protect margins.
World Affairs
Brent pulling toward $90.27/bbl from earlier prints near $92.02 followed reports of a U.S.–Iran pause in Gulf attacks, AP notes. The détente lowers the probability of acute shipping disruptions and near‑term insurance spikes, but tail risks remain elevated. Pricing feeds through freight and fuel surcharges, modulating cost pressure across Industrials and Materials.
Supply Chain
The Baltic Dry Index held around ~2,696 while container routes stayed tight: SCFI ~3,000–3,300 and transpacific 40‑ft spot quotes near $6,000–$8,500/FEU in July, with LA on‑dock dwell ~3.1 days and Long Beach ~4.0, per Hapag‑Lloyd and BDI data. Elevated container rates raise landed costs and stretch working capital for Industrials, Consumer Discretionary, and Staples into peak season. Lead‑time reliability improves, but pricing power sits with carriers.
AI
A $5.0B equity commitment targeting 500 MW of new AI data‑centre capacity by 2027 from Google and Blackstone, reported by Bloomberg/Reuters, reinforces multi‑year compute and power capex. With Big Tech AI infrastructure spend estimated above $700B in 2026, suppliers tied to chips, memory, advanced packaging, and grid interconnects see durable demand, while Utilities face larger PPAs and grid upgrades. Margin pressure persists for third‑party GPU providers amid rising TPU competition.
Industry News
Bitcoin at $64,600 (+1.08%) followed several days of U.S. spot‑ETF inflows (~$600M multi‑day; peaks near $1.3B in strong weeks), per CoinDesk and Forbes. The flows lift asset‑management fees and crypto‑infrastructure activity, while highlighting liquidity rotation between crypto and high‑beta tech. Volatility in these channels can tighten or loosen risk budgets for Financials and IT on short notice.
Industry Forecast
Today’s Setup
2026-07-30 sits under Day‑star Four Green Wood (Shiroku Mokusei, 四緑木星) in the Center (Chūkyū, 中宮), with month‑star Three Blue Wood (Sanpeki Mokusei, 三碧木星) and year‑star One White Water (Ippaku Suisei, 一白水星) during Shosho (Lesser Heat). Expect fast signal diffusion but higher coordination costs: rising yields and an expensive container market reward operators that convert orders to cash quickly, manage financing costs, and keep inventories light.
Focus Sectors
Financials (9.0/10): 10Y UST at 4.622% and USD/JPY 163.020 lift discount rates and volatility across bank books, but can widen net interest margin (NIM, the spread between loan yields and deposit costs) if deposit betas stay contained. Nasdaq 24,443 and softer issuance curb capital‑markets fees, while spot Bitcoin ETF inflows (~$600M over several days) support asset‑management lines. Watch available‑for‑sale marks and CRE refinancing as higher coupons reprice risk. Earnings leverage favors shorter asset duration and disciplined funding; key risk is deposit costs outrunning loan repricing.
Industrials (8.4/10): SCFI ~3,000–3,300 and transpacific spot $6k–$8.5k/FEU keep container freight elevated into peak season, while the Baltic Dry Index ~2,696 signals steady bulk lift. Copper at $6.4440/lb raises bills of materials for machinery and electrical kit, but normalized port dwell (LA ~3.1 days; Long Beach ~4.0) helps throughput and revenue recognition. Operators that sequence production and routing best can protect margin; those reliant on long ocean legs face stretched working capital. Risk: demand softens before rates ease, stalling backlog burn.
Information Technology (7.2/10): A six‑day Nasdaq slide at 24,443 with the 10Y at 4.622% pressures rate‑sensitive multiples, especially semis and AI supply‑chain names. Offsetting, Google–Blackstone’s $5B plan to add 500 MW of TPU‑focused data centers reinforces multi‑year compute and power capex. A stronger dollar trims reported revenue for exporters; chokepoints in HBM and advanced packaging keep dispersion high. Near term, discount‑rate shocks dominate; mid term, capex visibility supports providers tied to memory, packaging, and power.
Consumer Discretionary (6.6/10): Import‑reliant retailers face SCFI‑linked costs as transpacific $6k–$8.5k/FEU lifts landed COGS and inventory carrying costs into holiday builds. Brent at $90.27 eased after the U.S.–Iran pause, trimming fuel expense, but not enough to offset freight tightness; a firm dollar also raises import bills. Platforms that convert traffic with lower promotion burn should defend margin. Risk: if demand wobbles, markdowns escalate to clear stock, compounding freight‑era gross‑margin pressure.
Watchlist
Financials: Fed SLOOS (Senior Loan Officer Opinion Survey, Federal Reserve — quarterly lending standards and loan demand across commercial & industrial and consumer credit).
Industrials: ISM Manufacturing PMI — Supplier Deliveries (Institute for Supply Management — monthly gauge of delivery times, a proxy for supply‑chain tightness).
Information Technology: TrendForce DRAM Contract Price Index (TrendForce — monthly benchmark for DRAM pricing tied to AI/server demand).
Consumer Discretionary: U.S. Census Monthly Retail Sales — Control Group (U.S. Census Bureau — retail core that feeds GDP, a clean read on discretionary spending).
Energy: EIA Weekly Petroleum Status Report (U.S. Energy Information Administration — weekly U.S. crude/product inventories and refinery utilization).
Consumer Staples: BLS CPI — Food at Home (Bureau of Labor Statistics — monthly grocery‑category prices that drive COGS and shelf pricing).
Materials: LME Copper — Cash Price and Warehouse Stocks (London Metal Exchange — daily cash price and inventories indicating copper supply/demand tightness).
Real Estate: Green Street Commercial Property Price Index (Green Street — monthly U.S. commercial‑property pricing across sectors, a read on cap‑rate/valuation moves).
Utilities: EIA Electric Power Monthly (U.S. Energy Information Administration — generation mix, retail sales, and average revenue per kWh).
Health Care: CMS Medicare Physician Fee Schedule (Centers for Medicare & Medicaid Services — annual proposed/final rule setting reimbursement rates for physician services).
Communication Services: Nielsen The Gauge (Nielsen — monthly U.S. TV/streaming viewing share indicating ad‑supported versus subscription shifts).
Caveats
If the solar‑term window shifts or data revisions hit — especially yields, FX, copper, or container spot quotes — the balance between rate sensitivity and cost pressure will change. Conflicting signals between Five‑Element reads and near‑term macro prints can raise noise; rely on the watch indicators to confirm trend direction.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With Gulf risks merely paused, freight still tight, and rates elevated, planning for renewed shocks beats hoping they don’t arrive. Build cushions in liquidity, fuel and freight hedges, and alternate routing so operations continue if volatility returns.
Action: Favor readiness: pre‑arrange credit lines, hedge key inputs, and secure secondary suppliers now.
Today’s Points
Nasdaq at 24,443 (six consecutive down days) and 10Y UST at 4.622% point to continued tech‑for‑duration pressure on Information Technology and Communication Services.
Brent $90.27/bbl and WTI $83.58/bbl eased after a reported U.S.–Iran pause, while copper at $6.4440/lb rose — Energy and Materials face divergent margin implications.
Supply chain frictions persist: BDI ~2,696 and SCFI readings near 3,000–3,300 plus LA dwell ~3.1 days keep landed‑costs and inventories a near‑term risk for Industrials and Consumer Discretionary.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.