Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
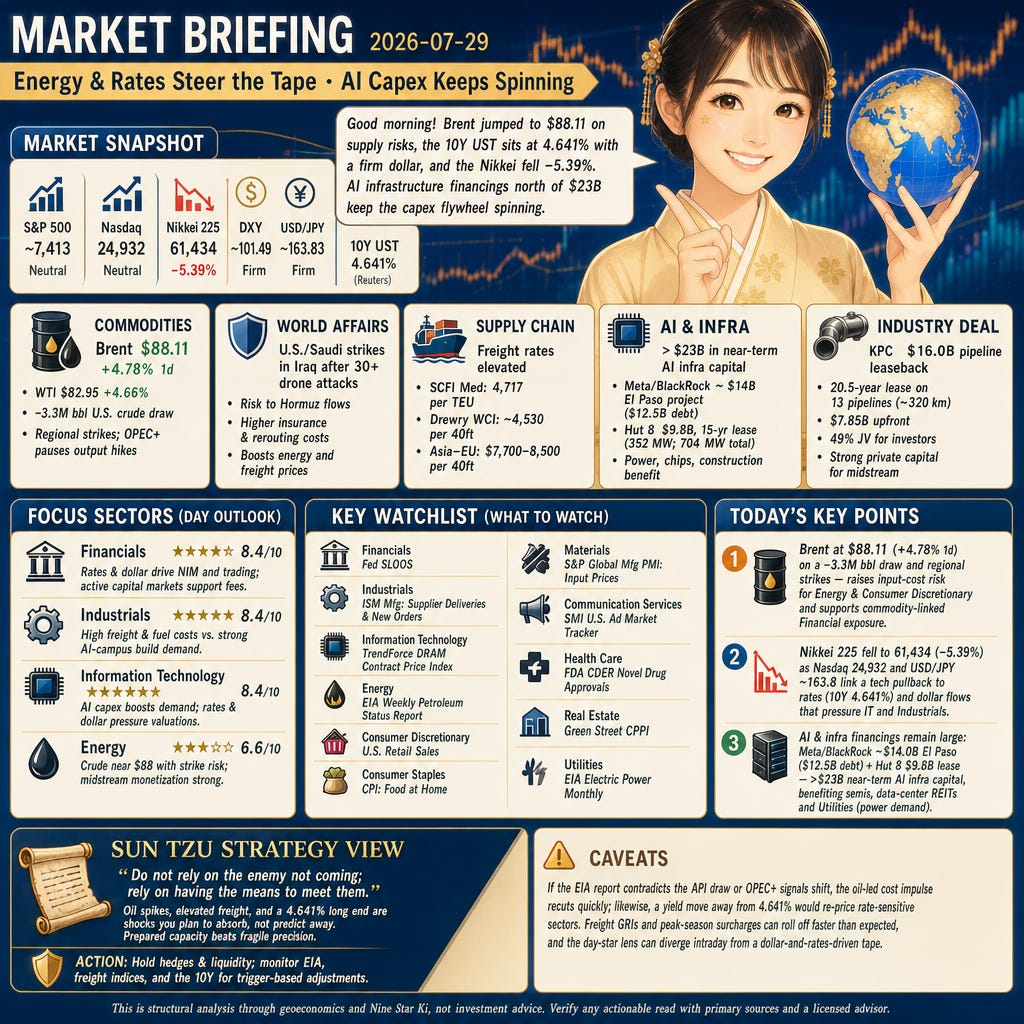
Good morning — energy prices and funding costs are doing the steering. Brent at 88.11 and WTI at 82.95 feed an inflation premium just as the 10Y UST sits at 4.641% with the dollar firm. A tech-led Nikkei drop (−5.39%) tightens global risk and FX translation for exporters. Meanwhile, AI infrastructure financings north of $23B keep the capex flywheel spinning for chips, power, and construction.
Paywall
Stocks and FX
Dollar index near 101.49 and USD/JPY around 163.83 anchored the FX tape, while the 10Y UST yield printed 4.641% (Reuters). Equities were mixed: S&P 500 ~7,413 and Nasdaq 24,932 as Japan’s Nikkei 225 slid to 61,434 (−5.39%). A firm dollar and higher long-end yields compress rate-sensitive multiples and raise FX translation risk for global tech exporters. For Financials, the curve and dollar path keep net interest margin and trading value-at-risk tightly coupled to rates.
Commodities
Brent jumped 4.78% to 88.11/bbl and WTI rose 4.66% to 82.95/bbl after a reported 3.3M bbl U.S. crude draw and renewed regional strikes (Reuters). Traders also cited OPEC+ signaling a pause to output increases. Higher crude lifts transport and petrochemical input costs, adds CPI risk, and can push rate expectations higher. That raises operating costs for Industrials and consumer sectors while pressuring valuation multiples.
World Affairs
U.S. and Saudi forces conducted precision strikes in Iraq following a wave of more than 30 drone attacks, coinciding with Brent at 88.11 and constrained Hormuz flows (Reuters/AP). The channel is direct: higher war-risk insurance, rerouting, and potential supply disruption lift energy prices and freight costs. That pressure passes through Energy and Industrials and can widen credit spreads via commodity-led inflation.
Supply Chain
SCFI Mediterranean rates printed 4,717 per TEU and the Drewry WCI hovered near 4,530 per 40ft, with Asia–EU quotes showing 7,700–8,500 per 40ft as carriers hold GRIs and peak-season surcharges (Great Hensen/Drewry). Elevated spot rates raise landed costs and working-capital needs into inventory replenishment. Importers and logistics providers face tighter margins and longer cash-conversion cycles.
AI
Meta and BlackRock outlined a roughly 14.0B dollar El Paso data-center venture, with BlackRock financing about 12.5B in debt; Hut 8 signed a 9.8B, 15-year lease for 352 MW, doubling tenant capacity to 704 MW at a 1 GW campus (Meta PR; Reuters). The AI capex cycle supports semiconductors, advanced packaging, power systems, and construction. It also tightens regional power availability and grid interconnect queues for Utilities and data-center Real Estate.
Industry News
Kuwait Petroleum agreed a 16.0B dollar, 20.5-year lease-and-leaseback covering 13 pipelines (~320 km) with a Blackstone/Brookfield/KKR consortium, yielding 7.85B dollars upfront and a 49% JV stake for investors (Reuters). The deal underscores robust private capital appetite for midstream assets with tariff-backed cash flows. It reallocates funding toward pipelines and away from sovereign balance sheets, with implications for Energy, Financials, and Industrials project pipelines.
Industry Forecast
Today’s Setup
On 2026-07-29, a Five Yellow Earth (Goou Dosei, 五黄土星) day sits within a Three Blue Wood (Sanpeki Mokusei, 三碧木星) month and a One White Water (Ippaku Suisei, 一白水星) year. Expect a center-led tape where pricing power and access are set by policy desks and market operators. Oil, the yield curve, and grid capacity are the chokepoints to watch, shaping costs, financing, and delivery timelines across sectors.
Focus Sectors
Financials (8.4/10): 10Y UST at 4.641% and a firm dollar (Reuters) keep net interest margin and trading books tethered to rates, while live capital markets—Meta/BlackRock’s ~14B data-center financing and KPC’s 16B pipeline leaseback—support underwriting, syndication, and fees. Higher Brent near 88 and the Nikkei’s −5.39% drop tighten cross-asset VaR and raise spread risk via commodity-led inflation. Watch deposit beta and CRE refinancing as yields persist. Key swing: whether loan demand and standards in SLOOS confirm a durable credit cycle.
Industrials (8.4/10): Freight is the margin gate: SCFI Mediterranean at 4,717 per TEU and Drewry WCI ~4,530 per 40ft (Great Hensen/Drewry) keep logistics costs elevated, and Brent’s jump raises fuel and transport inputs (Reuters). Offsetting, AI-campus builds keep equipment orders and construction backlogs firm. Routing around Hormuz and episodic war-risk insurance can spike shipping costs. Monitor ISM Manufacturing—Supplier Deliveries and New Orders—for lead times and demand momentum.
Information Technology (8.4/10): The capex engine is on: Meta/BlackRock’s ~14B El Paso campus and Hut 8’s 9.8B lease extend multi-year demand for semis, advanced packaging, and power-dense gear (Meta PR; Reuters). Offsetting, a stronger dollar and 10Y at 4.641% compress valuation multiples, while a tech-led Nikkei drawdown signals fragility in risk appetite. Bottlenecks in HBM and advanced-node packaging remain. Track TrendForce DRAM contract prices for tightness tied to AI/server demand.
Energy (6.6/10): A reported −3.3M bbl U.S. crude draw with Brent ~88.11 and WTI ~82.95 (Reuters) plus renewed U.S./Saudi strikes lift the risk premium and refined-product spreads. Private capital’s 16B move into Kuwait’s pipelines highlights a focus on tariff-backed cash flows and midstream monetization. A swift OPEC+ pivot or de-escalation could compress spreads; escalation around Hormuz would raise war-risk insurance and rerouting costs. Watch the EIA Weekly Petroleum Status for confirmation of draws and utilization shifts.
Watchlist
Financials: Federal Reserve Senior Loan Officer Opinion Survey (SLOOS) — quarterly U.S. bank lending standards and loan demand.
Industrials: ISM Manufacturing PMI — Supplier Deliveries and New Orders (monthly U.S. factory lead times and demand).
Information Technology: TrendForce DRAM contract price index (monthly memory pricing; a proxy for AI/server demand and supply tightness).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude inventories, refinery utilization and product stocks).
Consumer Discretionary: U.S. Census Advance Monthly Retail Sales (monthly spending levels in discretionary categories).
Consumer Staples: BLS CPI: Food at home (monthly U.S. grocery inflation, a proxy for cost pass-through capacity).
Materials: S&P Global Manufacturing PMI — Input Prices (monthly survey of factories’ input-cost inflation).
Communication Services: Standard Media Index (SMI) U.S. Ad Market Tracker — monthly measured ad spend across major media channels.
Health Care: FDA CDER Novel Drug Approvals — monthly count and detail of new molecular entity approvals.
Real Estate: Green Street Commercial Property Price Index (CPPI) — monthly U.S. commercial real-estate pricing trends.
Utilities: EIA Electric Power Monthly — U.S. electricity sales, generation mix and load growth by region.
Caveats
If the EIA report contradicts the API draw or OPEC+ signals shift, the oil-led cost impulse recuts quickly; likewise, a yield move away from 4.641% would re-price rate-sensitive sectors. Freight GRIs and peak-season surcharges can roll off faster than expected, and the day-star lens can diverge intraday from a dollar-and-rates-driven tape.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Oil spikes, elevated freight, and a 4.641% long end are shocks you plan to absorb, not predict away. Build room in budgets and timelines for price swings and interconnect delays while keeping liquidity accessible. Prepared capacity beats fragile precision when chokepoints move.
Action: Hold durable hedges and liquidity buffers; monitor EIA, freight indices, and the 10Y for trigger-based adjustments.
Today’s Points
Brent at $88.11 ( +4.78% 1d) on a reported -3.3M bbl U.S. crude draw and regional strikes — raises input-cost risk for Energy and Consumer Discretionary and supports commodity-linked Financial exposure.
Nikkei 225 fell to 61,434 (–5.39%) alongside Nasdaq 24,932 and USD/JPY ~163.8, linking a tech-sector pullback to currency/interest-rate flows (10Y UST 4.641%) that pressure Information Technology and Industrials.
AI and infra financings remain large-scale: Meta/BlackRock’s ~$14.0B El Paso project (with $12.5B debt) plus Hut 8’s $9.8B lease show >$23B in near-term AI infra capital, benefiting semiconductors, data‑center REITs and Utilities (power demand).
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.