

Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
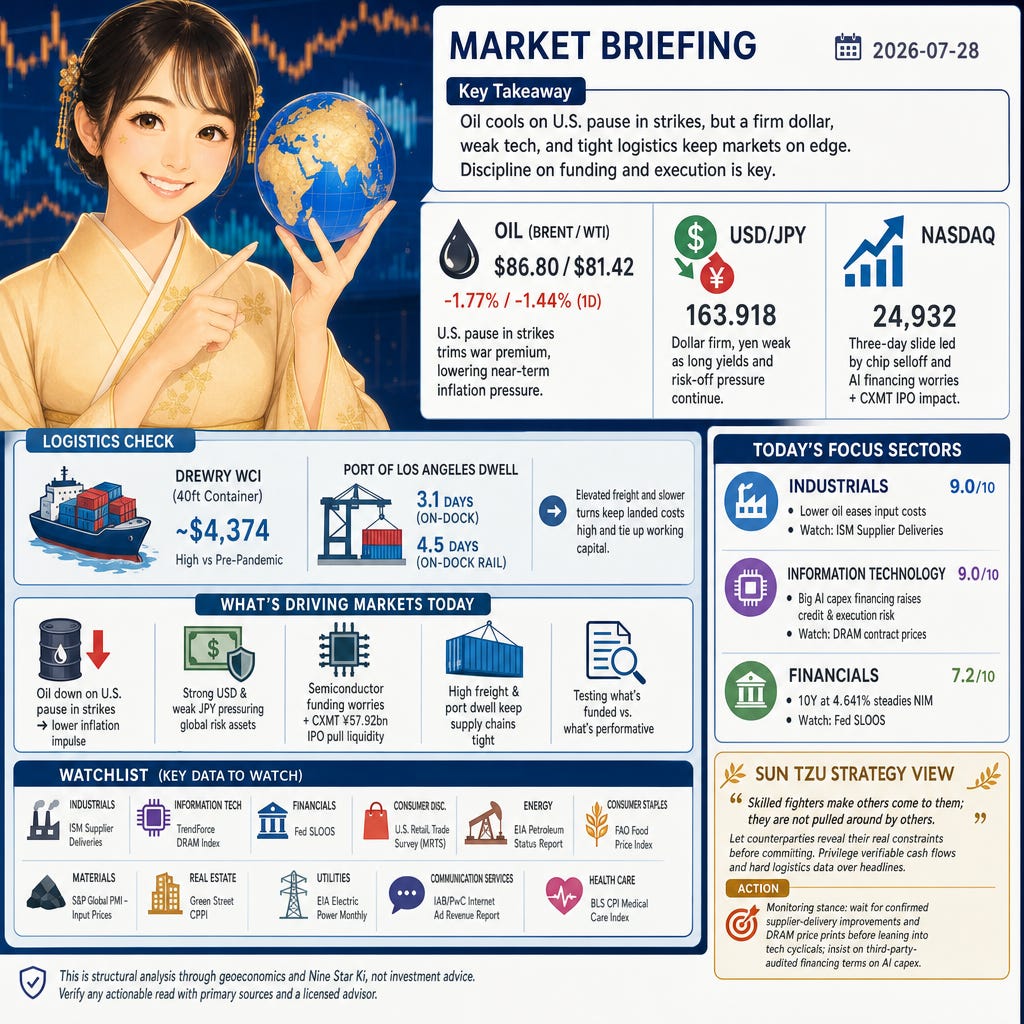
Good morning — tech is leading risk-off as semiconductor funding headlines hit valuations while the dollar stays firm and the yen sinks. Brent at $86.80 and WTI at $81.42 ease the near‑term inflation pulse, but freight and port dwell keep goods costs sticky. The market is testing what’s funded versus what’s performative: AI megaproject guarantees, container rates, and the 10Y UST at 4.641% are today’s anchors.
Paywall
Stocks and FX
Nasdaq at 24,932 after a three‑day slide and USD/JPY at 163.918 with the 10Y UST at 4.641% frame a dollar‑firm, tech‑weak tape (Reuters; yfinance snapshots). A chip‑led selloff tied to AI financing worries and CXMT’s liquidity‑draining debut tightens global tech risk premia. A stronger dollar compresses translated earnings for Japan exporters and raises local funding costs, while higher long yields pressure growth‑stock valuations and add VaR to Financials’ tech‑exposed books.
Commodities
Brent at $86.80/bbl (−1.77% 1d) and WTI at $81.42/bbl (−1.44% 1d) eased after Washington paused strikes on Iran (Reuters; Market Snapshot). Lower crude trims near‑term input‑cost pressure for transport, packaging, and petrochemicals, softening the inflation impulse ahead of central‑bank meetings. Energy margins stabilize if prices hold, but any Hormuz disruption can quickly reprice fuel and freight lines.
World Affairs
After roughly 13 nights of strikes, a U.S. pause and a reported 60‑day diplomacy window left Brent at $86.80, WTI at $81.42, and the 10Y UST near 4.641% (Reuters). A sustained lull reduces war‑risk premiums in oil and shipping insurance, easing commodity‑driven inflation expectations. That softens the case for tighter policy and temporarily relieves margin pressure for goods producers dependent on diesel and marine fuel.
Supply Chain
Drewry’s WCI near $4,374 per 40ft and Port of Los Angeles dwell at 3.1 days (on‑dock rail 4.5 days) show peak‑season costs still elevated even as weekly gains cool (Informare; Hillebrand). Elevated freight and slower turns lift landed costs and tie up working capital, delaying margin relief for Consumer Discretionary and Industrials. If dwell and blank sailings normalize into Q3, unit costs can step down and shorten lead times.
AI
A reported $250bn vendor guarantee for OpenAI’s Ohio campus and up to $350bn of chip financing (WSJ) recast AI capex as supplier‑backed credit rather than arms‑length sales. That raises circular‑financing risk and shifts credit exposure onto chip and platform vendors, widening discount rates for long‑dated tech cash flows. Memory competition also tightens, pressuring DRAM pricing and margins.
Industry News
CXMT raised ¥57.92bn ($8.6bn) in Shanghai, with shares opening at ¥49.50 versus ¥8.66 and implying roughly ¥3.3tn ($487bn) at the intraday peak — a near 470% surge (Reuters). The blockbuster listing concentrated flows in China memory names and intensified DRAM competition, pressuring global memory pricing and upstream materials suppliers. Liquidity crowd‑out hit other tech listings and added to chip volatility.
Industry Forecast
Today’s Setup
2026-07-28 is a Six White Metal (Roppaku Kinsei, 六白金星) day within a Three Blue Wood month and One White Water year during Shosho (Lesser Heat). Execution and funding discipline matter: oil’s retreat trims input costs, but elevated freight and port dwell keep inventory turns slow, while AI megaproject financing pushes balance‑sheet risk and due‑diligence thresholds to the foreground.
Focus Sectors
Industrials (9.0/10): WCI at ~$4,374/40ft and Brent/WTI at $86.80/$81.42 lower input‑cost volatility, improving order‑to‑delivery conversion. As supplier delivery times stabilize, operating leverage — more sales drop to profit when fixed costs don’t grow — improves and backlogs convert to revenue. Risks: Port of LA dwell remains 3.1 days (on‑dock rail 4.5) and any Hormuz flare‑up can re‑inflate fuel and freight. Watch ISM Supplier Deliveries for sustained acceleration and confirm easing accessorials in carrier contracts.
Information Technology (9.0/10): WSJ flags roughly $250bn in guarantees (and up to $350bn in chip financing) tied to OpenAI’s 10‑GW build, pulling vendor credit onto balance sheets. Add CXMT’s ¥57.92bn IPO and memory competition, and funding scrutiny widens discount rates for long‑duration cash flows, especially with the 10Y at 4.641% and a firm dollar. Upside still rests on secular compute demand; the near‑term hinge is financing quality, not headlines. Watch DRAM contract prices and any move from guarantees to take‑or‑pay obligations.
Financials (7.2/10): With the 10Y UST at 4.641%, NIM (net interest margin — the spread banks earn between loans and deposits) assumptions steady, while a chip selloff and AI supplier guarantees raise counterparty and collateral oversight. VaR (modelled loss limits) can spike in tech‑exposed books as equity volatility rises and USD/JPY at 163.918 jars FX hedges. The opportunity is disciplined underwriting; the risk is contingent vendor‑finance creeping onto loan books. Watch the Fed’s SLOOS for standards and demand across C&I and CRE.
Watchlist
Industrials: ISM Manufacturing PMI – Supplier Deliveries (Institute for Supply Management; monthly supplier delivery times — lower readings mean faster deliveries).
Information Technology: TrendForce DRAM contract price index (monthly benchmark for DRAM contract pricing and supply–demand balance).
Financials: Federal Reserve Senior Loan Officer Opinion Survey (SLOOS — quarterly U.S. bank lending standards and loan demand).
Consumer Discretionary: U.S. Census Monthly Retail Trade Survey (MRTS — monthly retail sales by category, a read on discretionary demand).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude inventories, product stocks, and refinery utilization).
Consumer Staples: FAO Food Price Index (Food and Agriculture Organization — monthly global food commodity price benchmark).
Materials: S&P Global Manufacturing PMI – Input Prices (monthly gauge of manufacturers’ input‑cost inflation).
Real Estate: Green Street Commercial Property Price Index (monthly U.S. commercial property price changes).
Utilities: EIA Electric Power Monthly (U.S. generation mix, retail rates, and utility fuel costs).
Communication Services: IAB/PwC Internet Advertising Revenue Report (semiannual benchmark of U.S. digital ad spending and mix).
Health Care: BLS CPI Medical Care index (monthly U.S. inflation gauge for medical care services and commodities).
Caveats
The Shosho (Lesser Heat) window can flip quickly if diplomacy in the Gulf breaks down or accelerates, re‑pricing oil, shipping insurance, and term premia. AI financing headlines are evolving; confirmation, sizing, and counterparty terms could materially change balance‑sheet exposure and sector dispersion.
Sun Tzu Strategy View
Sun Tzu wrote: —— Skilled fighters make others come to them; they are not pulled around by others.
Let counterparties reveal their real constraints — financing capacity, delivery speed, and willingness to price risk — before committing. In today’s tape, that means privileging verifiable cash flows and hard logistics data over headline scale or projected demand.
Action: Monitoring stance: wait for confirmed supplier‑delivery improvements and DRAM price prints before leaning into tech cyclicals; insist on third‑party‑audited financing terms on AI capex.
Today’s Points
Brent at $86.80 and WTI at $81.42 fell as a U.S. pause in strikes trimmed the war premium, lowering near‑term inflation pressure ahead of this week’s Fed decision (10Y UST 4.641%).
Dollar strength and a weak yen (USD/JPY 163.918) coincide with a tech rout (Nasdaq 24,932) driven by semiconductor funding worries and CXMT’s ¥57.92bn ($8.6bn) IPO that pulled liquidity into China memory stocks.
Logistics remain a bottleneck: Drewry WCI near $4,374 per 40ft and Port of Los Angeles dwell at 3.1 days keep landed costs and inventory lead times elevated for Consumer Discretionary and Industrials.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.
@tigercapitalresearch さん、いいねありがとうございます。読んでいただけてうれしいです。