Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
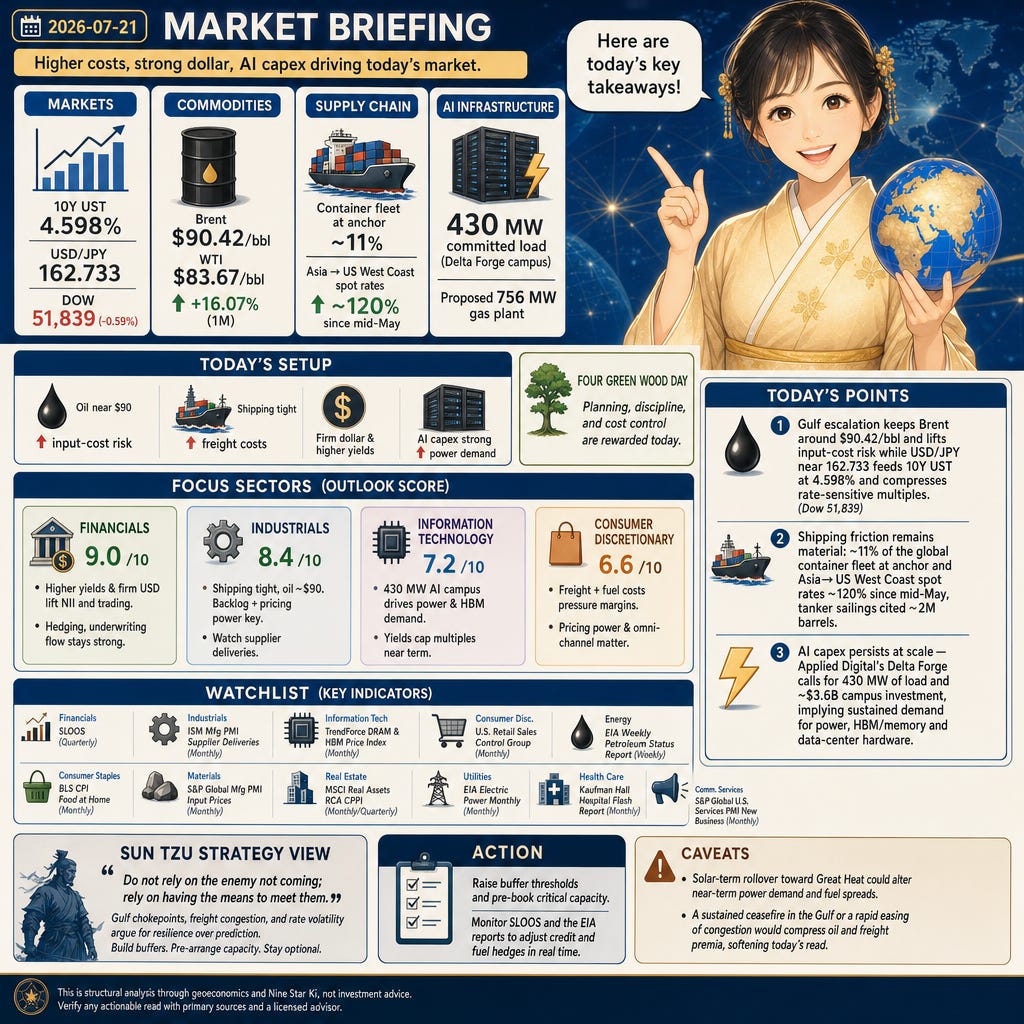
Good morning. Brent near $90.42/bbl, USD/JPY around 162.733, and the 10-year UST at 4.598% frame a higher-cost, stronger-dollar tape. Container congestion persists even as tanker routes face new Gulf risks, keeping delivered costs elevated. Meanwhile, AI infrastructure capex remains large with a 430 MW campus commitment, sustaining power and data-center demand. This setup favors balance-sheet strength in Financials and execution discipline in Industrials, with selective support for IT tied to data centers.
Paywall
Stocks and FX
4.598% on the 10-year U.S. Treasury and USD/JPY at 162.733 anchored a firmer dollar as the Dow closed 51,839 (-0.59%), Reuters reports. EUR/USD traded near 1.1426 while safe-haven flows oscillated with ceasefire headlines. Higher yields raise financing costs and compress valuation multiples for rate-sensitive equities, while FX and rates volatility supports trading and hedging activity in Financials.
Commodities
$90.42/bbl for Brent and $83.67/bbl for WTI kept oil firm, with Brent up about 16.07% over a month, per Reuters. Elevated crude prices lift Energy cash flows but raise fuel, packaging, and freight costs for manufacturers and retailers. The inflation impulse can keep yields sticky, reinforcing valuation pressure across growth equities.
World Affairs
21 million bpd historically transit the Strait of Hormuz (EIA), and Reuters reports Houthi threats of a Saudi naval blockade alongside a tanker strike, elevating energy-security risk. Insurance and rerouting costs rise as shippers price wider disruption. Markets translate this into a durable oil risk premium and higher macro uncertainty for equities and credit.
Supply Chain
11% of the global container fleet was at anchor and Asia→US West Coast spot rates are up roughly 120% since mid-May, Flexport notes, while Reuters tracked tanker sailings totaling just under 2 million barrels through Hormuz in cited moves. Tight capacity and blank sailings (~3%) extend lead times and push delivered input costs higher. Inventory planning cushions matter as schedules remain uneven.
AI
430 MW of committed load for Applied Digital’s Delta Forge campus and a proposed 756 MW gas plant to serve it, per Telborg/Cleco filings, underscore sustained AI power demand. That expands Utilities capex pipelines, tightens local transmission needs, and supports IT hardware and high-bandwidth memory orders even as higher yields pressure tech multiples today.
Industry News
$1,932 for Ethereum (+1.46% day, +20.05% month) came alongside renewed ETF inflows, with Ether ETF assets near $10 billion and U.S. spot Bitcoin ETFs around $78 billion, CoinDesk reports. Institutional flows can lift custody, exchange, and payments activity, adding revenue and volatility to crypto-exposed Financials and IT rails.
Industry Forecast
Today’s Setup
2026-07-21 is a Four Green Wood (Shiroku Mokusei, 四緑木星) day in a Three Blue Wood month and One White Water year during Shosho (Lesser Heat). With a Center (Chūkyū, 中宮) pull, today rewards planning-heavy operators: elevated oil and freight keep cost control front and center, the firm dollar tightens financing, and demand signals propagate through logistics and credit channels.
Focus Sectors
Financials (9.0/10): 4.598% on the 10-year UST and a firm USD/JPY 162.733 lift asset-sensitive net interest income and keep FX/rates trading active, while Brent $90.42 adds hedging and underwriting flow. Banks and brokers benefit from volumes across credit, commodities, and currencies as clients rebalance. Watch deposit betas and funding spreads to avoid NIM compression if rate paths shift. Policy shifts (Basel III endgame) could lift capital requirements and weigh on buybacks; track SLOOS for loan demand and standards.
Industrials (8.4/10): 11% of the container fleet at anchor and Asia→US West Coast rates up ~120% since mid-May, per Flexport, keep freight tight as Brent hovers near $90. Firms with disciplined orderbooks, automation, and pricing can still convert backlog when supplier-delivery times stabilize. Dollar strength can dent export competitiveness, so mix and localization matter. Monitor ISM Manufacturing PMI Supplier Deliveries (supplier delivery times) for relief or further strain, and watch bunker-fuel trends versus contracted surcharges.
Information Technology (7.2/10): A 430 MW AI campus and a proposed 756 MW gas plant (Telborg/Cleco) point to durable data-center and power procurement, supporting servers, accelerators, and high-bandwidth memory (HBM). Crypto ETF inflows add payments and infrastructure volumes, but the 10-year at 4.598% caps multiples near term. Supply risks in advanced packaging and HBM pricing remain; follow TrendForce’s DRAM/HBM contract index for margin signals and align shipments to power-interconnect timelines to avoid stranded inventory.
Consumer Discretionary (6.6/10): Asia→US West Coast ocean rates are ~120% higher since mid-May and ~11% of the fleet is at anchor (Flexport), while Brent near $90 lifts gasoline and delivery costs. That squeezes retailer margins and big-ticket demand as APRs track higher yields. Operators with supply-chain visibility and omnichannel conversion can defend share, but categories without pricing power may lean on promotions. Watch the U.S. Census Retail Sales Control Group for core demand quality and monitor surcharge passthrough to protect gross margin.
Watchlist
Financials: Federal Reserve Senior Loan Officer Opinion Survey (SLOOS) (quarterly U.S. survey of bank lending standards and loan demand across business and consumer credit).
Industrials: ISM Manufacturing PMI Supplier Deliveries (Institute for Supply Management; monthly supplier delivery times — higher readings mean slower deliveries/tighter supply).
Information Technology: TrendForce DRAM and HBM contract price index (monthly pricing for DRAM and high-bandwidth memory; a gauge of component cost and supply tightness).
Consumer Discretionary: U.S. Census Retail Sales Control Group (monthly core retail sales used in GDP tracking; proxy for discretionary spending momentum).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories, refinery utilization, and implied demand).
Consumer Staples: BLS CPI Food at Home index (monthly measure of grocery price inflation faced by consumers; pass-through pressure gauge).
Materials: S&P Global Manufacturing PMI Input Prices (monthly input-cost inflation for manufacturers; feedstock and freight cost signal).
Real Estate: MSCI Real Assets RCA CPPI (commercial property price index tracking U.S. sector-level price changes; valuation trend).
Utilities: EIA Electric Power Monthly (U.S. electricity generation mix, retail sales, and average prices; demand and fuel-cost recovery context).
Health Care: Kaufman Hall National Hospital Flash Report (monthly hospital operating margins, volumes, and expense trends; utilization and cost pressure).
Communication Services: S&P Global U.S. Services PMI New Business Index (monthly gauge of new orders across services, including marketing and media; ad-demand proxy).
Caveats
A solar-term rollover toward Great Heat could alter near-term power demand patterns and fuel spreads, changing Utilities and Energy nuances. A sustained ceasefire in the Gulf or a rapid easing of congestion would compress oil and freight premia, softening today’s read.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Gulf chokepoints, freight congestion, and rate volatility argue for resilience over prediction. Firms that pre-arrange liquidity, shipping slots, and power interconnects can keep executing even if disruptions persist or rotate. The structural edge is in buffers and optionality, not perfect timing.
Action: Raise buffer thresholds and pre-book critical capacity; monitor SLOOS and the EIA reports to adjust credit and fuel hedges in real time.
Today’s Points
Gulf escalation keeps Brent around $90.42/bbl and lifts input‑cost risk while USD/JPY trades near 162.733, feeding 10Y UST at 4.598% and compressing rate‑sensitive multiples (Dow 51,839).
Shipping friction remains material: ~11% of the global container fleet was at anchor and Asia→US West Coast spot rates have risen ~120% since mid‑May, while tanker sailings cited carried ~2 million barrels in recent transits (Reuters).
AI capex persists at scale — Applied Digital’s Delta Forge calls for 430 MW of load and ~$3.6B campus investment, implying sustained demand for power, HBM/memory and data‑center hardware.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.