

Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
Good morning. A softer June CPI print meets a renewed oil shock and sticky long yields, keeping funding costs in focus while AI capex stays firm. Brent above $85 and elevated freight rates raise goods costs even as inflation cools. The durable AI build-out, evidenced by TSMC’s record revenue, underpins chips, equipment, and power demand despite geopolitical noise.
Paywall
Stocks and FX
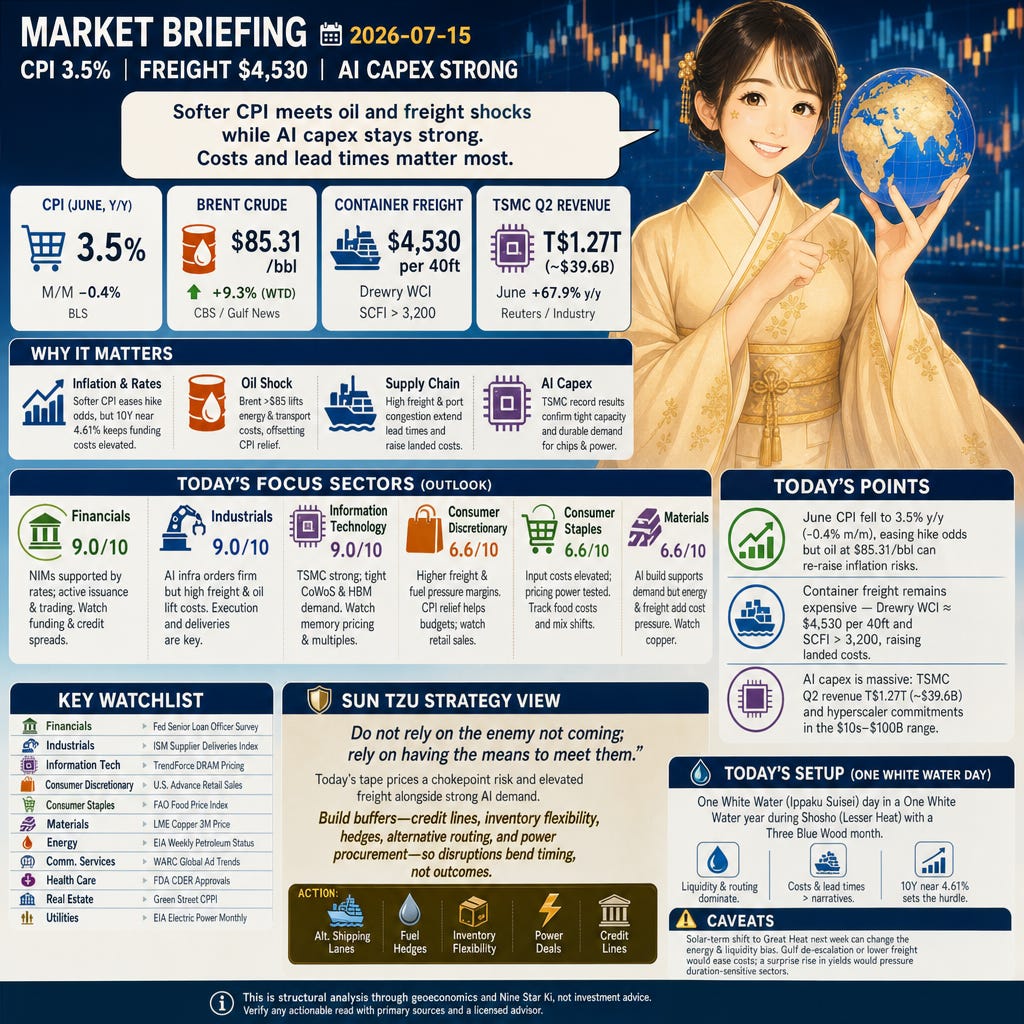
3.5% CPI year-on-year and -0.4% month-on-month (BLS) set the tone as the S&P 500 printed 7,515 and the Nikkei 225 68,752, with USD/JPY at 162.377 and the 10Y UST near 4.61% (market snapshot). The softer CPI reduced immediate Fed-hike odds, but a 4-handle on the 10-year kept discount rates elevated, pressuring some growth multiples. The print helps payments and trading volumes while long rates still tax leveraged balance sheets and capex-heavy plans.
Commodities
$85.31/bbl Brent and $79.86/bbl WTI (snapshot) extended a three-day rise, with Brent up about 9.3% on the week per Gulf News coverage. Higher crude filters into transport, packaging, and household energy costs, offsetting some CPI relief. The move supports upstream Energy cash flow while tightening margins for energy-intensive Industrials, Materials, and Consumer sectors.
World Affairs
$85.31/bbl Brent and $79.86/bbl WTI reflect CBS-reported renewed U.S. strikes on Iran and a reinstated naval blockade affecting Hormuz traffic. A blockade raises disruption risk to Gulf crude and tanker routes, lifting insurance premia and widening risk spreads. The channel is clear: higher energy and freight costs plus geopolitical risk premia can sap risk appetite and financing conditions.
Supply Chain
$4,530 per 40ft on Drewry’s WCI and SCFI readings above 3,200 (Seabridge/Drewry) signal expensive ocean freight. Reports of blank sailings near 7% and port congestion extend lead times and working-capital cycles. Retailers and manufacturers face higher landed costs and timing risk into seasonal demand, while logistics-heavy tenants absorb rising operating expenses.
AI
T$1.27 trillion (~$39.6B) Q2 revenue at TSMC, with June at T$442.68B (+67.9% y/y), confirms tight foundry capacity and persistent AI demand (Reuters/industry reports). Multi‑year compute and power deals by hyperscalers keep capex elevated, supporting chip equipment, HBM memory pricing, and server OEM pipelines. The load-growth implication is tangible for Utilities and grid-adjacent Industrials.
Industry News
$100B‑scale multi‑year AI compute commitments, alongside TSMC’s T$1.27T (~$39.6B) Q2 revenue and an approximately $1.95T market capitalization in market summaries, show a reweighted corporate capex mix (sector briefs). The money is flowing to semiconductors, advanced packaging, data‑center builds, and long‑dated power procurement. That creates durable demand visibility for IT, Industrials, Materials, and Utilities build‑outs.
Industry Forecast
Today’s Setup
2026-07-15 is a One White Water (Ippaku Suisei, 一白水星) day in a One White Water year during Shosho (Lesser Heat). With a Three Blue Wood month, liquidity and routing dominate: financing terms, shipping lanes, and data/power capacity determine who converts demand into revenue. Expect costs and lead times to matter more than narratives while long yields near 4.61% set the hurdle rate.
Focus Sectors
Financials (9.0/10): 3.5% CPI eases hike odds, but a ~4.61% 10Y keeps funding costs and term premia elevated, sustaining net interest margins while tempering loan appetite. AI-driven issuance and fee pools stay active as TSMC’s T$1.27T Q2 underlines durable compute demand, supporting underwriting, trading, and payments at the system’s center. Watch wholesale funding and credit spreads if Hormuz risk widens; monitor SLOOS for lending standards and demand inflections.
Industrials (9.0/10): Drewry WCI ~$4,530/FEU, SCFI >3,200, and Brent near $85/bbl lift input and transport costs even as AI infrastructure orders hold up. Firms with execution depth and machinery breadth can convert backlog while supplier deliveries remain stable. Risks are sustained freight/oil and a financing drag from ~4.61% 10Y yields; watch ISM Supplier Deliveries for any slip in lead times that would stall backlog burn.
Information Technology (9.0/10): TSMC’s T$1.27T (~$39.6B) Q2 revenue and June +67.9% y/y signal tight foundry and advanced packaging/HBM demand, benefiting equipment, materials, and server OEMs. Fundamentals are firm, but higher discount rates near a 4.61% 10Y can compress multiples. Bottlenecks in CoWoS and HBM remain the gating factor; track TrendForce’s DRAM pricing for supply‑demand shifts and shipment timing risk.
Consumer Discretionary (6.6/10): WCI ~$4,530 and SCFI >3,200 raise landed costs, while Brent near $85/bbl nudges pump prices, squeezing discretionary budgets. Softer CPI at 3.5% supports real incomes and card throughput, but retailers face a margin trade‑off between pricing, promo, and conversion. Delivery timing into back‑to‑school and holiday sets matters; watch Advance Retail Sales for demand resilience versus shipping‑cost drag.
Consumer Staples (6.6/10): Elevated ocean freight and fuel costs pressure grocery and household‑goods procurement, testing pricing power in retailer negotiations. CPI cooling helps real consumption, yet mix shifts and private‑label competition can slow unit-margin repair. Exposure to global food inputs adds a second cost channel; track FAO Food Price Index for commodity swings that could tighten gross margins further.
Materials (6.6/10): Brent near $85 and high container rates lift energy and logistics costs, while AI build‑outs sustain pull for copper, specialty chemicals, and lithography inputs. Gulf-route risk can disrupt petrochemical feedstocks and insurance costs. Margins hinge on energy/freight normalization and steady capex pipelines; watch LME Copper for demand tightness and any sign of a construction or electronics slowdown.
Watchlist
Financials: Federal Reserve Senior Loan Officer Opinion Survey (quarterly bank lending standards and loan‑demand trends).
Industrials: ISM Manufacturing Supplier Deliveries Index (monthly gauge of supplier lead times and delivery performance).
Information Technology: TrendForce DRAM contract price tracker (monthly memory pricing that reflects HBM/DRAM supply‑demand).
Consumer Discretionary: U.S. Census Advance Monthly Retail Sales (monthly topline for discretionary categories and e‑commerce).
Consumer Staples: FAO Food Price Index (monthly global food commodity costs that shape input inflation).
Materials: LME Copper 3‑month official price (daily benchmark for industrial metal demand/supply tightness).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude/product inventories and refinery utilization).
Communication Services: WARC Global Ad Trends (monthly revisions to digital and total ad spend growth).
Health Care: FDA CDER Drug and Biologic Approvals (monthly approvals that set near‑term revenue catalysts).
Real Estate: Green Street Commercial Property Price Index (monthly transaction‑based gauge of U.S. commercial real estate prices).
Utilities: EIA Electric Power Monthly (monthly U.S. generation, demand, and capacity‑factor data that signal load growth and fuel mix).
Caveats
A mid‑month solar‑term shift toward Great Heat next week can alter the energy‑and‑liquidity bias just as earnings guides land. Rapid de‑escalation in the Gulf or a swift retreat in freight would soften the cost channel; conversely, a surprise re‑acceleration in yields would challenge duration‑sensitive sectors.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Today’s tape prices a chokepoint risk and elevated freight alongside strong AI demand. Build buffers—credit lines, inventory flexibility, hedges, alternative routing, and power procurement—so disruptions bend timing, not outcomes.
Action: Pre‑arrange capacity: secondary shipping lanes, fuel hedges, and modular power deals to absorb shocks without repricing plans.
Today’s Points
June CPI fell to 3.5% y/y (-0.4% m/m), easing immediate Fed‑hike odds but competing with an oil shock (Brent $85.31/bbl) that can re‑raise inflation risks.
Container freight remains expensive — Drewry WCI ≈ $4,530 per 40ft and SCFI readings >3,200 — implying higher landed costs and margin pressure for retailers and manufacturers.
AI capex is still massive: TSMC Q2 revenue T$1.27 trillion (~$39.62B) and multi‑year hyperscaler compute commitments reported in the $10s–$100B range signal durable demand for chips, servers and power infrastructure.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.
Tiger Capital Research さん、いいねありがとうございます。読んでいただけてうれしいです。