Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
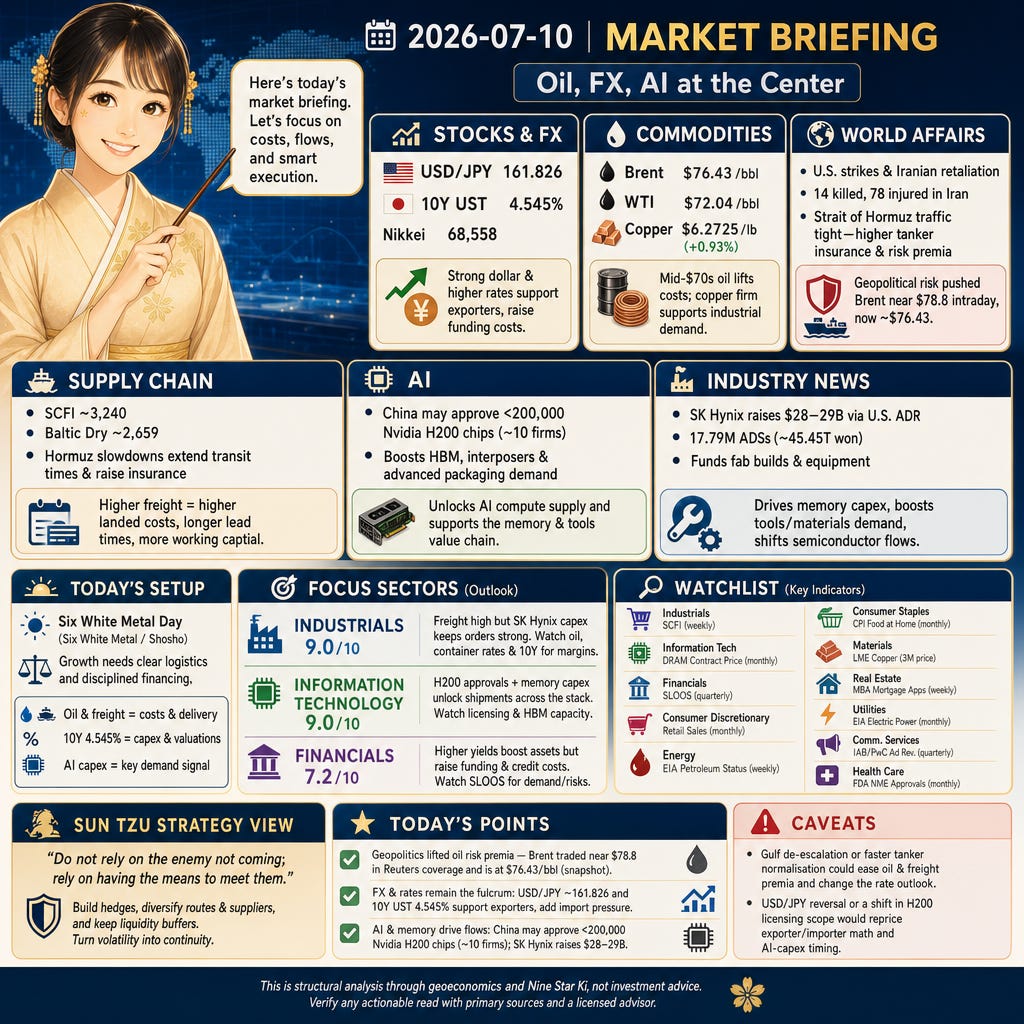
Geopolitics, funding costs, and AI supply sit at the center today. Brent is holding in the mid-$70s after Gulf strikes, USD/JPY hovers near 162 with the U.S. 10-year at 4.545%, and China may allow a limited Nvidia H200 flow while SK Hynix’s $28–29B ADR funds memory and packaging capex. Freight costs (SCFI ~3,240; Baltic ~2,659) keep landed costs and delivery times in focus.
Stocks and FX
USD/JPY 161.826 and a 10Y UST yield of 4.545% frame a strong-dollar, higher-rate tape, per Reuters (via MarketScreener). The yen near four‑decade lows around 162 supports Japanese exporter earnings in JPY terms, helping keep the Nikkei at 68,558. The same rate backdrop raises discount rates for long-duration tech and lifts funding costs for Financials, pressuring valuation multiples where cash flows are back‑weighted.
Commodities
Brent 76.43 $/bbl and WTI 72.04 $/bbl sit below this week’s intraday Brent print near 78.8, Reuters reports, while copper firmed to 6.2725 $/lb (+0.93% on the day). Mid‑$70s crude tightens Energy margins via refinery crack spreads and raises transport and packaging costs for Industrials and Consumer Discretionary. Higher oil can also lift inflation expectations, supporting yields (10Y 4.545%) and compressing rate‑sensitive equity multiples.
World Affairs
14 killed and 78 injured across five Iranian provinces were reported after U.S. strikes and Iranian retaliation, per Reuters, with some datasets showing Strait of Hormuz traffic near a standstill. The chokepoint risk inflated tanker insurance and physical premia, driving Brent toward 78.8 intraday before settling near 76.43. Tighter crude flows can push inflation expectations and keep yields firm, impacting Energy cash flows, Industrials shipping costs, and Financials’ risk pricing.
Supply Chain
SCFI ~3,240 and the Baltic Dry Index ~2,659 (Shanghai Shipping Exchange/Baltic via Investing.com) signal elevated container and bulk rates. Reported slowdowns around the Strait of Hormuz extend transit times and raise insurance premiums on some crude routes. For planners, this lengthens lead times, increases landed costs, and raises working‑capital needs for inventory, especially for retailers and capital‑goods makers.
AI
Fewer than 200,000 Nvidia H200 units and roughly 10 licensed Chinese buyers are in view, per Reuters/The Information. That loosens a key compute bottleneck and can pull through HBM memory, interposers, and advanced packaging capacity, supporting Information Technology hardware and select Communication Services workloads. Supply cadence and licensing scope will shape shipment timing and revenue exposure to China for chipmakers and component vendors.
Industry News
$28–29B in proceeds (17.79M new ADSs; ~45.45T won) from SK Hynix’s U.S. ADR listing are earmarked for fab builds and equipment, Reuters reports. The funding wave underwrites HBM and memory capex, supporting demand for semiconductor tools (ASML and peers), specialty materials, and factory automation. It also redistributes liquidity within semiconductors, with potential re‑weighting among memory producers as capital intensity rises.
Industry Forecast
Today’s Setup
2026-07-10 is a Six White Metal (Roppaku Kinsei, 六白金星) day in the Shosho (Lesser Heat) solar term. With a Three Blue Wood (Sanpeki Mokusei, 三碧木星) month and a One White Water (Ippaku Suisei, 一白水星) year, execution quality converts growth only where logistics clear and financing is disciplined. Read today through costs and flows: freight and oil shape delivery and COGS, while 10Y 4.545% sets the hurdle for capex and valuations; AI capex remains the gating demand signal.
Focus Sectors
Industrials (9.0/10): SCFI ~3,240 and the Baltic Dry ~2,659 raise freight costs, but SK Hynix’s $28–29B ADR push into fabs and tools keeps orderbooks supported for precision machinery and factory automation. Gulf tanker reroutes add insurance and time, yet throughput is still converting to revenue where delivery
reliability holds. Watch oil and container rates for margin squeeze, and the 10Y 4.545% for customer hurdle rates on equipment purchases.
Information Technology (9.0/10): China’s prospective approval for fewer than 200,000 Nvidia H200s (about 10 firms) plus SK Hynix’s capex raise unlock GPU, HBM, and advanced packaging shipments across the stack. That supports memory and tool vendors even as higher yields (10Y 4.545%) pressure valuation multiples. Monitor export-control cadence and tight HBM/CoWoS capacity that can cap quarterly shipments despite strong orders.
Financials (7.2/10): A 10Y UST at 4.545% lifts asset yields but also deposit beta and wholesale funding costs, while mid‑$70s oil can nudge inflation expectations and credit pricing. Balance‑sheet mix and pricing power matter most as markets reprice risk premia. Key risks are higher‑for‑longer rates compressing NIM and potential capital add‑ons that limit payouts; watch SLOOS for demand and standards direction.
Watchlist
Industrials: Shanghai Containerized Freight Index, SCFI (Shanghai Shipping Exchange — weekly China export container spot rates).
Information Technology: TrendForce DRAM contract price index (monthly benchmark for server/PC DRAM pricing and memory-cycle strength).
Financials: Federal Reserve Senior Loan Officer Opinion Survey, SLOOS (Board of Governors — quarterly lending standards and loan demand).
Consumer Discretionary: U.S. Census Advance Monthly Retail Sales (Census Bureau — monthly nominal retail spending by category).
Energy: EIA Weekly Petroleum Status Report (U.S. Energy Information Administration — weekly crude inventories, product stocks, and refinery utilization).
Consumer Staples: BLS CPI: Food at Home (U.S. Bureau of Labor Statistics — monthly grocery-price inflation as a proxy for input pass-through).
Materials: LME Copper 3-Month price (London Metal Exchange — benchmark industrial metal price signaling global demand).
Real Estate: MBA Mortgage Applications (Mortgage Bankers Association — weekly mortgage demand and refinance activity).
Utilities: EIA Electric Power Monthly (U.S. Energy Information Administration — generation mix, retail electricity prices, and demand).
Communication Services: IAB/PwC U.S. Internet Advertising Revenue Report (Interactive Advertising Bureau — quarterly digital ad spend levels).
Health Care: FDA CDER New Molecular Entity approvals (U.S. Food and Drug Administration — monthly count of first‑time drug approvals as a proxy for pipeline conversion).
Caveats
A rapid Gulf de‑escalation or faster tanker normalisation would compress oil and shipping premia, easing inflation expectations and changing the rates read. A sharp USD/JPY reversal on official intervention or a surprise shift in H200 licensing scope would reprice exporter/importer math and AI‑capex timing.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Today’s tape rewards firms that can absorb oil and freight shocks and operate under 10Y 4.545% funding: hedges, diversified routing, and liquidity buffers convert volatility into continuity. In AI, modular capex and alternative suppliers reduce dependency on a single licensing cadence and packaging node.
Action: Keep shock absorbers in place: maintain fuel and freight hedges, diversify suppliers, and monitor SCFI, Brent, USD/JPY, and SLOOS for stance shifts.
Today’s Points
Geopolitics lifted oil risk premia — Brent traded near $78.8 in Reuters coverage and is at $76.43/bbl (snapshot), tightening Energy and shipping risk.
FX and rates remain the cross‑asset fulcrum: USD/JPY ~161.826 and 10Y UST 4.545% are supporting exporters (Nikkei 68,558) while adding import/inflation pressure.
AI and memory continue to drive flows: China may approve <200,000 Nvidia H200 chips (about 10 Chinese firms licensed) and SK Hynix’s $28–29B ADR raises 17.79M ADSs, channeling capital into memory capex.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.