Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
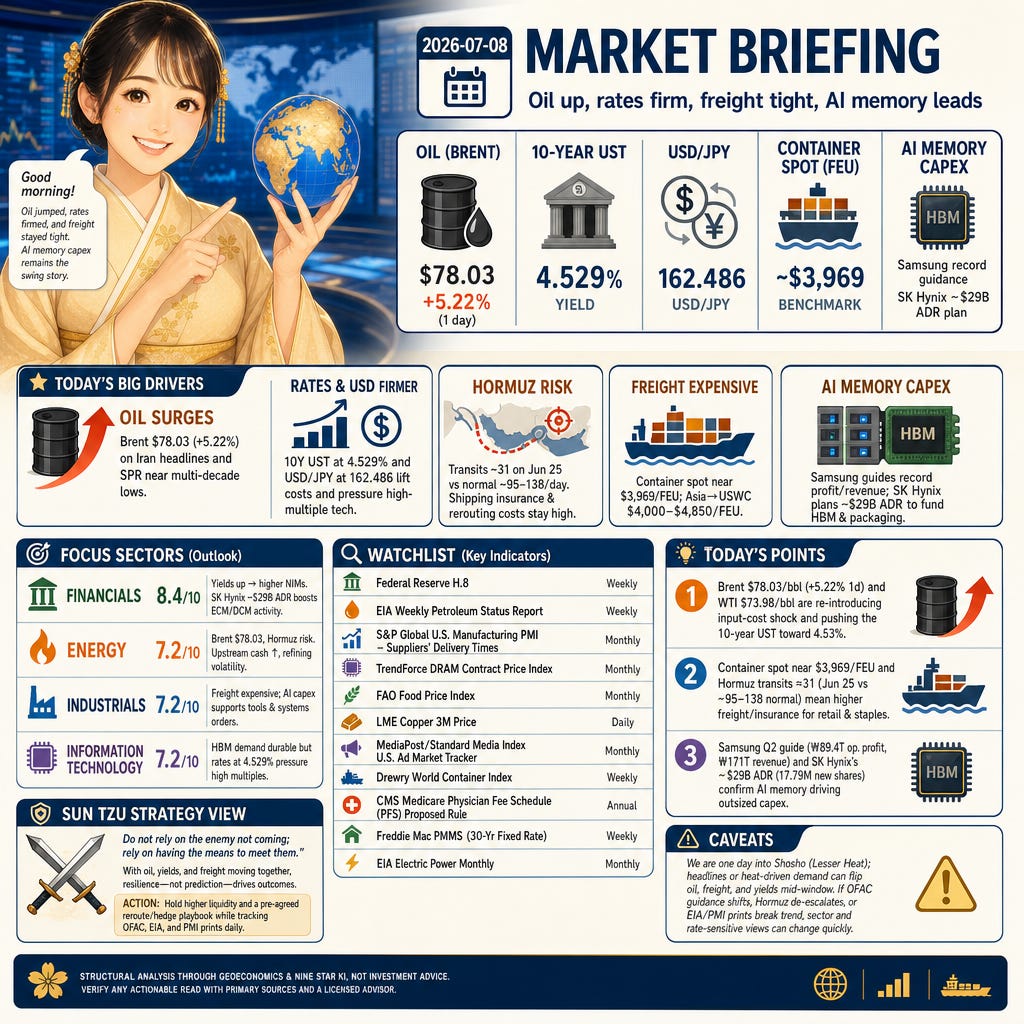
Good morning—oil jumped, rates firmed, and freight stayed tight. Brent near $78 and the 10-year UST at 4.529% raised input costs and discount rates as USD/JPY printed 162.486. Container spot rates around $3,969/FEU and depressed Hormuz transits keep logistics premia elevated. AI memory capex remains the swing story with Samsung’s record guidance and SK Hynix’s planned ~$29B ADR.
Stocks and FX
10-year U.S. Treasury yields printed 4.529% and USD/JPY traded at 162.486 as equities slipped, with the S&P 500 at 7,504 and Nasdaq at 25,819 in the Reuters snapshot via Euronext; the Nikkei 225 was 66,819. The move was tied to oil’s jump and U.S.–Iran headlines. Higher yields and a firmer dollar tighten financial conditions, pressuring high‑multiple tech and media while supporting bank net interest margins.
Commodities
Brent rose 5.22% to $78.03/bbl and WTI 5.03% to $73.98/bbl (Reuters via Euronext). Reporting noted U.S. SPR stocks at their lowest since 1983, magnifying supply sensitivity. Dearer crude lifts feedstock, packaging, and transport costs, raising inflation risk and compressing margins for fuel‑intensive sectors even as Energy upstream cash flow improves.
World Affairs
OFAC revoked Iran’s oil sales license with a wind‑down to July 17 (Axios), re‑raising supply‑security risk through the Strait of Hormuz. The shift coincided with Brent near $78 and the 10‑year UST at ~4.53% as markets priced tighter barrels into inflation and rates. The channel runs through commodity prices, shipping insurance, and financial conditions.
Supply Chain
Container benchmarks hovered near $3,969/FEU, with Asia→USWC lanes around $4,000–$4,850/FEU (Phaata). Windward data show Hormuz transits far below normal—about 31 crossings on June 25 versus historical ~95–138/day—keeping rerouting and insurance premia elevated. Expect longer lead times and higher landed costs, pressuring retail and staples while supporting transport pricing.
AI
Samsung guided to about ₩89.4T operating profit and ₩171T revenue for Q2 (Reuters), yet shares fell ~6–7% on sustainability concerns. The print underscores HBM and advanced‑packaging demand even as higher yields raise discount rates for long‑duration tech. Fab and substrate capacity remain the bottleneck; timing of hyperscaler spend is the swing factor for suppliers.
Industry News
SK Hynix filed for a Nasdaq ADR to raise ~$29–29.4B by issuing ~17.79M new shares, targeting a U.S. debut around July 10 (MarketWise). Proceeds will fund HBM fabs and advanced packaging, lifting multi‑year capex across lithography, tools, and substrates. The deal also broadens global investor access and feeds underwriting and trading revenues for banks.
Industry Forecast
Today’s Setup
2026-07-08 is an Eight White Earth (Happaku Dosei, 八白土星) day under Shosho (Lesser Heat), with Three Blue Wood (Sanpeki Mokusei, 三碧木星) in the month and One White Water (Ippaku Suisei, 一白水星) in the year. Translation: consolidate cash and balance sheets while keeping networks fluid—NIM and discount rates matter on a 4.53% 10‑year, fuel and freight surcharges shape costs, and the operators who reroute fastest protect margins.
Focus Sectors
Financials (8.4/10): 10-year UST at 4.529% and a firmer dollar (Reuters via Euronext) lift net interest margins while marking AFS/HTM duration books. ECM/DCM is open—SK Hynix’s ~$29B ADR points to underwriting, custody, and trading fees. Focus on deposit mix and securities duration; rising oil could keep
policy tight and credit costs elevated. Watch the Federal Reserve H.8 for real‑time shifts in loans, securities, and deposits, and be ready to hedge further curve backup risk.
Energy (7.2/10): Brent at $78.03 (+5.22%) and WTI at $73.98 (+5.03%) reflect OFAC’s Iran move and constrained Hormuz flows (Axios; Reuters). Upstream cash generation improves and trading spreads widen; refiners see crack volatility with SPR near multi‑decade lows in reporting. Route risk is elevated—hedge differentials and freight. Key risk is demand destruction if high prices persist. Track EIA Weekly Petroleum Status Report for inventory and utilization swings.
Industrials (7.2/10): Container spot near ~$3,969/FEU and Asia→USWC $4,000–$4,850/FEU (Phaata) support transport yields even as fuel costs rise. AI memory capex—Samsung’s record guidance and SK Hynix’s ADR—extends orders for tools, material handling, and fab systems (Reuters; MarketWise). Margin defense hinges on surcharges and mix. If higher yields slow approvals, equipment orders could slip. Watch S&P Global U.S. Manufacturing PMI—Suppliers’ Delivery Times for easing bottlenecks.
Information Technology (7.2/10): Samsung’s ₩89.4T operating‑profit and ₩171T revenue guide (Reuters) plus SK Hynix’s ~$29B ADR (MarketWise) confirm durable HBM demand and packaging build‑out, pulling through lithography and substrates. But the tape is rate‑sensitive: a 4.529% 10‑year lifts discount rates and compresses high‑multiple valuations. Bottlenecks in CoWoS/substrates cap shipments near‑term. Watch TrendForce’s DRAM contract price index for pricing power and order cadence risks if hyperscaler timing slips.
Watchlist
Financials: Federal Reserve H.8 weekly report (commercial bank loans, securities, and deposits — a real‑time read on NIM drivers and credit supply).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories plus refinery utilization).
Industrials: S&P Global U.S. Manufacturing PMI — Suppliers’ Delivery Times (monthly gauge of parts lead times and logistics congestion).
Information Technology: TrendForce DRAM contract price index (monthly benchmark for server DRAM/HBM pricing).
Consumer Staples: FAO Food Price Index (monthly global basket of commodity food prices that feeds into COGS).
Materials: London Metal Exchange Copper 3‑month price (LME benchmark for industrial demand and risk sentiment).
Communication Services: MediaPost/Standard Media Index U.S. Ad Market Tracker (monthly total ad spending across major channels).
Consumer Discretionary: Drewry World Container Index (weekly spot FEU rates on key lanes, a direct read on retail freight costs).
Health Care: CMS Medicare Physician Fee Schedule (PFS) proposed rule (annual update to reimbursement rates and coverage policies).
Real Estate: Freddie Mac Primary Mortgage Market Survey (weekly 30‑year fixed mortgage rate — a proxy for real estate financing costs).
Utilities: EIA Electric Power Monthly (U.S. generation mix, fuel costs, and retail electricity prices — inputs to rate‑case narratives).
Caveats
We are one day into Shosho (Lesser Heat); heat‑driven demand spikes or policy headlines can flip oil, freight, and yields mid‑window. If OFAC guidance shifts, Hormuz de‑escalates, or EIA/PMI prints break trend, the read on Energy/Industrials strength and rate‑sensitive multiple pressure would change quickly.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With oil, yields, and freight moving together, resilience—not prediction—drives outcomes. Build buffers in cash and liquidity, diversify shipping routes and suppliers, and pre‑arrange hedges so shocks are absorbed rather than priced in after the fact.
Action: Hold higher liquidity and a pre‑agreed reroute/hedge playbook while tracking OFAC, EIA, and PMI prints daily.
Today’s Points
Brent at $78.03/bbl (+5.22% one day) and WTI at $73.98/bbl are re‑introducing an input‑cost shock for Energy and Industrials and helping push the 10‑year UST toward 4.53%.
Container spot benchmarks near $3,969/FEU and Strait of Hormuz transits (≈31 on June 25 vs ~95–138 normal) mean higher freight/insurance premia for Consumer Discretionary and Staples.
Samsung’s Q2 guidance of ₩89.4T operating profit and SK Hynix’s planned ~$29B ADR (17.79M new shares) confirm AI memory is driving outsized capex and sector re‑allocation into Information Technology and Industrials.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.