Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
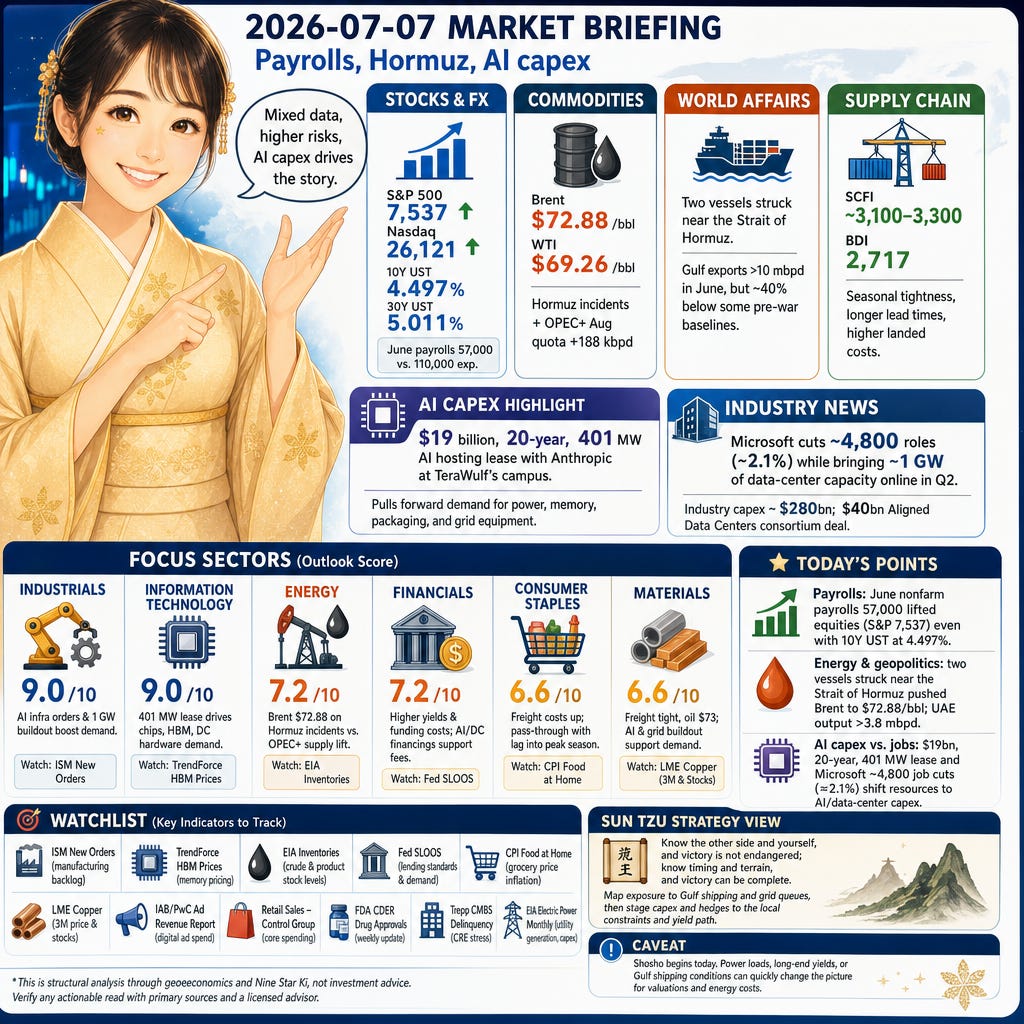
Good morning. A weak 57,000 June payrolls print lifted risk assets even as the 10Y and 30Y hold near 4.50% and 5.01%. Brent at $72.88 on Hormuz incidents and SCFI/BDI firmness keep cost pressure live. AI capex is the clearest through-line: a $19bn, 20‑year, 401 MW lease concentrates demand into power, memory, and grid equipment.
Stocks and FX
S&P 500 7,537 and Nasdaq 26,121 advanced after the June payrolls print of 57,000 (vs. 110,000 expected), while the 10Y UST held at 4.497% and the 30Y at 5.011% (Reuters). GBP/USD printed 1.3382, EUR/USD 1.1439, and USD/JPY 161.867 as rate-path repricing softened the dollar at the front end even with long-end yields elevated. High duration costs cap multiple expansion for rate-sensitive equities, but the softer data release supports near-term risk appetite.
Commodities
Brent settled around $72.88/bbl and WTI at $69.26/bbl after reports of two vessels struck near the Strait of Hormuz (Reuters). The supply backdrop includes UAE output above 3.8 mbpd and OPEC+ signaling a +188 kbpd quota lift from August. The mix of episodic security premia and managed supply keeps energy input costs volatile, feeding into refinery margins and transport/bunker surcharges that filter through to Industrials and Materials pricing.
World Affairs
Two vessels were struck near the Strait of Hormuz, reviving shipping-security concerns as Brent ticked to $72.88 and maritime insurance alerts rose (Reuters). Gulf exports exceeded 10 mbpd in June but remain roughly 40% below some pre-war baselines, implying persistent friction in seaborne flows. The channel is cost and routing: higher insurance/bunker and risk-driven detours can tighten effective supply and raise delivered costs for Energy and transport-exposed industries.
Supply Chain
BDI 2,717 and SCFI composites in the ~3,100–3,300 range signal seasonal tightness across container and dry-bulk lanes (C.H. Robinson; Baltic Exchange). Port omissions, equipment shortages, and tariff-pull-forward extend lead times and lift landed and inventory-carrying costs. For planning, that means earlier ordering, higher working capital, and selective price pass-through into peak season, especially for Industrials, Consumer Discretionary, and Materials.
AI
A $19 billion, 20‑year, 401 MW AI hosting lease with Anthropic at TeraWulf’s campus formalizes multi-year compute demand (Reuters). That pulls forward needs for HBM/memory, advanced packaging, power delivery, and grid interconnection, supporting visibility for Information Technology and specialized data-center Real Estate. The constraint shifts to power and memory supply; delays there can push out ramp timing even as valuations lean on contracted capacity.
Industry News
Microsoft will cut about 4,800 roles (~2.1% of workforce) while bringing ~1 GW of data-center capacity online in Q2, amid an industry capex surge that some trackers place near $280 billion (Reuters; datacentres.com). A $40 billion Aligned Data Centers consortium deal underscores access-to-capital as a differentiator. The read-through is reallocation from operating expense to fixed AI infrastructure, deepening demand for chips, power gear, and construction while compressing near-term payroll outlays.
Industry Forecast
Today’s Setup
On 2026-07-07, a Nine Purple Fire (Kyushi Kasei, 九紫火星) day in a Three Blue Wood (Sanpeki Mokusei, 三碧木星) month and One White Water (Ippaku Suisei, 一白水星) year lands exactly at Shosho (Lesser Heat). Expect attention to cluster around measurable buildouts—AI data centers, grid gear—while chokepoints (Hormuz, freight, interconnection queues) and elevated long-end yields steer costs, financing conditions, and delivery timelines.
Focus Sectors
Industrials (9.0/10): $19bn of contracted AI capacity over 20 years and ~1 GW of new hyperscale in Q2 translate into orders for switchgear, large transformers, HVAC, and construction. SCFI strength and a Baltic Dry Index of 2,717 lift freight and bunker costs but also enforce backlog discipline and pricing. Oil near $73 adds a modest logistics headwind. Key risk is power‑equipment bottlenecks and any rates‑driven pause that slows project recognition; watch ISM New Orders for backlog conversion.
Information Technology (9.0/10): A 401 MW, $19bn AI lease and hyperscalers shifting spend from labor to compute keep demand tight for semiconductors, HBM, CoWoS packaging, and DC hardware/software. Contracted capacity boosts top-line visibility even as a 10Y near 4.50% compresses multiples. Risks are
HBM/packaging caps and grid interconnection delays that push out ramps; export‑control shifts would crimp units. Track TrendForce’s DRAM/HBM prices for supply‑demand balance.
Energy (7.2/10): Brent at $72.88 on Hormuz incidents offsets the easing signal from OPEC+ (+188 kbpd in August) and UAE output above 3.8 mbpd. Episodic security premia can widen refined‑product spreads and raise LNG/shipping insurance, while managed supply anchors ranges. Escalation would tighten flows and lift costs; a faster OPEC+ unwind would pressure prices and margins. Monitor EIA inventories and utilization for near‑term balance and refining margin read‑through.
Financials (7.2/10): With the 10Y ~4.50% and 30Y ~5.01%, discount rates and funding costs stay high even as weaker payrolls support risk sentiment. AI/data‑center financings help underwriting and fees, but deposit competition and a lumpy curve squeeze net interest margin. CRE remains rate‑sensitive. Risks include higher credit costs if growth slips and stubbornly high deposit betas. Watch the Fed’s SLOOS for lending standards and loan demand.
Consumer Staples (6.6/10): SCFI composites around ~3,100+ and a BDI of 2,717 raise landed and carrying costs into peak categories. Big brands can pass through with a lag—visible in grocery prices and mix—while distribution depth sustains volumes. Persistent surcharges or consumer fatigue would pinch gross margins; private‑label share gains are the competitive risk. Track BLS CPI ‘Food at Home’ for pass‑through effectiveness versus volume resilience.
Materials (6.6/10): Freight tightness (SCFI elevated; BDI 2,717) and oil near $73 extend lead times and transport/input costs across metals and chemicals. Offsetting, AI and grid buildouts firm demand for copper, steel, cement, and specialty materials tied to data‑center shells and power delivery. Volatile Chinese demand and Gulf‑route risks could whipsaw prices and working capital. Watch LME copper 3‑month and stocks for tightness signaling and procurement timing.
Watchlist
Industrials: ISM Manufacturing PMI – New Orders (Institute for Supply Management; monthly gauge of U.S. factory order intentions and backlog conversion).
Information Technology: TrendForce DRAM/HBM contract price tracker (TrendForce; monthly pricing and supply-demand balance for memory critical to AI servers).
Energy: EIA Weekly Petroleum Status Report (U.S. Energy Information Administration; weekly crude/product inventories and refinery utilization).
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey; quarterly lending standards and loan-demand conditions across banks).
Consumer Staples: BLS CPI ‘Food at Home’ index (U.S. Bureau of Labor Statistics; monthly grocery price inflation as a proxy for pass-through).
Materials: London Metal Exchange copper – 3‑month price and warehouse stocks (LME; daily gauge of copper market tightness).
Communication Services: IAB/PwC Internet Advertising Revenue Report (Interactive Advertising Bureau/PwC; quarterly U.S. digital ad spend levels).
Consumer Discretionary: U.S. Census Bureau Advance Monthly Retail Sales – control group (monthly core retail spending proxy excluding autos, gas, and building materials).
Health Care: FDA CDER Drug Approvals – weekly update (U.S. Food and Drug Administration; running list of newly approved drugs and indications).
Real Estate: Trepp CMBS Delinquency Rate (Trepp; monthly share of commercial mortgages 30+ days delinquent, a gauge of CRE stress).
Utilities: EIA Electric Power Monthly (U.S. Energy Information Administration; monthly utility‑scale generation, capacity additions, and retail electricity sales).
Caveats
Shosho begins today, and early-summer power loads can shift the balance between data-center ramp timing and utility interconnection, altering Utilities and Industrials reads mid-window. A sharp move in long-end yields or a rapid change in Gulf shipping conditions would override today’s range-bound assumptions for valuations and energy costs.
Sun Tzu Strategy View
Sun Tzu wrote: —— Know the other side and yourself, and victory is not endangered; know timing and terrain, and victory can be complete.
Today’s edge comes from reading chokepoints (Hormuz, SCFI, grid queues) alongside rate timing: capacity is available only where terrain—security, freight, and power—permits. Align project starts and procurement with those constraints to protect margins and delivery schedules.
Action: Map exposure to Gulf shipping and grid queues, then stage capex and hedges to the local constraints and yield path.
Today’s Points
Payrolls: June nonfarm payrolls 57,000 helped lift equities (S&P 7,537) even with 10Y UST at 4.497% driving mixed risk pricing.
Energy & geopolitics: two vessels struck near the Strait of Hormuz pushed Brent to $72.88/bbl while UAE output topped 3.8 million bpd, weighing on longer-term risk premia.
AI capex vs. jobs: Anthropic’s ~ $19 billion, 20‑year, 401 MW lease and Microsoft’s ~4,800 job cuts (≈2.1% of workforce) underscore a shift of resources toward data‑center capex (hyperscaler capex industry reads ~$280bn).
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.