Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
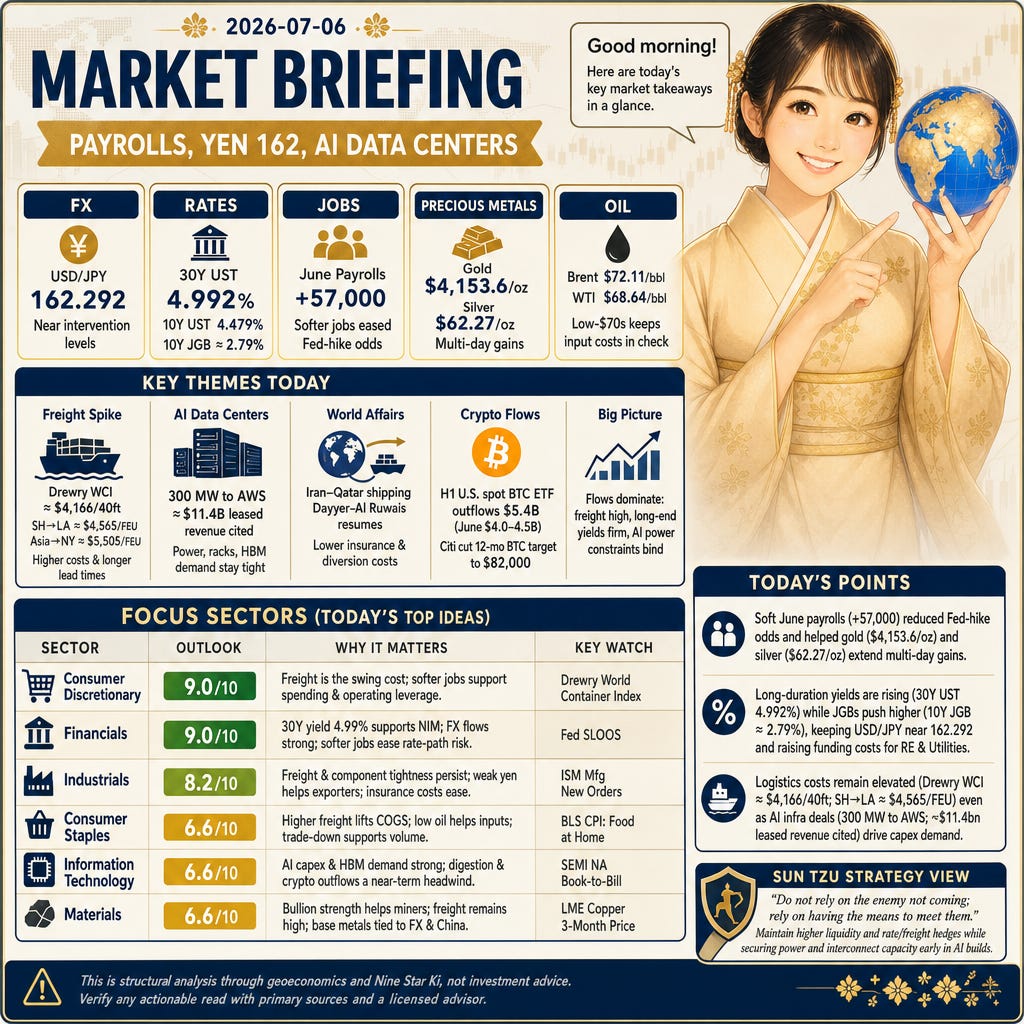
Good morning. Softer U.S. payrolls eased near-term Fed hike odds even as long-end yields stayed firm and the yen hovered near intervention levels. Container freight remains elevated into peak season, while AI data‑centre contracts keep power and memory demand tight. Precious metals extended gains; oil stays in the low‑$70s, capping input-cost pressure.
Stocks and FX
162.292 on USD/JPY and 4.992% on the U.S. 30Y yield frame today’s tape, Reuters reports, with the 10Y at 4.479% and Japan’s 10Y JGB near 2.79%. The weak yen boosts currency-hedged returns in Japan while raising import costs for yen buyers. Softer June payrolls (+57,000) trimmed Fed-hike risk and supported equities (S&P 500 7,525; Nasdaq 26,123). A firm long end still tightens financing for rate‑sensitive borrowers, pressuring Real Estate and Utilities but supporting bank NIM if deposit costs lag.
Commodities
$62.27/oz silver and $4,153.6/oz gold extended multi‑day gains after the +57,000 payrolls print cooled Fed bets, Reuters notes. $72.11/bbl Brent and $68.64/bbl WTI keep upstream cashflow capped and reduce near‑term fuel and packaging inflation for manufacturers and retailers. Rising bullion aids precious‑metals miners (Materials) but lifts input hedging needs for electronics that use silver and gold.
World Affairs
5 months after a pause, Iran–Qatar shipping between Dayyer and Al Ruwais has resumed, Reuters reports, with Brent at $72.11/bbl and WTI at $68.64/bbl reflecting some eased route premia. Lower insurance and diversion costs reduce surcharges for regional cargoes, trimming a piece of Middle East risk in Energy and Industrials supply chains.
Supply Chain
$4,166 per 40‑ft on Drewry’s WCI, ~$4,565/FEU Shanghai→Los Angeles, and ~$5,505/FEU Asia→New York mark a sharp freight spike, per Drewry and Freightos coverage. Higher ocean spot rates raise landed costs, lengthen lead times, and pull more working capital into inventory, pressuring Consumer Discretionary and Industrials margins unless pricing power holds.
AI
300 MW of capacity slated for AWS and roughly $11.4 billion of contracted leases highlight AI data‑centre demand, Investing.com reports. Multi‑year, take‑or‑pay deals lift specialized REIT/infra revenues and pull through power equipment, racks, accelerators, and HBM memory. The buildout raises Utilities capex plans and keeps advanced‑packaging and memory capacity tight.
Industry News
$5.4 billion in H1 net outflows from U.S. spot Bitcoin ETFs, with June redemptions around $4.0–4.5 billion, prompted Citi to cut its 12‑month BTC target to $82,000, per DWF Labs and CoinDesk coverage. With BTC at $61,908 and ETH at $1,748, thinner ETF demand pressures crypto‑linked equities and fee pools across Information Technology, Communication Services, and Financials.
Industry Forecast
Today’s Setup
2026-07-06 is a One White Water (Ippaku Suisei, 一白水星) day in a One White Water year, with the Four Green Wood (Shiroku Mokusei, 四緑木星) month; the Shosho (Lesser Heat) solar term starts on July 7. Expect flows—payments, freight, data—to dominate outcomes: elevated ocean rates and firm long-end yields raise working-capital and financing needs, while AI power and interconnect constraints shape who can convert demand into revenue.
Focus Sectors
Consumer Discretionary (9.0/10): Freight is the swing cost. Drewry’s WCI near $4,166/40‑ft lifts landed costs even as Brent around $72/bbl tempers fuel surcharges. Softer U.S. payrolls reduce immediate Fed‑hike risk, supporting checkout conversion and operating leverage. Platforms with pricing power and flexible sourcing can pass through surcharges and protect gross margin. Risks: another leg up in Asia–U.S. spot rates or FX whipsaws into peak season. Watch: Drewry World Container Index for pass‑through timing and inventory planning.
Financials (9.0/10): A 4.99% 30Y UST supports asset yields and can widen NIM if deposit betas remain contained. USD/JPY near 162 sustains FX flow for dealer desks, while H1 crypto ETF outflows (~$5.4bn) weigh on crypto‑linked fees. Softer payrolls ease immediate rate‑path anxiety, aiding credit formation. Risks:
duration losses if long yields lurch higher and a late‑cycle credit turn if labor softens; rising JGB yields (~2.79% 10Y) add rate sensitivity for Japan‑exposed books. Watch: Fed SLOOS for standards and loan demand.
Industrials (8.2/10): Elevated container spot rates (WCI ~$4,166; SH→LA ~$4,565/FEU) raise landed costs and stretch lead times. Brent near $72 and the Iran–Qatar maritime restart trim some route insurance costs, while a weak yen helps Japan‑heavy exporters. Procurement remains tight for AI‑linked components. Operating leverage improves as supplier delivery times stabilize and surcharges normalize. Risks: port congestion or further WCI spikes forcing margin give‑ups or shipment pushouts; FX volatility around USD/JPY extremes. Watch: ISM Manufacturing New Orders.
Consumer Staples (6.6/10): Higher container rates lift inbound COGS and working capital, but low‑$70s oil eases packaging and transport inputs. As real incomes adjust to a softer jobs tape, trade‑down can support private‑label volume, keeping cash flow defensive even if promo intensity rises. Risks: sustained Asia–U.S. freight inflation outpacing price pass‑through; FX and agricultural prints (grains, softs) that re‑accelerate basket inflation. Watch: BLS CPI – Food at Home for pricing power and elasticity.
Information Technology (6.6/10): AI capex and advanced packaging drive demand: a 300‑MW AWS lease and roughly $11.4bn of contracted revenue pull accelerators and HBM through the chain. Near term, digestion and higher logistics costs tug against momentum, and rising silver/gold prices lift some bill‑of‑materials. Crypto ETF outflows reduce a side‑pocket of miner/fintech demand, but hyperscaler compute is the core. Risks: HBM/CoWoS bottlenecks and export‑control shifts. Watch: SEMI NA book‑to‑bill for equipment order health.
Materials (6.6/10): Bullion strength (gold ~$4,154/oz; silver ~$62/oz) supports precious‑metals miners, while Brent near $72 eases some petrochemical feedstock pressure. The Iran–Qatar maritime restart trims insurance and routing costs regionally, but container‑dependent specialty chemicals still face elevated freight. Base metals remain tied to FX and China demand. Risks: stronger USD weighing on metals, freight escalation squeezing margins, and permitting/royalty shifts delaying projects. Watch: LME Copper 3‑month price for industrial demand and macro risk appetite.
Watchlist
Consumer Discretionary: Drewry World Container Index (weekly global spot rates for a 40‑ft container across major lanes).
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey — quarterly U.S. bank lending standards and loan demand).
Industrials: ISM Manufacturing PMI: New Orders Index (monthly gauge of U.S. factory order flow from the Institute for Supply Management).
Consumer Staples: BLS CPI: Food at Home (monthly U.S. grocery price inflation, a proxy for staples pricing power).
Information Technology: SEMI North America semiconductor equipment book‑to‑bill ratio (monthly orders-to-billings gauge for chip‑equipment demand).
Materials: LME Copper 3‑month official price (daily London Metal Exchange benchmark for industrial‑metal demand and macro risk appetite).
Real Estate: Green Street Commercial Property Price Index (monthly private‑market commercial real‑estate price levels and trends).
Utilities: EIA Electric Power Monthly (U.S. retail electricity sales and utility‑scale generation by sector).
Health Care: BLS CPI: Medical Care Services (monthly U.S. price changes for health services, a proxy for reimbursement/pricing power).
Communication Services: Standard Media Index U.S. Ad Market Tracker (monthly actual ad spend compiled from agency billing data).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude inventories, product stocks, and refinery utilization).
Caveats
Shosho (Lesser Heat) begins on July 7, and solar‑term shifts can change how flow vs. capacity constraints show up mid‑week. Rates and freight prints are snapshots; a sharp reversal in the 30Y UST or a WCI pullback would alter the sector skew, and some AI‑deal figures come from issuer‑linked research notes.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With container rates high, long yields firm, and AI power constraints binding, the risk is not whether shocks arrive but how quickly they propagate through freight, funding, and grid interconnects. Balance sheets, hedges, and alternate routing should be sized to absorb another leg up in freight or rates without forcing margin give‑ups.
Action: Maintain higher liquidity and rate/freight hedges while securing power and interconnect capacity early in AI builds.
Today’s Points
Soft June payrolls (+57,000) reduced Fed-hike odds and helped gold ($4,153.6/oz) and silver ($62.27/oz) extend multi-day gains.
Long-duration yields are rising (30Y UST 4.992%) while JGBs push higher (10Y JGB ≈2.79%), keeping USD/JPY near 162.292 and raising funding costs for Real Estate and Utilities.
Logistics costs remain elevated (Drewry WCI ≈ $4,166/40ft; SH→LA ≈ $4,565/FEU) even as AI infra deals (300 MW to AWS; ~$11.4bn leased revenue cited) drive energy and data‑centre capex demand.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.