Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
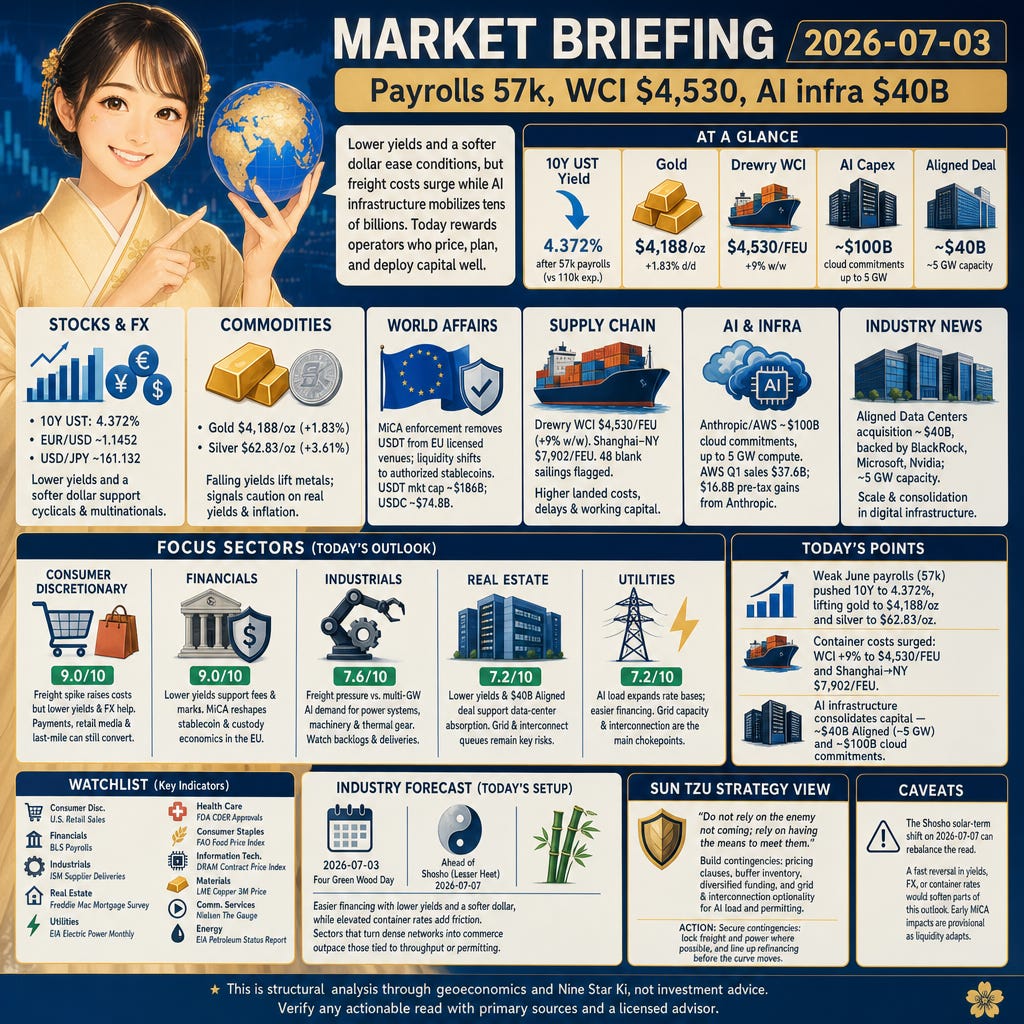
Good morning. Lower U.S. yields and a softer dollar are easing financial conditions as container freight spikes reset delivered costs. AI infrastructure continues to mobilize tens of billions, concentrating demand for power and space. Today rewards operators who can pass through shipping costs while redeploying capital toward data-center and grid bottlenecks.
Stocks and FX
4.372% on the 10Y UST after June payrolls printed 57,000 vs 110,000 expected (Investing.com reporting Reuters); the Dow hit 52,900 while the Nasdaq lagged at 25,833 and the S&P 500 at 7,483. EUR/USD traded near 1.1452 and USD/JPY around 161.132, reflecting a softer dollar. Lower discount rates support cyclicals and balance sheets with refinancing needs, while FX translation helps multinationals in Consumer Discretionary and Industrials.
Commodities
$4,188/oz gold (+1.83% d/d) and $62.83/oz silver (+3.61% d/d, four-day streak) rose as yields fell (MarketScreener citing Reuters). The rates-to-metals channel tightens input costs for jewelry and electronics and can shift hedging behavior for investors with rate-sensitive exposures. Precious-metals strength also signals caution around real yields and inflation expectations.
World Affairs
July 1 MiCA enforcement in the EU removed USDT from licensed venues as EU liquidity shifts toward authorised stablecoins (Bloodstone). USDT’s market cap is about $186B versus USDC at ~$74.8B; Bitcoin hovered near 61,902 and Ethereum 1,734 amid record June ETF outflows. Liquidity fragmentation raises compliance and custody costs for exchanges and Financials with crypto exposure, with knock‑ons to related IT platforms.
Supply Chain
$4,530 per FEU on Drewry’s World Container Index (WCI) after a 9% weekly jump, with Shanghai→New York at $7,902/FEU and 48 blank sailings flagged (Drewry via gCaptain). Higher spot and reliability risks lift landed costs, extend lead times, and raise working‑capital needs for retailers and manufacturers. Freight tightness also supports logistics pricing power and encourages inventory buffering into peak season.
AI
~$100B of reported multi‑year Anthropic/AWS cloud commitments and up to 5 GW of AI compute, alongside Amazon’s Q1 AWS sales of $37.6B and $16.8B pre‑tax gains from Anthropic (Amazon filings via StockTitan), underscore sustained AI capex. That supports demand for accelerators, HBM memory, power systems, and grid upgrades, benefiting Information Technology, Utilities, and data‑center Real Estate.
Industry News
~$40B for Aligned Data Centers, backed by BlackRock, Microsoft, and Nvidia, with roughly 5 GW of operational and planned capacity (AP), highlights consolidation and scale in digital infrastructure. The transaction implies rising valuations for power‑dense campuses and continued capital deployment into interconnection and grid capacity, supporting Real Estate, Utilities, and server/semiconductor suppliers.
Industry Forecast
Today’s Setup
2026-07-03 is a Four Green Wood (Shiroku Mokusei, 四緑木星) day in a Four Green Wood month, set within a One White Water (Ippaku Suisei, 一白水星) year, ahead of the Shosho (Lesser Heat) solar term on 2026-07-07. Expect financing to flow more easily with lower yields and a softer dollar, while elevated container rates introduce friction in goods flows; sectors that convert dense networks into commerce outpace those tied to throughput or permitting.
Focus Sectors
Consumer Discretionary (9.0/10): $4,530/FEU on Drewry’s WCI (+9% w/w) and 48 blank sailings lift landed costs and stress delivery windows, but 10Y at 4.372% and a softer dollar ease credit and improve FX translation. Payments, retail media, and last‑mile networks can still convert traffic into margin if pricing holds and
stock‑outs are contained. Watch retail sales mix and promo intensity as pass‑through tests consumer elasticity.
Financials (9.0/10): 10Y at 4.372% after a 57,000 payrolls print supports fee income, underwriting, and marks on securities, even as a bull‑flattening compresses NIM. MiCA’s EU rollout reshapes stablecoin liquidity and custody economics, a niche but real P&L line. Monitor loan demand and credit quality if labor softness persists; liquidity fragmentation can trim EU crypto‑related fees.
Industrials (7.6/10): WCI at $4,530 and transpacific $7,902/FEU raise freight and inventory‑carry costs; 48 blank sailings risk delays unless pricing power offsets. Countervailing demand persists from multi‑GW AI data‑center builds, lifting orders for power systems, precision machinery, and thermal gear. Track supplier deliveries and backlog health to gauge whether freight friction is stalling shipments or simply shifting timing.
Real Estate (7.2/10): Lower market yields improve cap‑rate math and refinancing terms, while a ~$40B Aligned deal (~5 GW) and reported AWS/Anthropic commitments sustain data‑center absorption. Power‑dense, interconnect‑rich campuses have the advantage as tenants lock capacity early. Risks center on interconnection queues and construction inflation if freight remains elevated; watch mortgage‑rate prints for broader funding tone.
Utilities (7.2/10): Multi‑GW AI load expands regulated asset bases and rate‑case visibility, with easier financing as yields fall. Grid capacity and interconnection are the chokepoints; utilities positioned to deliver peaking and transmission upgrades should see clearer capex lanes. Fuel‑cost volatility and siting delays remain the main risks; track generation mix and capacity factors for signs of margin pressure or relief.
Watchlist
Consumer Discretionary: U.S. Census Advance Monthly Retail Sales (monthly U.S. retail spending, including the GDP control group).
Financials: BLS Employment Situation (monthly U.S. nonfarm payrolls and average hourly earnings that steer rate expectations and the yield curve).
Industrials: ISM Manufacturing PMI — Supplier Deliveries (monthly U.S. delivery times; lower readings indicate faster deliveries).
Real Estate: Freddie Mac Primary Mortgage Market Survey (weekly U.S. mortgage rates that feed into cap rates and refinancing).
Utilities: EIA Electric Power Monthly (U.S. generation mix, retail sales, and capacity factors).
Health Care: FDA CDER Drug and Biologic Approvals (monthly U.S. approvals of new drugs and biologics).
Consumer Staples: FAO Food Price Index (monthly global food-commodity price benchmark).
Information Technology: TrendForce DRAM contract price index (monthly DRAM and HBM memory pricing used in servers and AI).
Materials: LME Copper 3-month price (London Metal Exchange benchmark for industrial-metals demand and supply tightness).
Communication Services: Nielsen The Gauge (monthly U.S. TV and streaming share as a proxy for attention and ad inventory).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories and refinery utilization).
Caveats
The Shosho solar‑term shift on 2026-07-07 can rebalance the read toward heat‑driven power demand and seasonal logistics rhythms. A fast reversal in yields, FX, or a quick easing of container rates would soften parts of today’s tilt; early MiCA impacts are also provisional as liquidity adapts.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Freight spikes, softer rates, and shifting EU crypto rules can land simultaneously; the edge goes to teams with pricing clauses, buffer inventory, and diversified funding. Build grid and interconnection optionality now so AI load and permitting delays are manageable rather than existential.
Action: Secure contingencies: lock freight and power where possible, and line up refinancing before the curve moves.
Today’s Points
Weak June payrolls (57,000) pushed the 10Y UST to 4.372%, lifting gold to $4,188/oz and silver to $62.83/oz — a classic rates→precious‑metals transmission.
Container costs surged: Drewry WCI +9% to $4,530/40ft and Shanghai→NY at $7,902/FEU, implying higher landed costs for Consumer Discretionary and Industrials and tighter inventories.
AI infrastructure continues to consolidate capital — Aligned’s acquisition (~$40B, ~5 GW capacity) and reported Anthropic/AWS commitments (up to 5 GW; ~$100B cloud spend) mean sustained capex for IT, Utilities and Real Estate exposure.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.