


Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
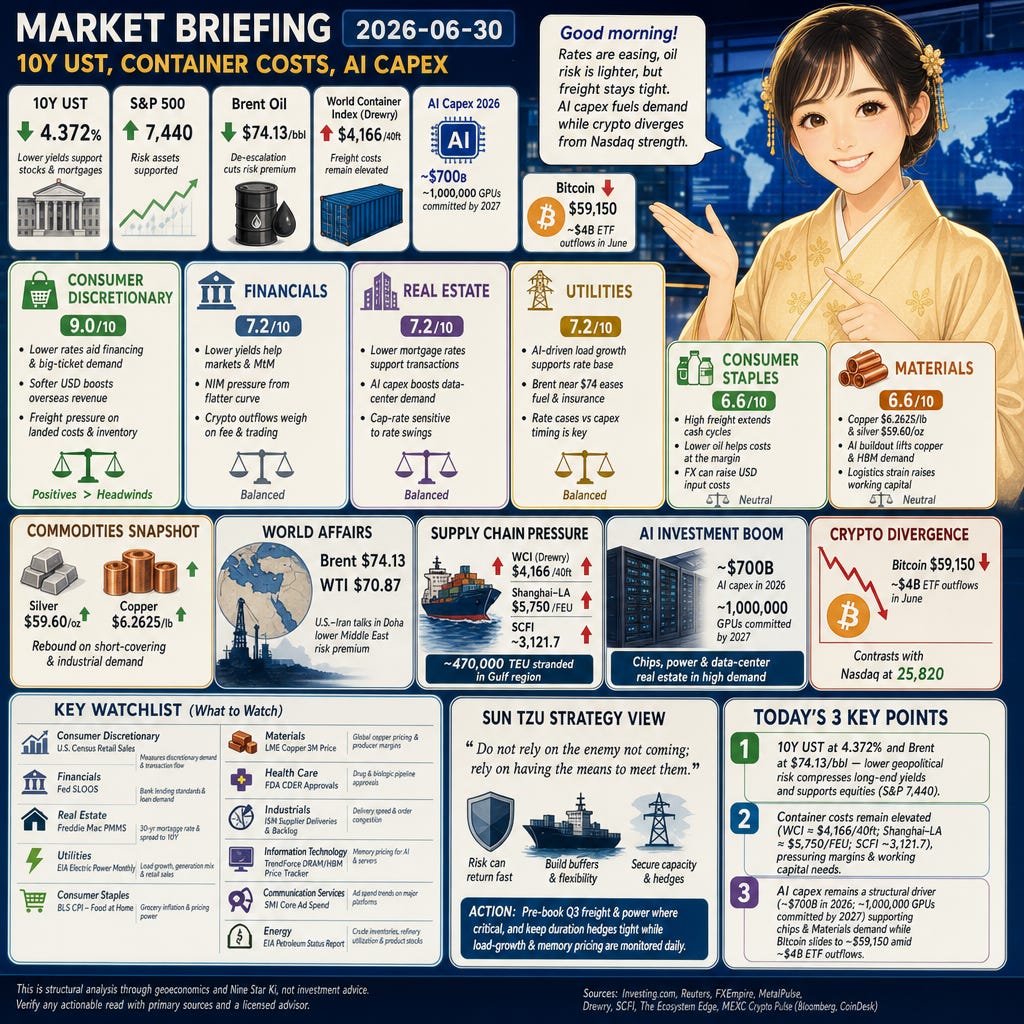
Good morning — the tape opens with rates easing, oil’s risk premium lighter, and freight still tight. The 10-year UST at 4.372% supports equity valuations and mortgage channels as Brent holds near $74.13. Container costs (WCI ≈ $4,166/40ft; Shanghai–LA ≈ $5,750/FEU) keep pressure on import-heavy sectors. AI capex near $700B anchors demand for chips, power, and data-center real estate, while crypto weakness diverges from Nasdaq strength.
Stocks and FX
4.372% on the 10-year UST coincided with the S&P 500 at 7,440 and the Nasdaq at 25,820, while EUR/USD printed 1.1399, GBP/USD 1.3225, and USD/JPY 162.395, per Investing.com/Reuters. Lower long yields reduce equity discount rates and financing costs for mortgages and investment-grade debt, aiding risk assets. A softer dollar lifts overseas revenue translation for global Consumer Discretionary and Tech names and supports dollar-priced commodity revenues for Materials and Energy.
Commodities
$59.60/oz for silver and $6.2625/lb for copper marked a rebound driven by short-covering and industrial demand, according to FXEmpire and MetalPulse. Higher copper tightens input costs for Industrials and some Consumer Durables, while supporting Materials producers tied to electrification and data-center buildouts. Precious-metals swings feed inflation expectations and can influence real yields and FX, shaping valuation math for rate-sensitive equities.
World Affairs
$74.13/bbl for Brent and $70.87/bbl for WTI reflect de-escalation hopes as U.S. and Iranian negotiators head to Doha, Reuters reports. With roughly one-fifth of seaborne oil transiting the Strait of Hormuz, even tentative talks trim the Middle East risk premium. Lower crude eases headline inflation and reinforces the bond rally that pulled the 10-year to 4.372%, while modestly reducing freight-insurance and working-capital costs for importers.
Supply Chain
Paid content below this line
$4,166 per 40ft on Drewry’s World Container Index and about $5,750/FEU on Shanghai–Los Angeles, plus an SCFI near 3,121.7, keep landed costs elevated (Drewry/SCFI via industry aggregation). Reports of roughly 470,000 TEU stranded in the Gulf region add route uncertainty. Retailers and Industrials face longer cash-conversion cycles and margin squeeze, while Shipping & Logistics pricing power holds.
AI
~$700B in 2026 AI capex and ~1,000,000 GPUs committed through 2027 keep advanced-node and CoWoS packaging sold out into 2027, The Ecosystem Edge notes. Tight supply supports semiconductor pricing and visibility for chipmakers, while raising BOM costs and prepay needs for OEMs. The buildout drives incremental MW demand for Utilities and data-center Real Estate, and lifts Materials via copper cabling and HBM inputs.
Industry News
$59,150 for Bitcoin came alongside roughly $4B of June spot-ETF outflows and an up-to-$1.25B sale authorization, contrasting with a Nasdaq at 25,820, per MEXC Crypto Pulse citing Bloomberg/CoinDesk. Reduced crypto liquidity pressures funding and trading revenue for crypto-adjacent Financials and ad spend on large platforms, even as AI-led equity strength persists.
Industry Forecast
Today’s Setup
2026-06-30 is a Seven Red Metal (Shichiseki Kinsei, 七赤金星) day in Boshu (Grain in Ear), a phase that favors commerce and transaction flow. Expect lower discount rates (10Y at 4.372%) to buoy consumer and fee/flow businesses even as elevated ocean freight (WCI ≈ $4,166; Shanghai–LA ≈ $5,750) keeps import costs sticky; AI infrastructure demand continues to pull copper, power, and data-center capacity into focus.
Focus Sectors
Consumer Discretionary (9.0/10): 4.372% on the 10-year lowers discount rates and auto/large-ticket financing, while a softer dollar supports overseas revenues (Investing.com/Reuters). Elevated freight (WCI ≈ $4,166/40ft; Shanghai–LA ≈ $5,750/FEU) still pressures landed costs and inventory turns (Drewry/SCFI). Net, transaction-heavy flow on a Seven Red Metal day can reveal operating leverage if fulfillment is predictable. Watch sustained container-rate strength and any Gulf routing delays (~470k TEU exposure).
Financials (7.2/10): Long-end yields slipping to 4.372% aid capital markets and mark-to-market, but can compress NIM (net interest margin) as funding costs lag lower (Investing.com/Reuters). Softer sovereign and insurance premia on Middle East de-escalation help risk perception. Crypto ETF outflows (~$4B in June) and sales (~$1.25B) weigh on trading/fee lines for exposed desks (MEXC). Key risk is deeper curve flattening or a bond reversal that hits securities books.
Real Estate (7.2/10): The 10-year at 4.372% pulls primary mortgage rates down, easing residential transactions and refinancing (Investing.com/Reuters). AI infrastructure capex (~$700B; ~1,000,000 GPUs committed) supports data-center demand, favoring power-proximate sites with interconnection visibility (The Ecosystem Edge). Income properties benefit from steadier rates, but cap-rate sensitivity remains. Risks: a rates rebound or grid interconnection delays that defer data-center cash flows.
Utilities (7.2/10): Data-center load growth tied to AI capex lifts rate-base expansion prospects and grid-upgrade pipelines (The Ecosystem Edge). Brent near $74 reduces some fuel and insurance inputs at the margin (Reuters). Regulated returns plus capex visibility align with defensiveness, but rate-case timing versus rising spend can pressure cash flows. If Gulf risk re-prices, fuel volatility could reappear in purchased-power costs.
Consumer Staples (6.6/10): Freight is the pinch-point: WCI ≈ $4,166/40ft and SCFI ~3,121.7 extend cash-conversion cycles and compress gross margins (Drewry/SCFI). Oil’s lower risk premium slightly eases transport and insurance, but a softer dollar can raise USD costs of imported ingredients and packaging (Reuters). Scale procurement and disciplined inventory help offset. Risks: persistent ocean-rate elevation and FX pass-through slippage at the shelf.
Materials (6.6/10): Copper around $6.2625/lb and silver near $59.60/oz support producer pricing and inventory marks (FXEmpire/MetalPulse). AI/data-center buildouts raise demand for copper cabling and certain HBM inputs, while a softer dollar aids commodities. Logistics strain (WCI/SCFI) can delay shipments and raise working capital. Risks: a metals-price retrace or shipment delays that whipsaw realized margins; watch LME curves for guidance.
Watchlist
Consumer Discretionary: U.S. Census Bureau Monthly Retail Trade Report (advance retail sales by category, the primary flow gauge for discretionary demand).
Financials: Federal Reserve Senior Loan Officer Opinion Survey (SLOOS) on Bank Lending Practices (quarterly changes in lending standards and loan demand).
Real Estate: Freddie Mac Primary Mortgage Market Survey (PMMS) (weekly 30-year fixed mortgage rate and its spread to the 10-year Treasury).
Utilities: EIA Electric Power Monthly (U.S. generation mix, demand, and retail sales trends that inform load growth and fuel cost pass-through).
Consumer Staples: BLS CPI — Food at Home Index (monthly grocery inflation indicating pricing power and input-cost pass-through).
Materials: London Metal Exchange (LME) Copper 3-Month Price (benchmark for global copper pricing and producer margins).
Health Care: U.S. FDA CDER monthly Drug and Biologic Approvals (pipeline conversion milestones that drive revenue inflections).
Industrials: ISM Manufacturing PMI — Supplier Deliveries and Backlog Indexes (monthly gauges of delivery speed and order congestion).
Information Technology: TrendForce DRAM/HBM Price Tracker (monthly contract pricing for AI memory used in accelerators and servers).
Communication Services: Standard Media Index (SMI) Core Ad Spend (monthly U.S. advertising outlays by category on major platforms).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude inventories, refinery utilization, and product stocks shaping spreads).
Caveats
A quick solar-term shift in early July can change the day-to-day tone, narrowing the Seven Red Metal commerce bias. A sharp reversal in oil or rates, or a fast normalization in ocean freight, would alter the sector dispersion more than today’s read implies.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
De-escalation headlines and a bond rally reduce pressure today, but Gulf routing risk and advanced-packaging bottlenecks can return quickly. Build buffers—flexible freight contracts, grid capacity reservations, and rate hedges—so operations hold when conditions flip.
Action: Maintain shock-ready posture: pre-book Q3 freight and power where critical, and keep duration hedges tight while load-growth and memory pricing are monitored daily.
Today’s Points
10Y UST at 4.372% and Brent at $74.13/bbl — lower geopolitical risk is compressing long-end yields and easing inflation risk premia, supporting equities (S&P 7,440).
Container costs remain elevated (World Container Index ≈ $4,166/40ft; Shanghai-LA ≈ $5,750/FEU; SCFI ~3,121.7), pressuring margins for Consumer Discretionary and Industrials and keeping working-capital needs high.
AI capex remains a structural demand driver (industry estimates ~ $700B in 2026; ~1,000,000 GPUs committed through 2027) propping up chip and Materials demand even as Bitcoin slides to ~$59,150 amid ~$4B of ETF outflows in June.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.
Tiger Capital Researchさん、いいねありがとうございます。読んでいただけてうれしいです。