Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
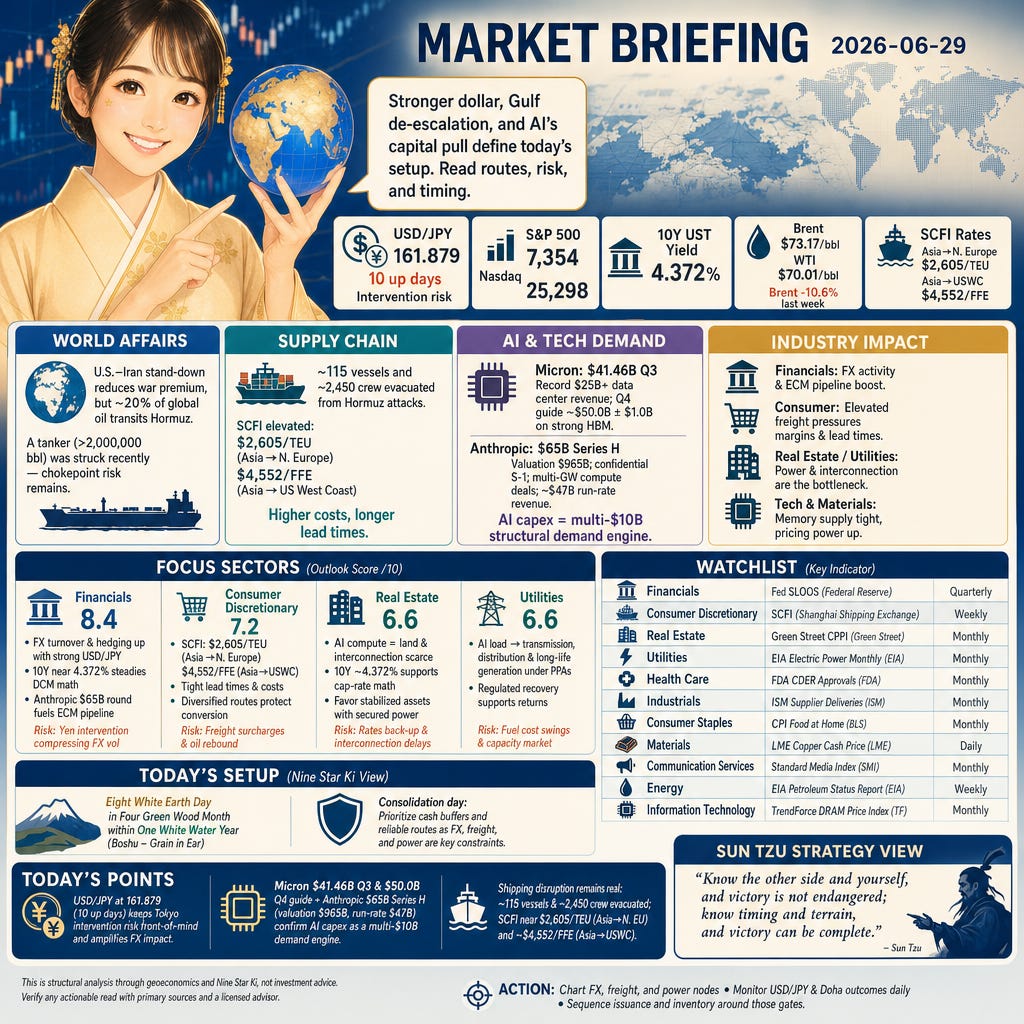
Good morning — a stronger dollar, Gulf de-escalation, and AI’s capital pull define today’s setup. USD/JPY at 161.879 keeps Tokyo intervention risk live as U.S. yields hover near 4.37%. Hormuz tensions have eased but ocean-freight lanes remain elevated, extending delivery times and costs. AI memory and compute demand from Micron and Anthropic concentrate pressure on power, data centers, and chip supply chains.
Stocks and FX
USD/JPY printed 161.879 as the dollar hovered near a one-year high, while the S&P 500 stood at 7,354 and the Nasdaq at 25,298; the 10-year UST yield was 4.372% (Reuters via Investing.com). Yen-intervention watch tempers outright FX carry while lower long-end yields support defensives over high-duration tech. The stronger dollar tightens translation for multinationals and lifts activity on banks’ FX desks, aiding Financials while pressuring Information Technology multiples.
Commodities
Brent traded $73.17/bbl and WTI $70.01/bbl, with Brent down 10.6% last week as Hormuz shipments rose (Reuters via Investing.com). A U.S.–Iran stand-down reduced the immediate war premium, but $73 crude still feeds transport and packaging costs for Industrials and Consumer sectors. Softer oil risk premia ease inflation expectations at the margin, reinforcing a 4.372% 10-year and supporting rate stability.
World Affairs
Roughly 20% of global seaborne oil transits Hormuz, and the U.S. and Iran agreed to halt reciprocal attacks with Doha talks slated around June 30 (RFE/RL). Reports noted at least one tanker carrying over 2,000,000 barrels was struck in recent days, highlighting persistent chokepoint risk. The stand-down trims the war premium and helps restore shipping throughput, a relief valve for Energy and Materials supply chains.
Supply Chain
Paid content below this line
About 115 vessels and ~2,450 crew were evacuated amid recent Hormuz attacks, and the IMO paused its emergency evacuation plan as transits recovered; SCFI Asia→North Europe sits near $2,605/TEU and Asia→US West Coast around $4,552/FFE (BusinessMirror; DSV). Elevated spot rates and reroutings extend lead times and raise landed costs for retailers and manufacturers. Inventory planning and safety stocks face renewed pressure, with margin squeeze risk if surcharges persist.
AI
Micron reported a record $41.46B quarter with data-center revenue above $25B and guided Q4 to ~$50.0B ± $1.0B, citing strong HBM (high-bandwidth memory) demand and record gross margin (Micron Technologies). Tight memory supply and accelerated AI capex lift semicap and memory pricing power but raise hardware costs for AI cloud operators. The result is stronger upstream cash flows and tighter downstream margins for AI-heavy services.
Industry News
Anthropic closed a $65B Series H at a $965B post-money valuation and filed a confidential S‑1, noting multi‑gigawatt compute deals (up to 5 GW each with AWS and with Google/Broadcom) and ~$47B run-rate revenue (Anthropic). The private mega-round deepens the ECM pipeline and redirects capital toward AI infrastructure. Expect continued demand for chips, advanced packaging, and power/land-constrained data centers, with knock-ons for Financials, Real Estate, and Utilities.
Industry Forecast
Today’s Setup
2026-06-29 is an Eight White Earth (Happaku Dosei, 八白土星) day within a Four Green Wood (Shiroku Mokusei, 四緑木星) month and a One White Water (Ippaku Suisei, 一白水星) year, during the Boshu (Grain in Ear) solar term. Read it as consolidation: prioritize cash buffers and reliable routes as a strong dollar shapes funding, elevated freight constrains supply, and data‑center power becomes the scarce input.
Focus Sectors
Financials (8.4/10): USD/JPY at 161.879 and a one‑year‑high dollar lift FX turnover and client hedging, supporting trading revenue; a 4.372% 10Y steadies DCM math. Anthropic’s $65B round and S‑1 point to an active ECM pipeline tied to AI. Watch yen‑intervention risk that could compress FX vol and issuance windows if risk‑off extends. Monitor the Federal Reserve Senior Loan Officer Opinion Survey for lending standards that set credit creation pace.
Consumer Discretionary (7.2/10): SCFI routes near $2,605/TEU (Asia→N. Europe) and ~$4,552/FFE (Asia→USWC) keep delivered costs and lead times tight even as a firm dollar trims some import prices. Retailers with diversified routings and clean inventories can protect conversion. Risks are Hormuz‑linked surcharges and an oil rebound hitting real incomes. Track SCFI weekly to time orders, promotions, and working‑capital buffers.
Real Estate (6.6/10): Multi‑GW AI compute deals spotlight land plus interconnection scarcity as the real bottleneck for data‑center builds. A 10Y UST near 4.372% helps cap‑rate math, while Eight White Earth favors stabilized assets with secured power and offtake. Risks are a rates back‑up and interconnection delays that strand demand. Use Green Street’s CPPI to gauge pricing and sequence development starts.
Utilities (6.6/10): Rising AI load shifts returns toward transmission, distribution, and long‑lived generation under PPAs, aligning with a defence/safety tilt for regulated recovery. Grid interconnection and permitting cadence govern when growth capex turns into revenue. Fuel‑cost swings and capacity‑market dynamics can pressure allowed returns between cases. Watch EIA Electric Power Monthly to size demand growth, mix, and tariff headroom.
Watchlist
Financials: Federal Reserve Senior Loan Officer Opinion Survey (Federal Reserve; quarterly U.S. bank lending standards and loan demand).
Consumer Discretionary: Shanghai Shipping Exchange’s SCFI (Shanghai Shipping Exchange; weekly container spot rates for major export lanes).
Real Estate: Green Street Commercial Property Price Index (Green Street; monthly U.S. commercial property pricing levels).
Utilities: EIA Electric Power Monthly (U.S. Energy Information Administration; U.S. utility generation mix, sales volumes, and average retail prices).
Health Care: FDA CDER monthly approvals report (U.S. Food and Drug Administration, Center for Drug Evaluation and Research; counts and labels for new drugs/biologics).
Industrials: ISM Manufacturing PMI – Supplier Deliveries index (Institute for Supply Management; monthly gauge of vendor delivery speed).
Consumer Staples: BLS CPI ‘Food at Home’ (U.S. Bureau of Labor Statistics; monthly U.S. grocery price inflation).
Materials: LME Copper Cash Price (London Metal Exchange; daily benchmark for physical copper).
Communication Services: Standard Media Index (Standard Media Index; monthly U.S. ad‑spend totals across major agencies and channels).
Energy: EIA Weekly Petroleum Status Report (U.S. Energy Information Administration; weekly U.S. crude inventories and refinery utilization).
Information Technology: TrendForce DRAM contract price index (TrendForce; monthly DRAM/HBM pricing for memory suppliers and buyers).
Caveats
Late‑Boshu seasonality can shift as we approach the next solar‑term window, altering the day’s defensive read toward more activity. A sharp yen intervention, a surprise in Doha, or a fast move in freight indices would flip the FX and logistics channels that underpin today’s view.
Sun Tzu Strategy View
Sun Tzu wrote: —— Know the other side and yourself, and victory is not endangered; know timing and terrain, and victory can be complete.
With USD/JPY at 161.879, elevated ocean freight, and Hormuz risk ebbing but not gone, outcomes hinge on reading routes, passages, and timing — not brute speed. Map counterparties’ constraints (power, interconnection, shipping windows) against your own cash and capacity to decide when to issue, procure, or defer.
Action: Chart critical FX, freight, and power interconnect nodes; monitor USD/JPY and Doha outcomes daily; sequence issuance and inventory around those gates.
Today’s Points
USD/JPY at 161.879 (10 consecutive up days) keeps Tokyo intervention risk front‑of‑mind and amplifies FX transmission to Financials and exporters.
Micron’s $41.46B Q3 and $50.0B Q4 guide plus Anthropic’s $65.0B Series H (valuation $965B, run‑rate $47B) show AI capex is now a multi‑$10B structural demand engine for semiconductors and cloud compute.
Shipping disruption remains tangible: IMO reported ~115 vessels and ~2,450 crew evacuated while SCFI route rates sit near $2,605/TEU (Asia→North EU) and ~$4,552/FFE (Asia→USWC), raising landed costs for Industrials and Consumer Discretionary.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.