Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
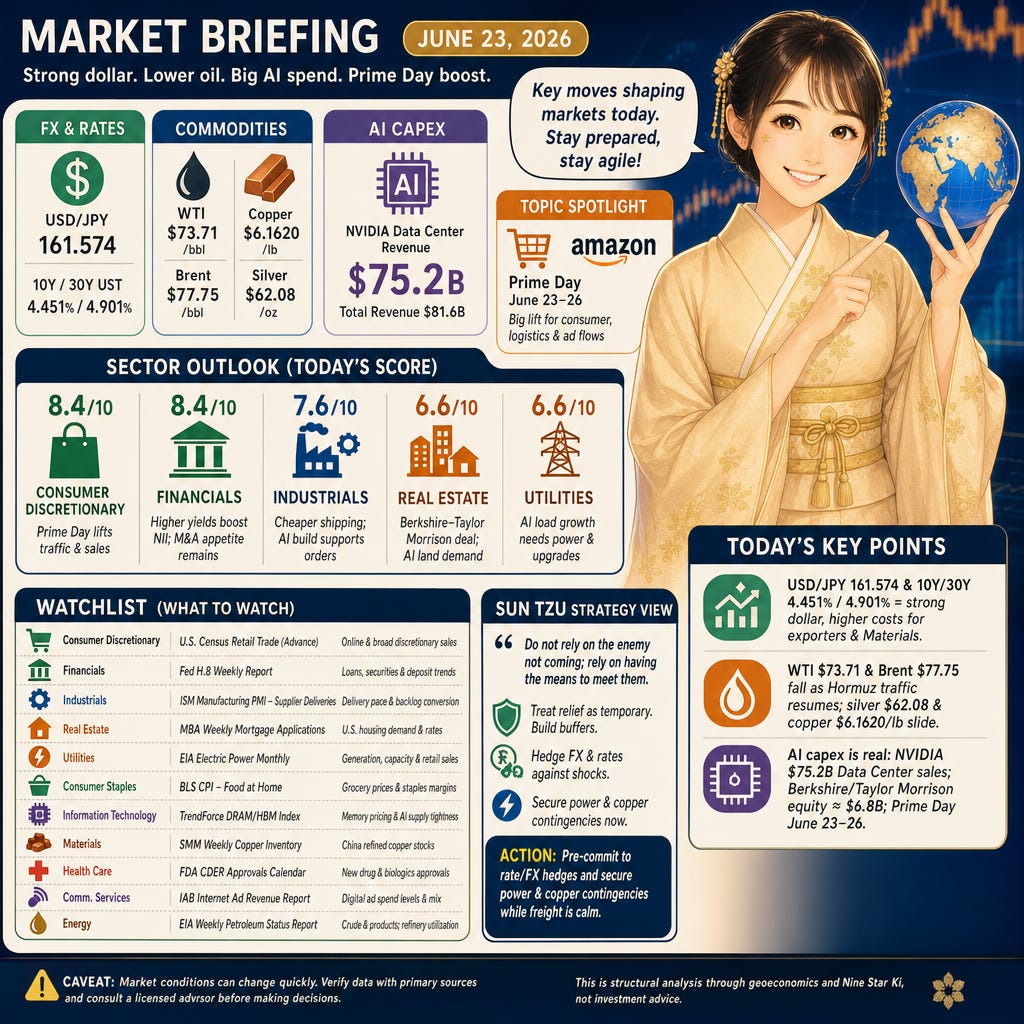
Good morning. USD/JPY at 161.574 with 10Y/30Y UST yields at 4.451%/4.901% sets a firm-dollar, higher-yield backdrop. WTI at $73.71 and copper at $6.1620/lb reflect eased chokepoint risk and softer industrial appetite. AI capex remains heavy (NVIDIA Data Center $75.2B) as Amazon Prime Day (June 23–26) concentrates consumer, logistics, and ad flows.
Paid content below this line
Stocks and FX
USD/JPY is 161.574 while U.S. 10Y/30Y Treasury yields print 4.451%/4.901% (Business Recorder reporting Reuters). Session references put the S&P 500 at 7,473 and Nasdaq at 26,167. A stronger dollar and higher long-end yields compress valuation multiples for long-duration growth names and raise FX-hedging costs. Banks’ net interest income typically benefits from elevated yields, but exporters face translation pressure and hedging expense in this tape.
Commodities
WTI is $73.71/bbl and Brent $77.75/bbl as tanker flows through Hormuz resume (Business Recorder reporting Reuters). Silver is $62.08/oz (−5.26% on the day, −18.20% month) and copper $6.1620/lb (−3.06% today), with SMM noting China copper inventories fell 16,300 mt WoW to 129,600 mt. Cheaper crude trims freight and packaging costs, easing near‑term inflation, while base‑metal weakness flags slower industrial demand and can defer Materials capex.
World Affairs
Brent at $77.75 and WTI at $73.71 accompany reports that some Iran oil sanctions were temporarily suspended and Hormuz tanker traffic resumed on June 23 (Business Recorder). Earlier reporting cited more than 800 vessels affected at the disruption’s peak. Reduced geopolitical premium lowers shipping insurance and fuel costs, easing inflation and feeding back into rates/FX expectations across Energy, Industrials, and Materials.
Supply Chain
A 16,300 mt WoW draw left China copper inventories at 129,600 mt (SMM) while tanker and LNG movements through Hormuz picked up (Business Recorder). Lower maritime insurance and steadier transit times shorten lead times and reduce spot freight volatility. But tight regional copper stocks can keep procurement prices jumpy for OEMs, complicating inventory planning in Industrials, EV supply chains, and Consumer Discretionary hardgoods.
AI
NVIDIA posted $81.6B revenue with $75.2B from Data Centers (NVIDIA investor release), and market reports highlight multi‑hundred‑million to $1B+ per month GPU rental commitments by hyperscalers (press coverage). The spend profile pulls through GPUs, optics, power gear, and cooling, tightening component lead times and sustaining data‑center construction. This supports semis and electrical equipment, while raising power and land demand that spills into Utilities and Real Estate.
Industry News
Berkshire Hathaway agreed to buy Taylor Morrison for $72.50/share, valuing it at ~$6.8B equity and ~$8.5B enterprise value (Reuters via Investing.com). Amazon confirmed Prime Day for June 23–26 (press release via BusinessWire). The deal re‑prices homebuilder comps and signals M&A appetite despite high rates; Prime Day concentrates short‑term Consumer Discretionary, Logistics, and ad auction volumes, shifting weekly revenue timing.
Industry Forecast
Today’s Setup
June 23, 2026 is a Five Yellow Earth (Goou Dosei, 五黄土星) day within a Four Green Wood month and a One White Water year during Boshu (Grain in Ear). Expect command‑center behaviors to matter: policy and FX settings transmit quickly to financing costs, while resumed energy flows relieve logistics; AI data‑center builds keep power, land, and component allocation front‑of‑mind.
Focus Sectors
Consumer Discretionary (8.4/10): Prime Day (June 23–26) concentrates traffic, checkout volume, and ad spend, lifting marketplace and logistics throughput. Resumed Hormuz flows and a firm dollar trim freight and import costs, improving unit economics where pricing holds. Watch for a post‑event air pocket and heavier promotions that can compress margins if inventory is mis‑positioned or if FX translation dulls overseas growth.
Financials (8.4/10): 10Y/30Y UST at 4.451%/4.901% with a firm dollar supports net interest income for balance‑sheet lenders and lifts hedging and trading flows. Berkshire’s ~$6.8B equity/$8.5B EV bid for Taylor Morrison signals functioning risk appetite, sustaining fees. Key risks are a sudden bull‑steepener that squeezes deposit betas and rising credit costs if higher real yields pressure housing and small‑business cash flow.
Industrials (7.6/10): Hormuz shipping resumed, lowering insurance premia and transit uncertainty, while copper at ~$6.16/lb eases some input costs despite demand worries; SMM flagged a 16,300 mt WoW inventory draw. NVIDIA’s $75.2B Data Center revenue underpins orders for power gear, cooling, and construction. A fresh chokepoint shock or delayed interconnections could push revenue right; monitor Supplier Deliveries for backlog conversion.
Real Estate (6.6/10): Berkshire–Taylor Morrison ($6.8B equity/$8.5B EV) re‑prices homebuilder comps and affirms deal appetite amid high mortgage rates. AI capex tightens land, power, and zoning capacity for data‑center sites, supporting specialized REIT pipelines, while softer oil/shipping costs marginally ease build and logistics expense. Long‑end yields cap valuations; interconnection or permitting delays can strand data‑center developments.
Utilities (6.6/10): Hyperscaler AI demand (NVIDIA DC $75.2B) drives multi‑year load growth, requiring substation upgrades and new generation; planning visibility is improving as oil stabilizes and gas remains manageable. Regulatory lag still governs cost recovery and cash flow pacing. Interconnection backlogs or delayed rate cases are the near‑term risks; fuel recovery disallowances would pressure liquidity.
Watchlist
Consumer Discretionary: U.S. Census Bureau Advance Monthly Retail Trade Report (control group and nonstore retailers — a read on online and broad discretionary sales).
Financials: Federal Reserve H.8 Weekly Report (bank assets and liabilities — loan growth, securities, and deposit trends).
Industrials: ISM Manufacturing PMI — Supplier Deliveries index (pace of deliveries; faster deliveries support backlog conversion).
Real Estate: MBA Weekly Mortgage Applications — Purchase Index (activity and rate sensitivity in U.S. housing demand).
Utilities: EIA Electric Power Monthly (U.S. electricity generation, capacity factors, and retail sales by sector).
Consumer Staples: BLS CPI — Food at Home index (price levels for grocery categories that drive staples margins).
Information Technology: TrendForce DRAM/HBM contract price index (memory pricing and supply tightness for AI accelerators).
Materials: SMM Weekly Copper Social Inventory (Shanghai Metals Market — refined copper stocks across major Chinese warehouses).
Health Care: U.S. FDA CDER drug approvals calendar (monthly new molecular entity and biologics approvals).
Communication Services: IAB Internet Advertising Revenue Report (U.S. digital ad spend levels and mix).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories and refinery utilization — near‑term supply/demand balance).
Caveats
A solar‑term shift within late June can alter how cost and demand signals propagate, so today’s read is sensitive to mid‑week data and policy headlines. A snapback in Hormuz risk or a sharp rates move would quickly change FX, valuations, and freight assumptions embedded here.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
Treat resumed shipping and lower oil as temporary relief, not a given. Build buffers where shocks bite fastest: FX hedges against a firm dollar, liquidity for higher yields, and alternative routing or inventory for metals. For AI builds, secure power and interconnections now to avoid stranded capex later.
Action: Pre‑commit to rate/FX hedges and secure power and copper contingencies while freight is calm.
Today’s Points
USD/JPY at 161.574 with 10Y/30Y UST yields at 4.451% / 4.901% keeps dollar strength and raises FX/headline risk for exporters and Materials.
WTI $73.71/bbl and Brent $77.75/bbl fell as Strait of Hormuz traffic resumed (tankers moved after talks); silver $62.08/oz and copper $6.1620/lb slid on demand/liquidation, pressuring Energy and Materials margins.
AI capex remains large and concrete: NVIDIA posted $81.6B revenue and $75.2B in Data Center sales, while corporate deals (Berkshire/Taylor Morrison equity ≈ $6.8B) and Amazon Prime Day (June 23–26) drive sector‑specific volume and M&A re‑pricing.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.