Thank you for reading. Please subscribe and support Ayanomics 9 Trends so this work can continue.
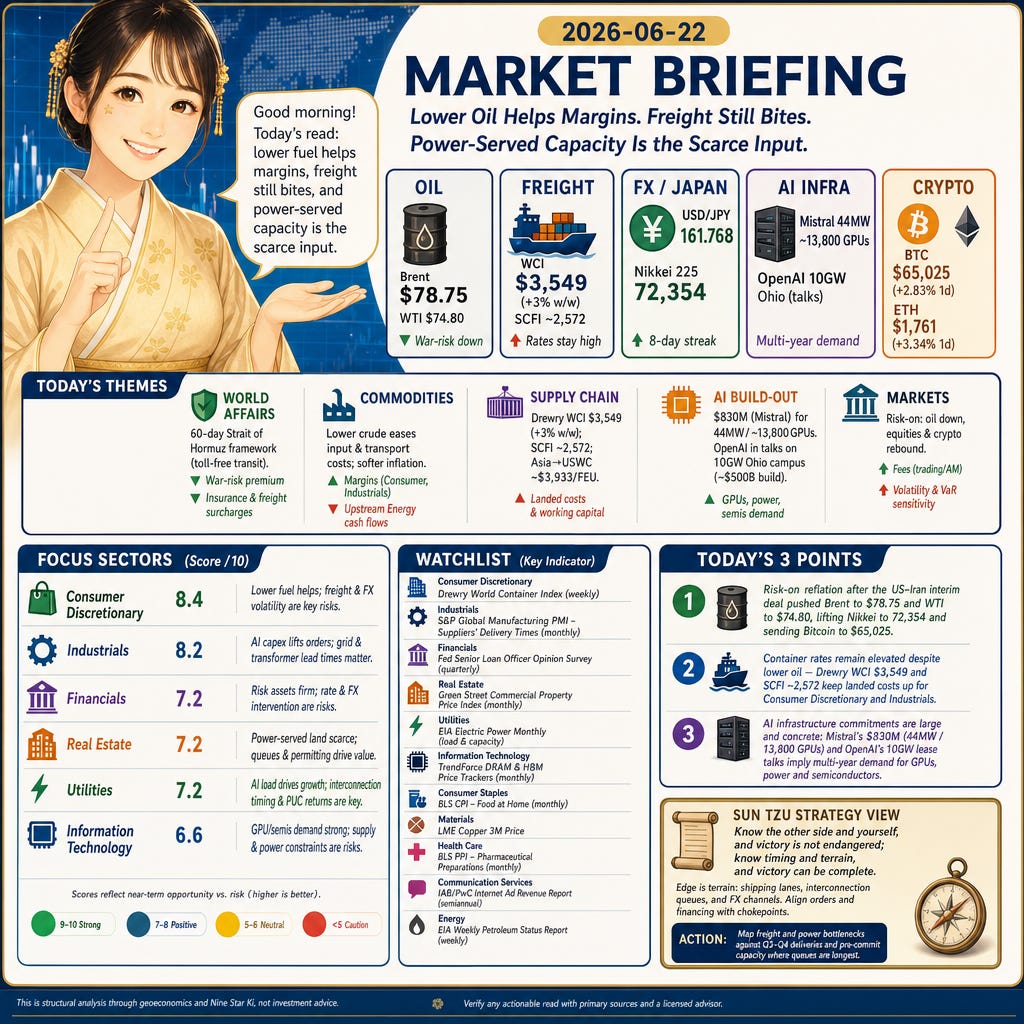
Good morning — oil sits in the mid‑$70s while container rates stay high, and AI build plans keep capex pipelines busy. The U.S.–Iran interim window trims war‑risk premia, the yen remains weak, and risk assets lean firm. Today’s read: lower fuel helps margins, freight still bites, and power‑served capacity is the scarce input.
Stocks and FX
Nikkei 225 at 72,354 (eight‑day streak) and USD/JPY 161.768 put Japan on intervention watch, per Japan Times and Reuters. A softer yen lifts dollar‑translated earnings for exporters in Information Technology and Industrials but raises the risk of a policy snap‑back. The stronger equity tape can pull global flows into Japan Financials while increasing hedge demand and FX basis volatility.
Commodities
WTI $74.80/bbl and Brent $78.75/bbl fell after reports of a U.S.–Iran interim understanding on Hormuz, according to Reuters and Investing.com. Cheaper crude eases input and transport costs for manufacturers and retailers and softens headline inflation. That supports margins in Consumer Discretionary and lowers pressure on rates, but also compresses upstream Energy cash flows and refined‑product cracks.
World Affairs
A 60‑day Strait of Hormuz reopening framework with toll‑free transit, cited by S&P Global and AP, reduces immediate war‑risk premia. Reporting referenced 55 ships and ~17 million barrels transiting in the period used by CENTCOM. The channel to markets is direct: lower insurance and freight surcharges cut costs for Industrials and Consumer sectors while trimming Energy risk pricing.
Supply Chain
Drewry’s World Container Index is $3,549 per 40ft (+3% w/w) and the SCFI sits near ~2,572, per Drewry and the Shanghai Shipping Exchange. Asia→USWC lanes are quoted around $3,933/FEU. Elevated spot rates keep landed costs high, stretch working‑capital needs, and complicate inventory turns — offsetting some of the margin relief from lower crude.
AI
Mistral’s $830 million debt raise funds a 44‑MW Paris data center with ~13,800 Nvidia GPUs, while OpenAI is in talks on a 10‑GW Ohio campus with an estimated build cost near $500 billion, per TechCrunch and Reuters. These commitments anchor multi‑year demand for GPUs, HBM memory, advanced packaging, and megawatt‑class power — supporting Information Technology suppliers and Utilities/grid investment plans.
Industry News
Bitcoin at $65,025 (+2.83% 1d) and Ethereum at $1,761 (+3.34% 1d) rebounded alongside equities as oil slipped, per CoinDesk and Investing.com. The move lifts trading and asset‑management fees in Financials and reflects risk‑on flows rotating toward AI‑linked corporates. Volatility in digital assets remains a sensitivity for broker‑dealer VaR and client margin.
Industry Forecast
Today’s Setup
2026-06-22 is a Six White Metal (Roppaku Kinsei, 六白金星) day in a Four Green Wood (Shiroku Mokusei, 四緑木星) month and a One White Water (Ippaku Suisei, 一白水星) year during Boshu (Grain in Ear). Translation: precise execution through networks wins — lower oil trims costs, elevated freight still binds, FX and power‑grid queues steer financing needs and delivery timing.
Focus Sectors
Consumer Discretionary (8.4/10): WTI $74.80 and Brent $78.75 ease fuel and packaging inputs while Drewry’s WCI at $3,549 and SCFI ~2,572 keep landed costs high. A risk‑on tape (Nikkei 72,354) supports conversion in apparel, leisure, and autos, but FX at USD/JPY 161.768 can whipsaw export pricing. Watch peak‑season GRIs and delivery reliability — freight and authorization rails determine gross margin capture.
Industrials (8.2/10): AI builds pull capex: 44 MW near Paris (~13,800 GPUs) and 10 GW in Ohio under discussion concentrate orders in switchgear, transformers, and EPC. Lower oil trims operating costs; a weak yen (161.768) aids Japan machinery exports, but elevated WCI/SCFI ties up working capital. Execution risk sits in grid interconnection and long‑lead transformers — delivery times dictate revenue timing.
Financials (7.2/10): Lower oil cools inflation while risk assets firm (BTC $65,025; ETH $1,761), supporting trading and asset‑management fees. Elevated container rates sustain trade‑finance and working‑capital demand, but potential USD/JPY intervention can jar FX revenue and hedging. Curve compression would squeeze NIM; manage VaR and liquidity buffers for crypto‑driven swings and collateral calls.
Real Estate (7.2/10): Power‑served land is scarce as data‑center plans scale — 44 MW funded in Paris and 10 GW in Ohio talks point to heavy absorption near substations. Cheaper oil may help sentiment, but interconnection queues and permitting cadence drive leasing and delivery far more than fuel. Concentration risk rises with hyperscale single‑tenant exposure; financing cost discipline remains pivotal.
Utilities (7.2/10): AI load is the growth vector: a proposed 10‑GW campus and smaller 10–100‑MW sites support rate‑base expansion and T&D upgrades. Fuel costs matter less here; timing of interconnections and allowed returns drive earnings. Equipment bottlenecks (large transformers, HV gear) and PUC cost‑recovery lags can defer spend and enlarge regulatory asset balances.
Information Technology (6.6/10): Concrete orders — ~13,800 GPUs at 44 MW and multi‑GW campus talks — sustain demand for GPUs, HBM, substrates, and advanced packaging. A soft yen aids exporters’ pricing, but packaging and HBM supply can cap shipments even with healthy orders. Project phasing keeps lead‑time management front‑and‑center; policy or power constraints at fabs are the key tail risks.
Watchlist
Consumer Discretionary: Drewry World Container Index (weekly composite spot rates per 40ft, a direct read on global container shipping costs)
Industrials: S&P Global Manufacturing PMI — Suppliers’ Delivery Times Index (monthly, tracks whether parts are arriving faster or slower)
Financials: Federal Reserve Senior Loan Officer Opinion Survey (quarterly bank lending standards and loan demand — forward read on credit creation)
Real Estate: Green Street Commercial Property Price Index (monthly, transaction-based read on U.S. commercial property pricing levels)
Utilities: EIA Electric Power Monthly (U.S. electricity sales by sector and new capacity additions — a read on load growth and build pace)
Information Technology: TrendForce DRAM and HBM contract price trackers (monthly, benchmark pricing for memory that signals supply/demand balance)
Consumer Staples: BLS CPI — Food at Home (monthly retail food inflation, a proxy for staples pricing power and consumer trade-down)
Materials: LME Copper 3-month price (London Metal Exchange benchmark for global industrial metal demand and pricing)
Health Care: BLS Producer Price Index — Pharmaceutical preparations (monthly input-cost signal for drugmakers and distributors)
Communication Services: IAB/PwC Internet Advertising Revenue Report (semiannual, authoritative measure of U.S. digital ad spend growth)
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories plus refinery utilization — near-term balance signal)
Caveats
Boshu transitions to the summer solstice period around now, so a solar‑term shift can alter near‑term emphasis from planting to peak‑load execution. The U.S.–Iran memorandum is interim; any reversal would quickly reprice oil and freight premia. FX intervention around USD/JPY 160–162 remains a live tape risk and could flip exporters’ translation tailwind.
Sun Tzu Strategy View
Sun Tzu wrote: —— Know the other side and yourself, and victory is not endangered; know timing and terrain, and victory can be complete.
Today’s edge sits in reading terrain: shipping lanes, interconnection queues, and FX channels. Align orders and financing with those chokepoints — lock freight and power where capacity is tight, and hedge yen exposure before intervention risk crystallizes.
Action: Map freight and power bottlenecks against Q3–Q4 deliveries and pre-commit capacity where queues are longest.
Today’s Points
Risk‑on reflation after the US‑Iran interim deal pushed Brent to $78.75 and WTI to $74.80, lifting Nikkei to 72,354 and sending Bitcoin to $65,025.
Container rates remain elevated despite lower oil — Drewry WCI $3,549 and SCFI ~2,572 keep landed costs up for Consumer Discretionary and Industrials.
AI infrastructure commitments are large and concrete: Mistral’s $830M (44MW / 13,800 GPUs) and OpenAI’s 10GW lease talks imply multiyear demand for GPUs, power and semiconductors, supporting Information Technology and Utilities capex.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.