Reader support is what makes Oracle Ayano possible. I am building a generative AI system for large-scale data gathering, analytical synthesis, and article verification, so each piece can offer both accuracy and a fresh perspective. Please consider supporting the project: Support Oracle Ayano.
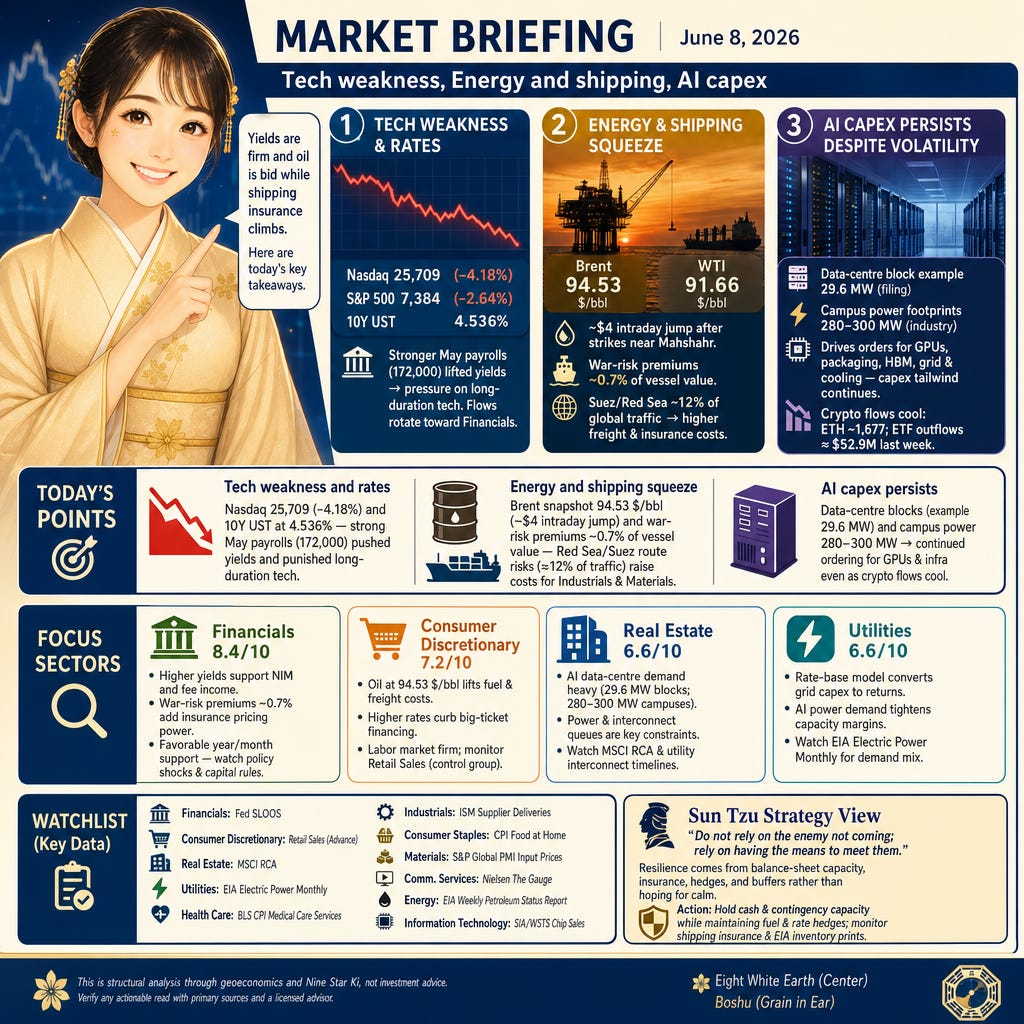
Good morning. Yields are firm and oil is bid while shipping insurance climbs, setting a defensive tone. Discount-rate pressure is hitting long-duration tech, while Energy-linked costs ripple into freight and margins. AI power builds continue to anchor capex, keeping Utilities and data‑centre Real Estate relevant even in a choppy tape.
Stocks and FX
Nasdaq 25,709 (-4.18%) and S&P 500 7,384 (-2.64%) slid after a stronger May payrolls print (172,000), with the 10Y UST at 4.536% and 30Y at 4.999% as USD/JPY reached 159.950 (Reuters). EUR/USD printed 1.1542 and GBP/USD 1.3356 after four down days. Higher discount rates compress long-duration valuations in Information Technology and Communication Services and tend to rotate flows toward Financials that monetize spread and fee income.
Commodities
Brent 94.53 $/bbl and WTI 91.66 $/bbl (Reuters snapshots) followed an intraday ~$4 jump after strikes on Iran’s Mahshahr petrochemical site. Precious metals softened with higher yields: Gold 4,354.4 $/oz and Silver 68.71 $/oz. Higher crude lifts fuel, plastics, and freight costs, pressuring Industrials and Consumer Discretionary margins while reinforcing inflation‑hedge demand that can aid Financials and some Materials names.
World Affairs
Reports cited at least 11 missiles in an early salvo as Israel and Iran exchanged strikes, with the conflict near day ~100 and roughly one‑fifth of oil flows transiting the Strait of Hormuz (Reuters). Direct hits near Mahshahr explain the >$4 Brent intraday move and add a risk premium to Energy and Materials. Safe‑haven dollar demand and shipping insurance repricing tighten global financial conditions and working capital needs.
Supply Chain
War‑risk premiums around ~0.7% of a vessel’s value on high‑risk lanes and Suez/Red Sea’s ~12% share of global traffic are extending routes and timelines (Reuters). Rerouting via the Cape adds days and bunker costs, raising landed costs and delivery uncertainty for Industrials, Consumer Discretionary, and Materials. Inventory buffers and insurance coverage become costlier, complicating seasonal planning.
AI
29.6 MW incremental data‑centre capacity in an SEC filing and campus power footprints of ~280–300 MW (industry coverage) signal sustained hyperscaler AI buildouts. That scale drives orders for GPUs, advanced packaging, and HBM memory while pulling forward grid, cooling, and real‑estate investment. The capex tailwind supports Utilities and data‑centre REITs even as higher rates pressure tech valuations (filings and industry reporting).
Industry News
ETH near 1,677 USD with ~$52.9M weekly outflows from ETH ETFs and BTC at 63,146 USD show softer crypto flows, while Coinbase reported a second straight quarterly loss and ~14% headcount cuts (Reuters, market trackers). Reduced institutional bid and platform restructuring point to lower near‑term revenue for exchanges and custody, affecting Information Technology, Financials, and Communication Services exposures tied to trading volumes.
Industry Forecast
Today’s Setup
June 8 is an Eight White Earth (Happaku Dosei) day at the Center during Boshu (Grain in Ear, started June 6), reading as consolidation: balance sheets, regulated cash flows, and operating discipline matter most. With yields elevated and oil/war‑risk premia in play, expect rate‑sensitive financing, fuel and freight costs, and power‑capacity constraints to dominate decisions over growth‑at‑any‑price narratives.
Focus Sectors
Financials (8.4/10): 10Y UST at 4.536% and firmer oil lift rate and inflation channels that support net interest margin and fee/trading income (Reuters). War‑risk premiums near ~0.7% of vessel value add specialty-insurance pricing power. Strong year/month support favors patient positioning as spreads and volumes stabilize; watch for policy shocks or Basel capital shifts that could blunt NIM gains and raise impairments.
Consumer Discretionary (7.2/10): Brent at 94.53 $/bbl and higher war‑risk insurance raise gasoline and freight costs (Reuters), while higher discount rates curb big‑ticket financing. A firm labor market cushions demand, but near‑term pass‑through and delivery reliability gate margins. Expect cleaner follow‑through once fuel and freight prints settle; watch the U.S. Census Monthly Retail Trade Report for control‑group momentum feeding GDP.
Real Estate (6.6/10): Higher Treasury yields reprice cap rates and refinancing, but AI data‑centre demand remains heavy with ~29.6 MW blocks and campus loads of ~280–300 MW (filings/industry). Power availability and interconnect queues are the binding constraints, favoring infrastructure‑adjacent cash flows over speculative builds. Debt maturity ladders matter more than leasing velocity; monitor private marks via MSCI RCA and utility interconnect timelines.
Utilities (6.6/10): The regulated rate‑base model converts grid capex into allowed returns, and AI campuses needing hundreds of MW tighten capacity margins. Fuel and LNG logistics risks add procurement complexity as oil stays near mid‑90s (Reuters). Near‑term stability improves as rate cases catch up with spend; risks include fuel spikes and weather liabilities outpacing recovery. Track EIA Electric Power Monthly for demand mix and capacity factors.
Watchlist
Financials: Federal Reserve Senior Loan Officer Opinion Survey (quarterly U.S. bank lending standards and loan demand).
Consumer Discretionary: U.S. Census Monthly Retail Trade Report (advance retail sales and the control group that feeds GDP).
Real Estate: MSCI Real Assets RCA Commercial Property Price Index (monthly private‑market commercial property values).
Utilities: EIA Electric Power Monthly (U.S. electricity generation mix, retail sales, and capacity factors).
Health Care: BLS CPI Medical Care Services index (monthly price changes for healthcare services).
Industrials: ISM Manufacturing Supplier Deliveries Index (monthly gauge of how fast suppliers are delivering to manufacturers).
Consumer Staples: BLS CPI Food at Home index (monthly grocery price inflation for consumer staples).
Materials: S&P Global Manufacturing PMI Input Prices (monthly gauge of raw‑material cost pressures across factories).
Communication Services: Nielsen The Gauge (monthly U.S. TV viewing shares for streaming vs. linear and platforms).
Energy: EIA Weekly Petroleum Status Report (weekly U.S. crude and product inventories plus refinery utilization).
Information Technology: SIA/WSTS Global Semiconductor Sales (monthly worldwide chip sales from the Semiconductor Industry Association/WSTS).
Caveats
Boshu sits early in the summer solar‑term cycle; a mid‑month transition can shift emphasis from consolidation toward activity, altering the sector tilt. If oil’s risk premium compresses quickly or yields retrace, today’s Earth‑leaning read toward Financials/Utilities/Real Estate would ease and duration assets could rebound.
Sun Tzu Strategy View
Sun Tzu wrote: —— Do not rely on the enemy not coming; rely on having the means to meet them.
With yields elevated and oil and shipping risk premia rising, resilience comes from balance‑sheet capacity, insurance, hedges, and buffers rather than hoping for calm. Financials, Utilities, and power‑rich Real Estate exemplify systems that keep functioning when shocks arrive. Build optionality in logistics, power, and funding so execution survives rate or supply hits.
Action: Hold cash and contingency capacity while maintaining fuel and rate hedges; monitor shipping insurance and EIA inventory prints for posture shifts.
Today’s Points
Tech weakness and rates: Nasdaq 25,709 (-4.18%) and 10Y UST at 4.536% — strong May payrolls (172,000) pushed yields and punished long-duration tech positions, hitting Information Technology and Communication Services.
Energy and shipping squeeze: Brent snapshot 94.53 $/bbl (Reuters reported a ~$4 intraday jump) and war‑risk premiums near ~0.7% of vessel value — Red Sea/Suez route risks (≈12% of traffic) are increasing freight and insurance costs, pressuring Industrials and Materials input costs.
AI capex persists despite volatility: filings/industry notes show data‑centre blocks (example 29.6 MW) and campus power footprints of 280–300 MW, implying continued ordering for GPUs and infrastructure even as crypto flows (ETH ~1,677; ETH ETF outflows ≈ $52.9M last week) cool digital‑asset demand.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.