


Reader support is what makes Oracle Ayano possible. I am building a generative AI system for large-scale data gathering, analytical synthesis, and article verification, so each piece can offer both accuracy and a fresh perspective.
Please consider supporting the project: Support Oracle Ayano
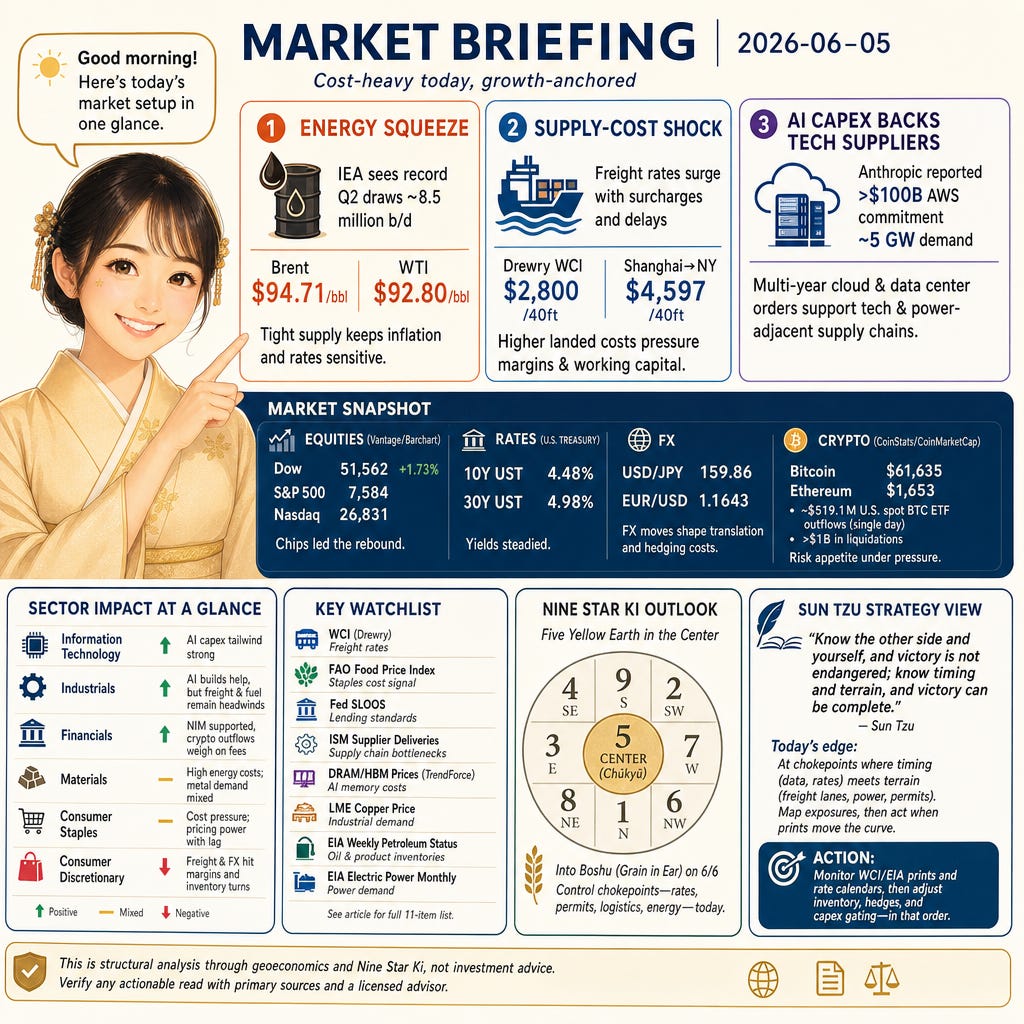
Good morning — today’s setup is cost-heavy but growth‑anchored. Oil sits in the mid‑$90s as the IEA flags record Q2 inventory draws, while container freight climbs to $2,800/40ft with added surcharges and 1–3 week delays. AI capex momentum (> $100bn over 10 years, ~5 GW demand) supports tech and power‑adjacent supply chains. USD/JPY near 159.86 and a 10Y U.S. yield around 4.48% shape translation and financing conditions.
Stocks and FX
51,562 on the Dow (+1.73%) with the S&P 500 at 7,584 and Nasdaq at 26,831, per Vantage/Barchart; chip names led the rebound as yields steadied with the 10Y UST near 4.48% and the 30Y around 4.98%. USD/JPY printed ~159.86 and EUR/USD ~1.1643 in the same session. A firmer Dow and contained rates tend to lift cyclicals (Industrials, Financials), while FX swings reshape revenue translation and hedging costs for multinationals in Information Technology and Consumer Discretionary.
Commodities
$94.71/bbl Brent and $92.80/bbl WTI in today’s tape, alongside spot gold $4,497.7/oz and silver $73.12/oz, per the IEA’s May Oil Market Report snapshot. The IEA highlights a record Q2 draw pace near ~8.5 mb/d and tight Gulf supply. Higher crude and refined‑product spreads raise transport and packaging costs, pressuring margins in goods‑heavy sectors and complicating central‑bank inflation management that feeds into rates and valuations.
World Affairs
~12.8–14.0 mb/d of Gulf supply losses since February are linked to Strait‑of‑Hormuz disruptions, with Brent near $94.71 and WTI $92.80, according to the IEA and industry coverage. The oil shortfall transmits through higher import bills and inflation, influencing rate paths and FX. That affects Energy producers’ realizations, Financials via policy and curve shifts, and Industrials through fuel and freight costs.
Supply Chain
$2,800 per 40‑ft on Drewry’s WCI, Shanghai–New York at $4,597/40‑ft, and Shanghai–Rotterdam at $2,861/40‑ft, with ONE’s $2,000/40‑ft peak‑season surcharge and 7–21 extra transit days, per Daily Cargo News. Elevated ocean rates lift landed costs and tie up working capital as goods sit in transit. Consumer Discretionary, IT hardware OEMs, and Industrials face assortment and delivery‑window risk if delays persist.
AI
$100 billion in Anthropic–AWS cloud commitments over 10 years and ~5 GW of AI compute demand, with a $5.0 billion immediate investment from Amazon, per Associated Press coverage in The Independent. Multi‑year capex and bookings lift demand for GPUs, HBM memory, advanced packaging, racks, and power, supporting Information Technology suppliers and data‑center ecosystems. Utilities and power‑adjacent Real Estate see clearer load and leasing pipelines.
Industry News
$61,635 for Bitcoin and $1,653 for Ethereum during a multi‑day slide, with ~$519.1M in single‑day U.S. spot BTC ETF outflows and >$1B in liquidations, per CoinStats/CoinMarketCap. Shrinking crypto risk appetite pressures exchange and custody fees across Financials and some IT/Comm‑Services names, while volatility can still lift trading activity in select pockets.
Industry Forecast
Today’s Setup
On 2026-06-05, Five Yellow Earth (Goou Dosei, 五黄土星) sits in the Center (Chūkyū, 中宮) for both day and month, concentrating decision rights and standards while the One White Water year favors network flow. Into Boshu (Grain in Ear) on 2026-06-06, today rewards control of chokepoints — rates, permits, logistics, and energy — making cost pass‑through, financing terms, and delivery reliability the operative edges.
Focus Sectors
Information Technology (7.6/10): >$100bn in Anthropic–AWS spend and ~5 GW compute needs extend multi‑year demand for GPUs, HBM, advanced packaging (CoWoS), racks, and power gear; chip leaders drove the equity tape. This supports backlog visibility and pricing power across AI supply chains. Risks: capacity concentration in HBM/packaging, export‑control frictions, and freight delays that push quarter‑end shipments.
Industrials (7.6/10): Drewry’s WCI at $2,800/40‑ft and 7–21 day re‑routes raise diesel/jet costs and working‑capital needs, slowing backlog conversion on fixed‑price or tight‑margin work. Offsetting, multi‑GW AI data‑center builds pull through switchgear, transformers, and thermal systems. Watch supplier deliveries and permitting/grids; risks are sustained fuel/freight elevation and grid‑connection delays deferring revenue.
Financials (7.6/10): A 10Y UST near ~4.48% and 30Y ~4.98% supports bank NIM (net interest margin) while inflation risk from mid‑$90s oil keeps curve volatility live. Crypto ETF outflows (~$519M in a day) compress exchange/fintech fee lines even as FX vol can aid FICC trading. Key risks: faster deposit beta, capital/liquidity rule shifts, and CRE refinancing strain if cap rates reset higher.
Materials (7.6/10): IEA‑flagged tight oil balances keep energy inputs elevated — a headwind for energy‑intensive chemicals — while firm industrial‑metal benchmarks can support miners’ netbacks. Higher ocean freight reshapes arbitrage and inventory staging, favoring flexible routing. Expect dispersion between miners and chemicals. Risks: sustained power/fuel costs, port congestion, and China demand softness; LME copper is the demand bellwether.
Consumer Staples (7.6/10): WCI $2,800/40‑ft and mid‑$90s oil lift transport and packaging inputs; staples can pass a portion through via shelf pricing and contracts, typically with a lag. Defensive cash generation holds if replenishment routes stay stable. Risks: spikes in agri commodities or resin costs outpacing pass‑through and retailer pushback forcing promo spend; watch FAO food prices for COGS pressure.
Consumer Discretionary (7.6/10): WCI $2,800/40‑ft, $2,000/40‑ft peak‑season surcharges, and 7–21 day delays raise landed costs and tie up inventory in transit, pressuring gross margins and working capital. USD/JPY ~159.86 also shifts revenue translation and hedging for global brands. Execution on assortment timing and markdown discipline is pivotal; risks include further surcharges and port congestion into peak season.
Watchlist
Consumer Discretionary: Drewry World Container Index (Drewry; weekly global container freight rates per 40‑ft box across key lanes).
Consumer Staples: FAO Food Price Index (FAO; monthly global basket of food commodity prices that drive COGS for many staples).
Financials: Federal Reserve SLOOS (Senior Loan Officer Opinion Survey; quarterly U.S. bank lending standards and loan‑demand conditions).
Industrials: ISM Manufacturing PMI — Supplier Deliveries Index (Institute for Supply Management; monthly delivery‑time gauge that signals bottlenecks/ease in supply chains).
Information Technology: TrendForce DRAM/HBM contract price tracker (TrendForce; periodic pricing for DRAM and high‑bandwidth memory used in AI systems).
Materials: LME Copper official cash price (London Metal Exchange; daily benchmark for refined copper pricing, a bellwether for industrial metals demand).
Communication Services: Standard Media Index (SMI) — U.S. Ad Market Tracker (SMI; monthly national advertising spend across media owners and formats).
Energy: EIA Weekly Petroleum Status Report (U.S. Energy Information Administration; weekly crude/product inventories and refinery utilization).
Health Care: FDA CDER Drug and Biologic Approvals (U.S. Food and Drug Administration; monthly listing of new approvals influencing revenue ramps).
Real Estate: Green Street Commercial Property Price Index (Green Street; monthly private‑market pricing for U.S. commercial real estate).
Utilities: EIA Electric Power Monthly (U.S. Energy Information Administration; monthly U.S. electricity generation, sales, and average revenue per kWh).
Caveats
Boshu (Grain in Ear) begins 2026-06-06, shifting emphasis from coordination to throughput; freight and energy prints around that transition can alter the margin read quickly. If the rate path or Gulf supply picture changes materially (policy surprise, route reopening), today’s sector balance between cost pass‑through and capex pull would need recalibration.
Sun Tzu Strategy View
Sun Tzu wrote: —— Know the other side and yourself, and victory is not endangered; know timing and terrain, and victory can be complete.
Today’s edge sits at chokepoints where timing (data releases, rate decisions) meets terrain (freight lanes, power access, permitting). Map your exposures to these nodes, then sequence actions to when prints move the curve or inventories. Getting both right preserves margin and financing optionality while others react late.
Action: Prioritize monitoring of WCI/EIA prints and rate‑setting calendars, and adjust inventory, hedges, and capex gating in that order.
Today’s Points
Energy squeeze: IEA sees Q2 draws ~8.5 million b/d while Brent trades at $94.71/bbl and WTI at $92.80/bbl — downside to inventories keeps inflation and rates sensitive.
Supply-cost shock: Drewry WCI $2,800/40ft and Shanghai→New York at $4,597/40ft (ONE PSS $2,000/40ft) lift landed costs for Consumer Discretionary and IT hardware, pressuring margins and working capital.
AI capex backs tech suppliers: Anthropic’s reported >$100 billion AWS commitment and ~5 GW demand signal sustained multi‑year cloud/data‑center orders, benefiting Information Technology and Communication Services suppliers even as crypto outflows (~$519.1M ETF redemptions) sap risk appetite.
This is structural analysis through geoeconomics and Nine Star Ki, not investment advice. Verify any actionable read with primary sources and a licensed advisor.
@welfarearch Thanks for the like. I am glad you read it.